
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Pirelli (BIT:PIRC) Limited Edition Speedboat Partnership
- Pirelli & C, Ducati and SACS Marine have released the limited-run Pirelli 44 Ducati Edition speedboat, unveiled at the 2026 Cannes Yachting Festival with just 26 units planned and pricing expected to exceed €1 million per boat.
- The project ties Pirelli’s marine manufacturing know how to Ducati’s Superleggera V4 Centenario design, reinforcing the tire maker’s premium brand positioning across performance-focused, high price point mobility segments.
- This limited edition Pirelli 44 Ducati Edition collaboration could influence Pirelli & C’s broader investment narrative.
Scan other premium mobility players that echo the high-end positioning of Pirelli & C by moving through our hand picked 617 high quality undiscovered gems that focus on performance, branding and pricing power.
Pirelli & C Investment Narrative Recap
To own Pirelli & C, you need to be comfortable with a tire group that leans heavily into premium, performance and EV compatible products, backed by a long track record and global reach. The key near term swing factor is execution on high value capacity, cost control and pricing power while dealing with tariffs, FX and raw material costs.
The Pirelli 44 Ducati Edition fits the brand story but is not a material earnings driver. It mainly reinforces positioning around high end mobility, which can support relationships with prestige OEMs. The bigger risk in the near term still comes from trade policy shifts and any weakness in premium vehicle demand rather than niche lifestyle projects.
The most relevant recent announcement is the broader Ducati centenary collaboration. The Pirelli 44 I Ducati Edition speedboat uses triple Mercury Racing engines and targets speeds up to 120 km/h at a price above €1,000,000. For an investor, the key takeaway is not the unit economics of 26 boats but the branding halo around performance and luxury.
That halo effect feeds back into the core catalysts analysts already watch. Pirelli & C is pushing premium tire tech, smart and EV focused products, and deeper ties with high end OEMs in Europe, North America and Asia. Branded projects like this can support pricing, but they do not offset risks from tariffs, currency swings, raw material costs or a potential slowdown in high value tire demand.
Pirelli & C's current analyst narrative points to revenue of €7.5b and earnings of €561.9 million by 2029. This assumes yearly top line growth of 2.1% and an earnings increase of about €39.5 million from the current €522.4 million level.
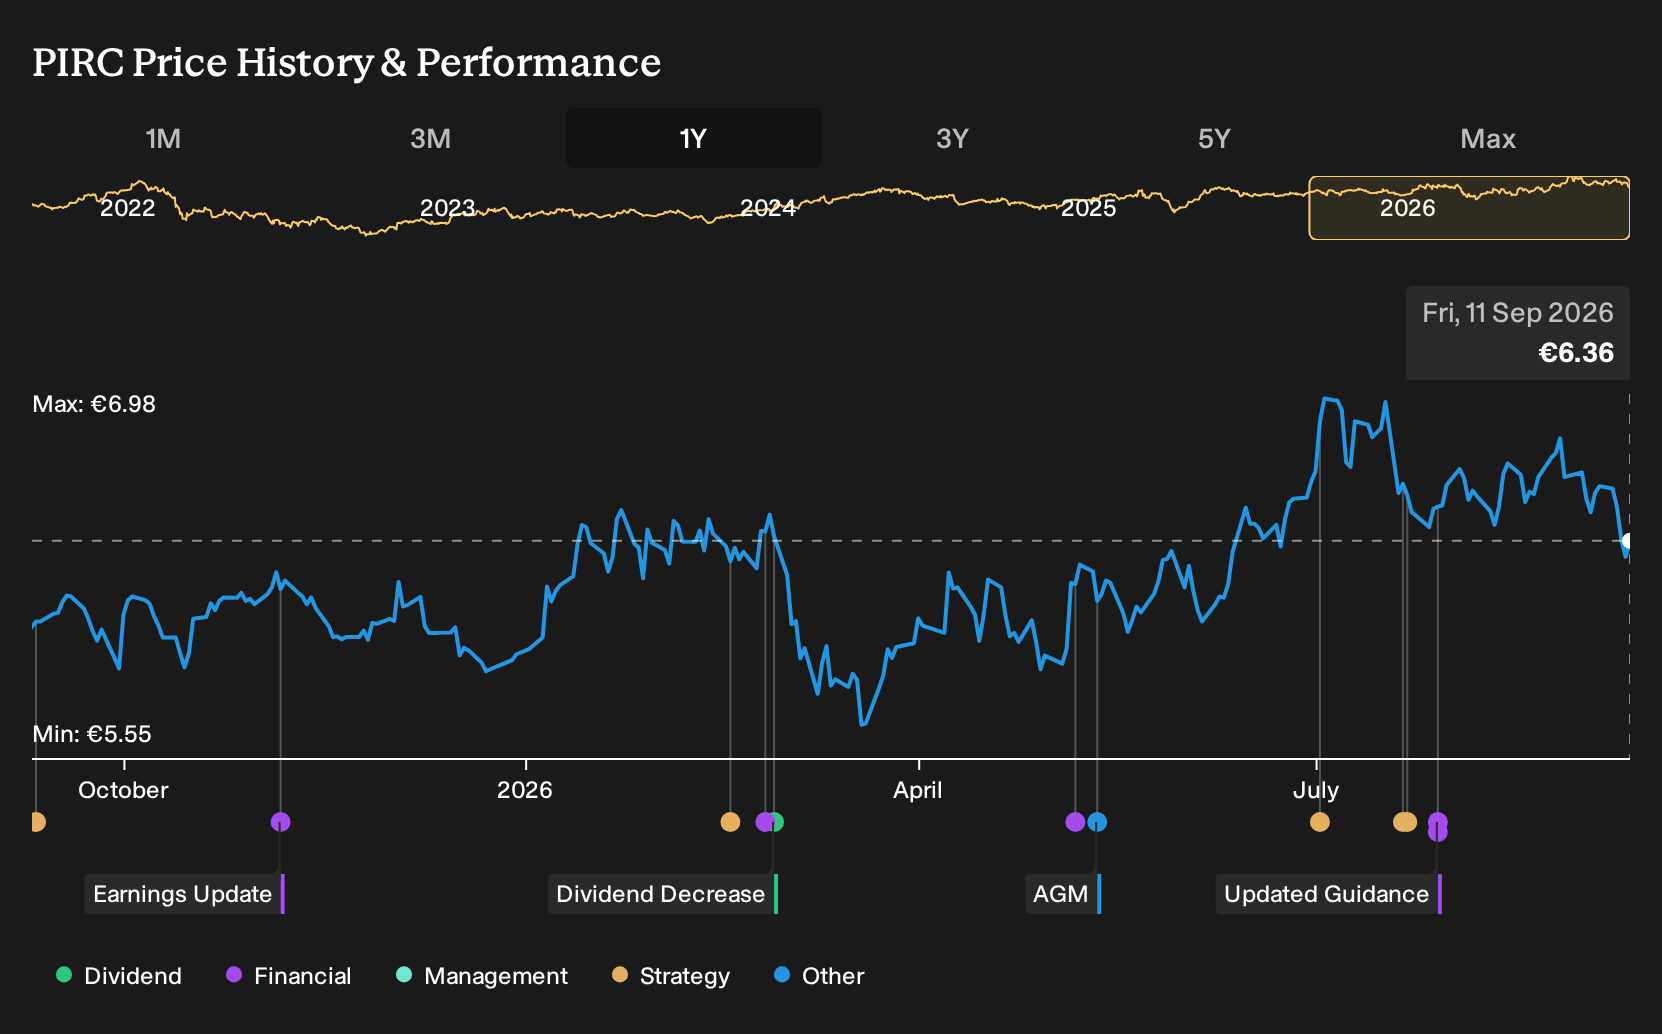
Uncover why Pirelli & C's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight band between €7.06 and about €7.78, showing how even a small group of private investors can disagree. Consider these views alongside tariff risk, currency swings and Pirelli & C’s EV and smart tire projects, then compare several alternative viewpoints yourself.
Explore another Pirelli & C fair value estimate, including one that suggests potential upside of up to 22% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Pirelli & C research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pirelli & C. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pirelli & C's overall financial health at a glance.
Looking for more investment ideas beyond Pirelli & C?
If the Pirelli & C story has sharpened your thinking about pricing power, balance sheet strength and income resilience, it can help to compare it with a wider set of businesses that fit similar themes. The Simply Wall St Screener lets you quickly move from a single stock to a broader watchlist that reflects how you want risk, quality and dividends to work together in your portfolio.
- For investors who care most about financial resilience and clean balance sheets, start with a list of solid balance sheet and fundamentals (194 results) that keeps debt and liquidity risk in clear view.
- If you prefer companies where the market may not fully reflect fundamentals, scan a 182 high quality undervalued stocks and see which businesses offer quality at a compressed price tag.
- For readers building income focused portfolios, focus on steady cash returns by reviewing a 162 dividend fortresses that screens for higher yielding payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com