
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Altria (MO) Stock May Still Be Undervalued On Earnings Power
Altria Group has delivered robust long term returns, and that kind of run always raises the same question for fresh capital. Is the current share price asking too much of the company’s earnings power, or are investors still paying a reasonable figure for what the business is generating today?
- Over the past 5 years the stock has returned about 107.1%, which puts real pressure on the question of how much earnings strength is already baked into the valuation.
- The business depends heavily on converting steady tobacco cash flows into shareholder returns, so the durability of those earnings streams can matter a lot for how investors judge today’s multiple.
- There is a second opinion on Altria Group worth weighing. See what analysts think Altria Group's shares could be worth.
The issue now is whether the earnings profile behind Altria Group is strong enough to justify where the share price sits today.
If you are weighing whether Altria Group’s earnings justify today’s price and want a broader starting point for research, it can help to compare it with 32 high quality undervalued stocks.
Is Altria Group a Bargain on Earnings?
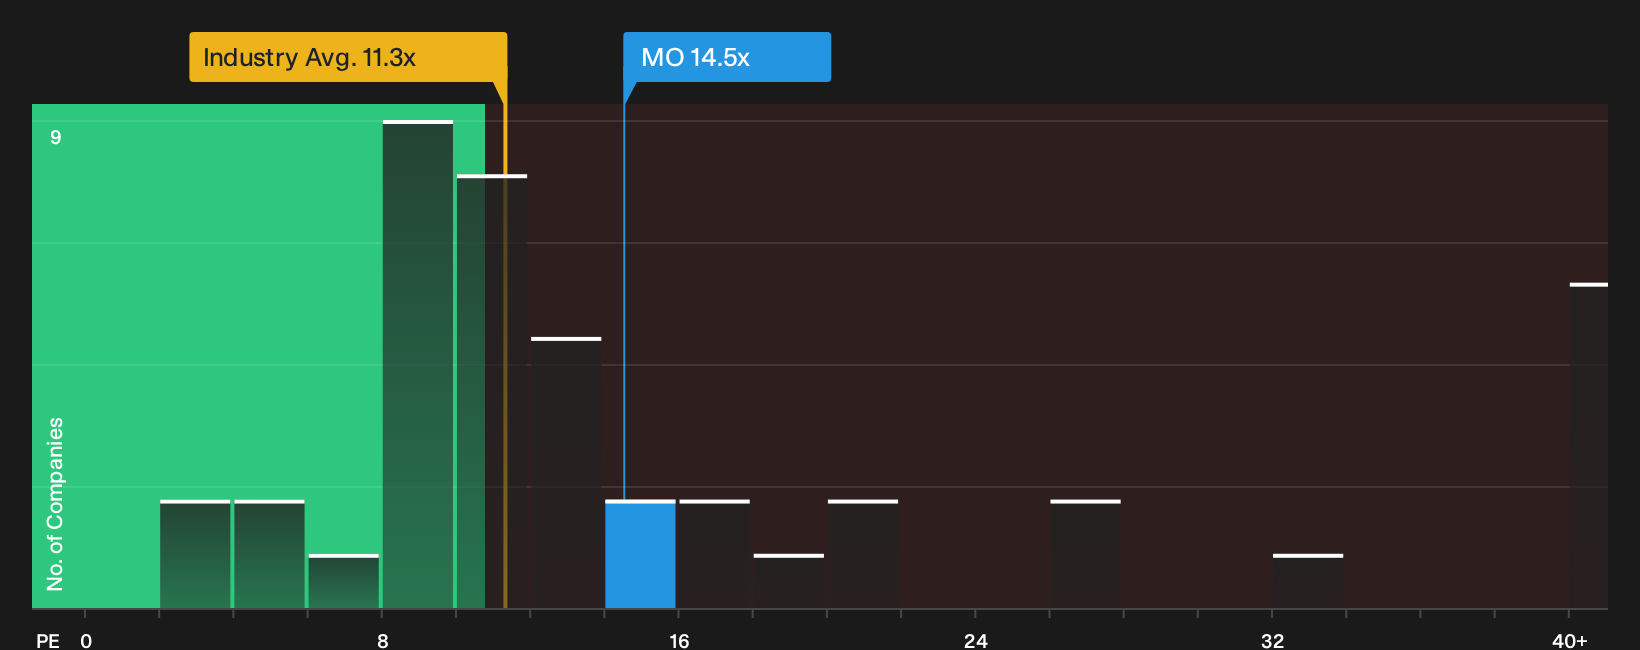
The P/E ratio fits Altria Group because earnings remain the key anchor for how investors judge a mature, cash focused tobacco business. On this measure, the stock trades on about 14.5x earnings, which is above the tobacco sector average of roughly 11.1x. That puts a premium on the shares relative to many direct competitors that sit closer to 32.7x on average across a broader peer set.
A tailored fair P/E for Altria Group that blends its growth profile, profitability, size and risk points to a higher figure than where the shares change hands today. The current 14.5x therefore screens as undervalued against that reference point, suggesting the market is assigning a lower price tag to each dollar of profit than the model implies might be justified. For anyone assessing the stock, the open question is whether Altria Group’s earnings quality and risk profile align with that lower market multiple or with the higher benchmark the fair value framework is flagging. Explore the numbers behind Altria Group's P/E valuation.
The Altria Group Narrative: What Would Justify Today's Price?
Narratives for Altria Group pick up where the valuation puzzle leaves off. They spell out which paths for future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than it is today, and they sit on Simply Wall St's Community page. Instead of only giving a single output from a ratio or model, these scenarios lay out the future that figure rests on so you can watch how real world results line up with it.
Community views on Altria Group split between those who see enough earnings power in smoke free plans and those who worry regulation and illicit products could cap the upside.
Bull case: roughly fairly valued
"Altria leverages strong tobacco margins, growing oral products, strategic marketing, and e-vapor initiatives to drive stable earnings and shareholder value..."
Discover why this Narrative puts Altria Group at roughly fairly valued.
Bear case: 17% overvalued
"Altria's smoke-free product segment, including NJOY and on!, is threatened by the rapid growth of illicit e-vapor products, which now account for over 60% of the market..."
Explore why this Narrative puts Altria Group at 17% overvalued.
Altria Group’s price is only one side of the story
Your view on Altria Group gets sharper when you line up today’s earnings multiple with where professional forecasts expect profits and cash flows to land over the next few years. Explore where analysts expect Altria Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com