
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why NCR Voyix Stock Is Rising Recurring Revenue And What's Next
- NCR Voyix reported second quarter revenue that fell 21% year over year after exiting its hardware operations, while underlying software and services activity grew 1% and contract value tied to the Voyix Commerce Platform rose 65%.
- The firm kept its full year outlook intact and repurchased US$11 million of shares, which points to management confidence in the software and payments transition despite headline revenue pressure.
- We will now look at how NCR Voyix's investment narrative could be shaped by its revenue mix shift toward higher recurring software streams.
Scan beyond NCR Voyix and evaluate other large software companies making similar shifts toward recurring platforms with our curated 32 high quality undervalued stocks.
NCR Voyix Investment Narrative Recap
To own NCR Voyix, you need to believe the pivot away from hardware and toward software, payments and the Voyix Commerce Platform can offset headline revenue pressure over time. The latest quarter largely reinforces that story. Top line fell as expected after the hardware exit, while underlying software and services activity and contract value still moved in the right direction.
For the near term, the key swing factor remains execution on recurring software adoption and payments volumes. The biggest risk is that transition costs and elevated capital spending continue to weigh against earnings while hardware related revenue steps down, especially given existing concerns about interest coverage and the impact of one off items on recent results.
The clearest new datapoint tied to this catalyst is the 65% rise in Remaining Contract Value for the Voyix Commerce Platform. That figure gives you a cleaner view of how much work NCR Voyix has already signed onto its platform, even as reported revenue is reshaped by the hardware exit and restructuring noise.
Repurchasing US$11 million of stock and keeping full year guidance unchanged sits against this operational backdrop. For you as an investor, the more practical questions are whether recurring software and payments contracts keep compounding from here, and whether that is enough to offset risks around forecast revenue and earnings declines and tighter room on interest coverage.
NCR Voyix's narrative projects US$2.0b revenue and US$5.6 million earnings by 2029. This assumes revenue declines at about 10.1% per year and earnings fall by US$36.4 million from US$42.0 million today.
Uncover why NCR Voyix's fair value indicates a 50% potential upside to its current price that could narrow quickly.
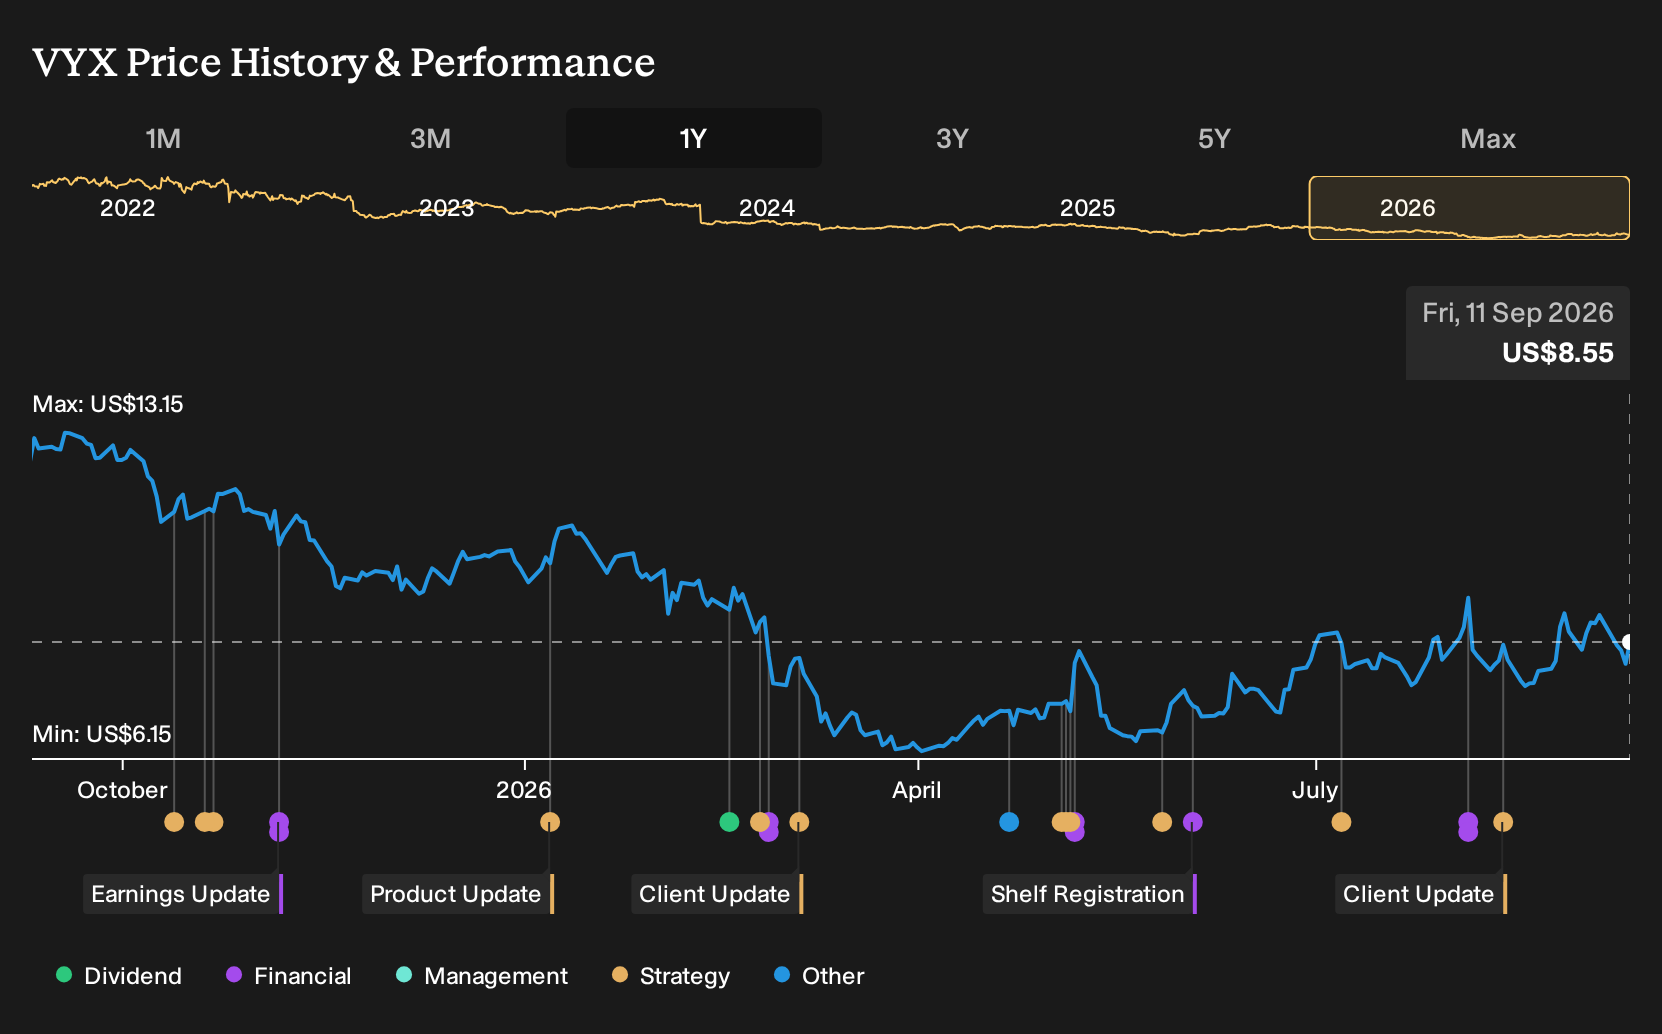
Exploring Other Perspectives
One alternate view on NCR Voyix leans hard into execution risk on the outsourced hardware shift. The most pessimistic analysts were already modeling revenue declining about 9% a year and earnings easing from US$42.0 million to roughly US$5.0 million by 2029. You can treat today’s results as a fresh test of those assumptions and consider how opinions might reset.
Explore 3 other NCR Voyix fair value estimates, including one that suggests it could be worth just $9.75.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NCR Voyix research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NCR Voyix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCR Voyix's overall financial health at a glance.
Looking For More Investment Ideas Beyond NCR Voyix?
Once you have a view on NCR Voyix, it can help to compare it with other opportunities that match your risk tolerance, income needs, and balance sheet preferences. The Simply Wall St Screener lets you filter for exactly the type of businesses you want to research next.
- If you are hunting for potential mispricings with stronger fundamentals, start with a curated group of 15 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation sits near the top of your list, narrow your focus to companies in the 11 resilient stocks with low risk scores and see how their risk profiles compare with what you own today.
- If balance sheet strength matters most to you, filter for businesses in the list of solid balance sheet and fundamentals (23 results) and line them up against your current watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com