
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hammond Power Solutions (TSX:HPS.A) Raises Dividend As The Undervalued Narrative Holds
Hammond Power Solutions (TSX:HPS.A) has raised its quarterly cash dividend to $0.29 per Class A and Class B share, a 5.5% increase that puts income returns in clearer focus for shareholders.
Recent trading shows that momentum in Hammond Power Solutions has cooled over the past quarter. The 90-day share price return is down 21.52% and the 30-day share price return is down 4.64%, even as the year-to-date share price return sits at 56.22% and the 1-year total shareholder return is 123.93%.
Scan Hammond Power Solutions alongside other income-focused opportunities by reviewing our hand picked 2 dividend fortresses that combine higher yields with a focus on resilience.
Hammond Power Solutions now combines a richer dividend with a share price that has cooled after a strong 1 year run. Strong business, weaker recent momentum. Is that combination actually priced fairly today?
Most Popular Narrative: 30% Undervalued
Against a last close of CA$253.85, the most followed narrative for Hammond Power Solutions pegs fair value at about CA$362.71, which points to a wide gap that investors need to understand before leaning too heavily on the higher dividend.
The ramp-up of new manufacturing facilities in Mexico, with expectations to be fully loaded and operational by early next year, will significantly increase production capacity, positioning Hammond to capture greater share of increasing North American demand and support long-term revenue growth while enabling improved operating leverage and margin expansion.
See why 37 investors see Hammond Power Solutions as 30% undervalued.
The narrative uses a discount rate of about 8.55% and assumes revenue growth of roughly 27.28% a year and profit margins near 8.23%, which together support that CA$362.71 fair value estimate. Those assumptions also line up with analyst expectations for earnings growth around 32% per year, faster than the broader Canadian market and the firm’s own historical five year profit expansion of 25.5% per year.
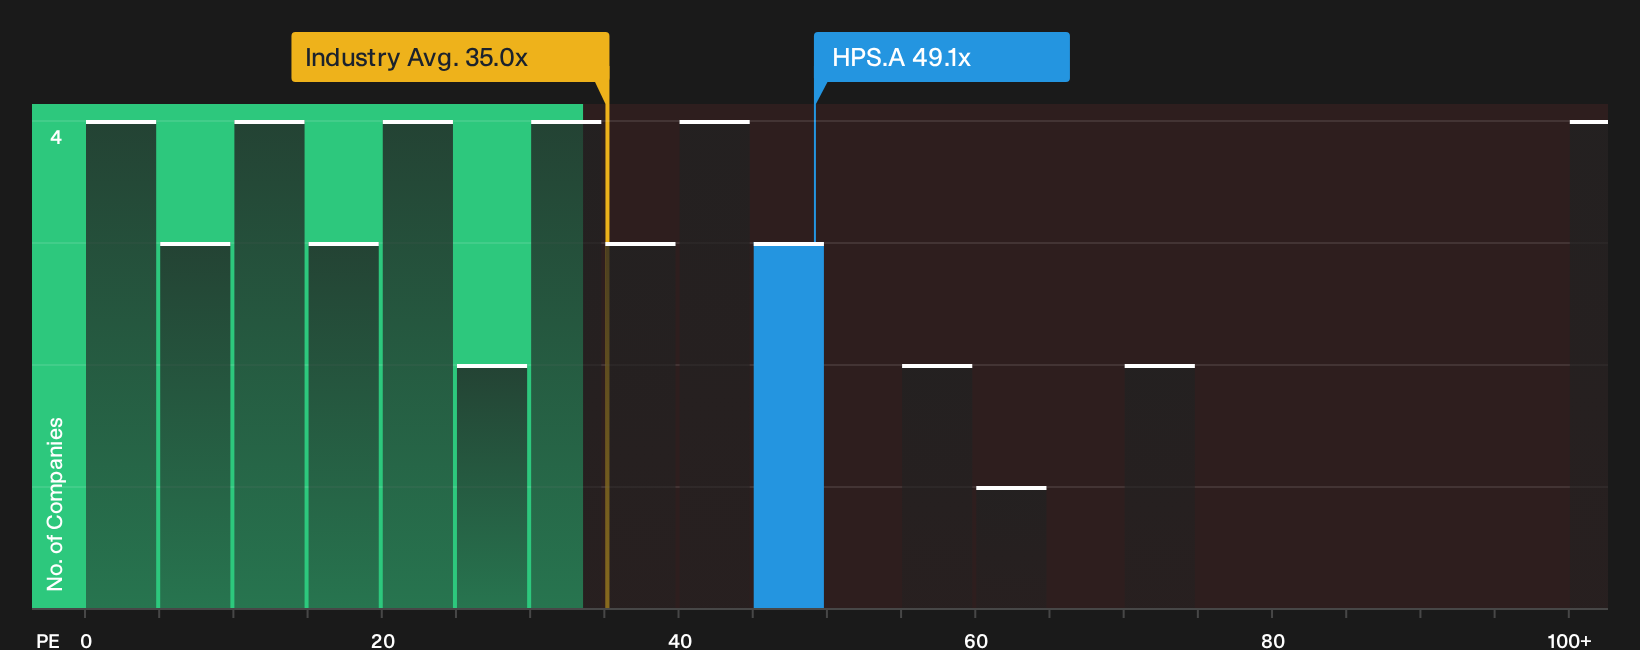
At the same time, the narrative sits alongside some cooling in recent share price performance, a current net profit margin of 5.8% that is below last year’s 9.6%, and a P/E ratio of 49.1x that is higher than both the North American Electrical industry average of 35x and an estimated fair P/E of 44.3x. That mix suggests the market already prices in a meaningful portion of the growth story even though the narrative sees more room based on those discounted cash flow style assumptions.
Result: Fair Value of CA$362.71 (UNDERVALUED)
Still, that upbeat Hammond Power Solutions story can crack if material costs stay stubbornly high or if new Mexican capacity takes longer to run efficiently.
Find out about the key risks to this Hammond Power Solutions narrative.
Another View: Hammond Power Solutions Through The P/E Lens
Analyst models see Hammond Power Solutions as about 30% undervalued on those growth and cash flow style assumptions. The simple earnings multiple paints a very different picture. The current P/E is 49.1x, versus 35x for the wider North American Electrical group and a fair ratio of 44.3x.
That gap signals investors are already paying more than both peers and the fair ratio. This may leave less room if expectations cool or margins stay under pressure. The question is whether you think Hammond Power Solutions has enough earnings power to keep justifying that richer tag.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals rarely resolve themselves. Consider Hammond Power Solutions in light of the hard numbers, then act promptly on your own view by checking the 2 key rewards and 2 important warning signs.
Looking for more Hammond Power Solutions style ideas?
If Hammond Power Solutions has your attention, do not stop here. A few targeted screens can surface opportunities you will not see by scrolling headlines.
- Spot potential mispricing early by scanning a focused group of 5 high quality undervalued stocks that pair solid fundamentals with compressed expectations.
- Strengthen your defensive side by reviewing a list of solid balance sheet and fundamentals (7 results) so cash flow quality and debt levels work in your favor.
- Get ahead of the crowd by checking 9 high quality undiscovered gems that have strong underlying numbers but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com