
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Reasons INSE is Risky and 1 Stock to Buy Instead
Inspired has gotten torched over the last six months - since March 2026, its stock price has dropped 25.3% to $5.10 per share. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Inspired, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Inspired Will Underperform?
Despite the more favorable entry price, we’re sitting this one out for now. Here are three reasons why INSE doesn’t excite us, plus one stock we’d rather own.
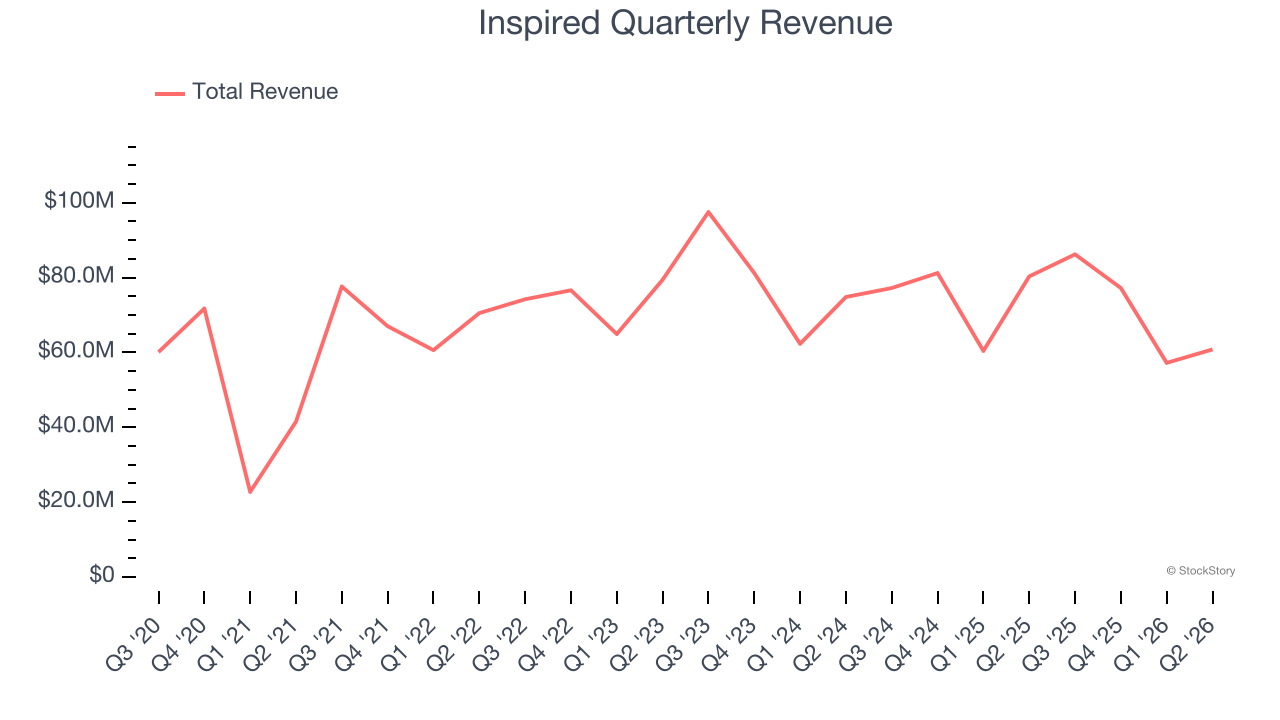
1. Long-Term Revenue Growth Disappoints
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Inspired grew its sales at a weak 7.5% compounded annual growth rate. This fell short of our benchmark for the consumer discretionary sector.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
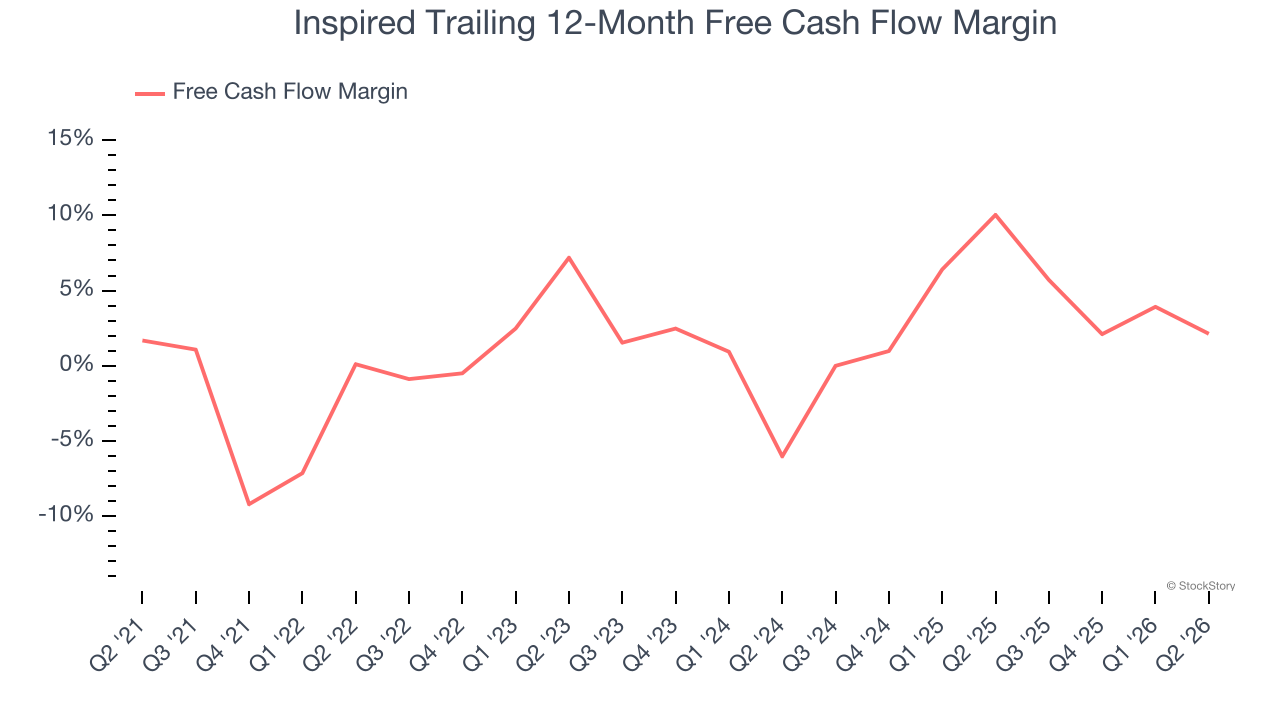
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Inspired has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 6.2%, below what we’d expect for a consumer discretionary business.
3. New Investments Fail to Bear Fruit as ROIC Declines
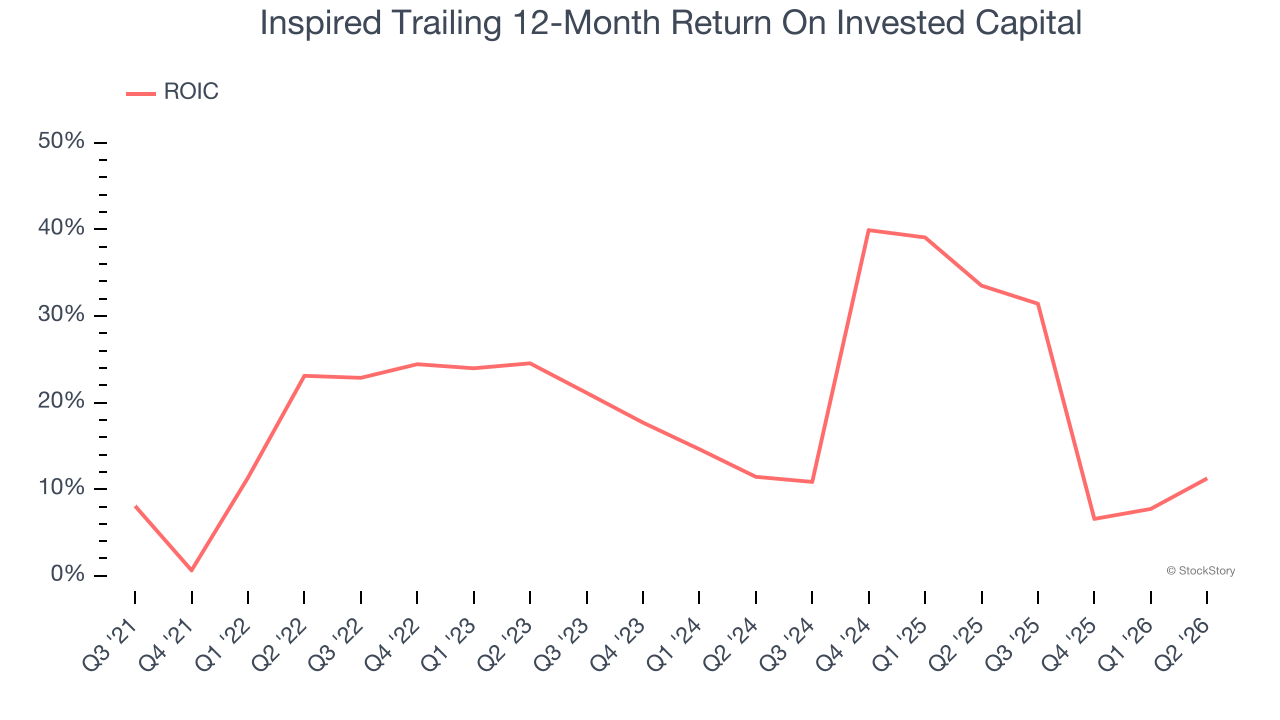
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Unfortunately, Inspired’s ROIC averaged 1.4 percentage point decreases each year over the last few years. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final Judgment
Inspired doesn’t pass our quality test. Following the recent decline, the stock trades at 23.4× forward P/E (or $5.10 per share). While this valuation is reasonable, we don’t see a big opportunity at the moment. There are better stocks to buy right now. Let us point you toward one of Charlie Munger’s all-time favorite businesses.
Stocks We Would Buy Instead of Inspired
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.