
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Reasons to Sell PNC and 1 Stock to Buy Instead
PNC Financial Services Group has had an impressive run over the past six months as its shares have beaten the S&P 500 by 8.2%. The stock now trades at $243.93, marking a 21.5% gain. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in PNC Financial Services Group, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is PNC Financial Services Group Not Exciting?
We’re happy investors have made money, but we’re sitting this one out for now. Here are three reasons we avoid PNC, plus one stock we’d rather own.
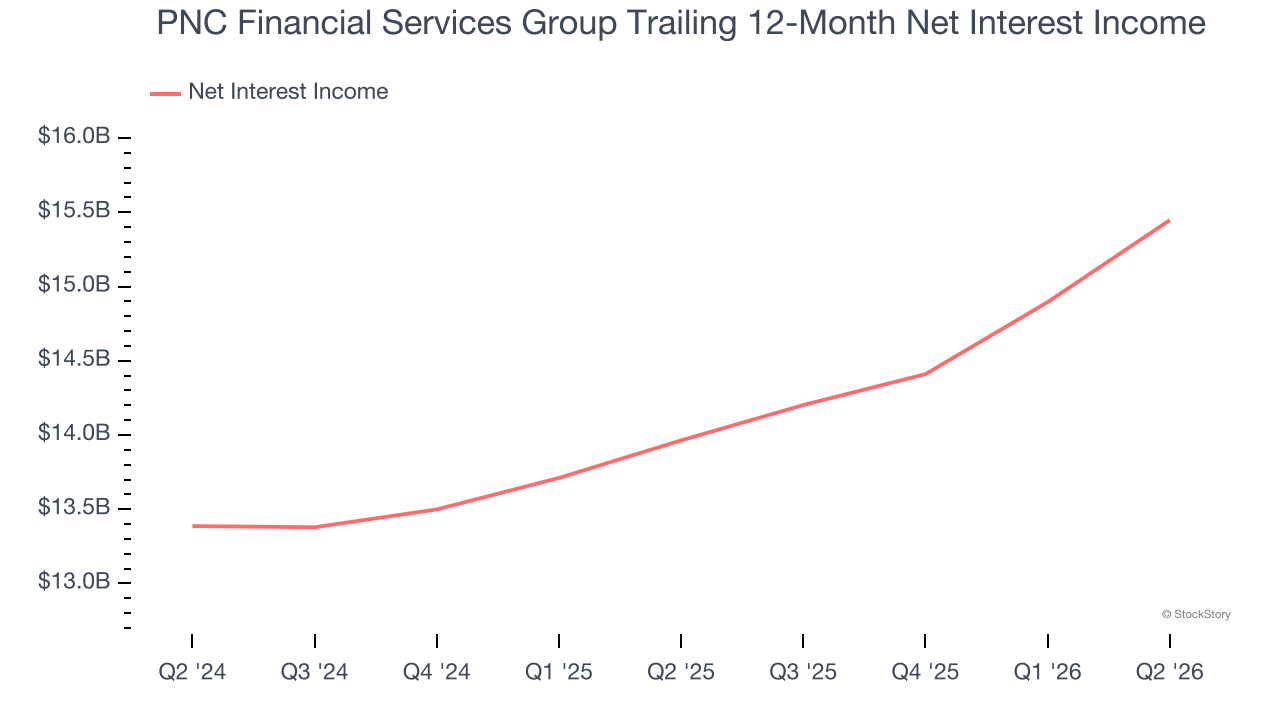
1. Net Interest Income Points to Soft Demand
Markets consistently prioritize net interest income over non-recurring fees, recognizing its superior quality compared to the more unpredictable revenue streams.
PNC Financial Services Group’s net interest income has grown at a 9.4% annualized rate over the last five years, slightly worse than the broader banking industry.
2. Low Net Interest Margin Reveals Weak Loan Book Profitability
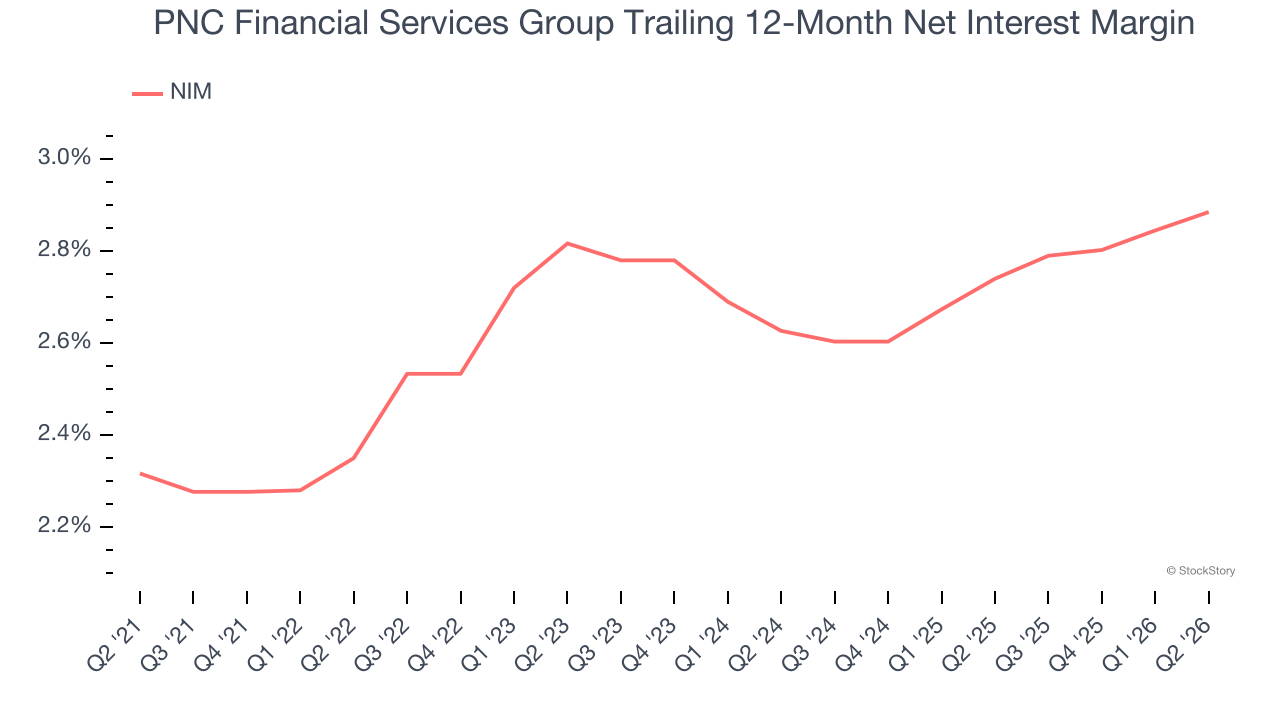
The net interest margin (NIM) is a key profitability indicator that measures the difference between what a bank earns on its loans and what it pays on its deposits. This metric measures how efficiently it can generate income from its core lending activities.
Over the past two years, we can see that PNC Financial Services Group’s net interest margin averaged a weak 2.8%, indicating the company has weak loan book economics.
3. EPS Barely Growing
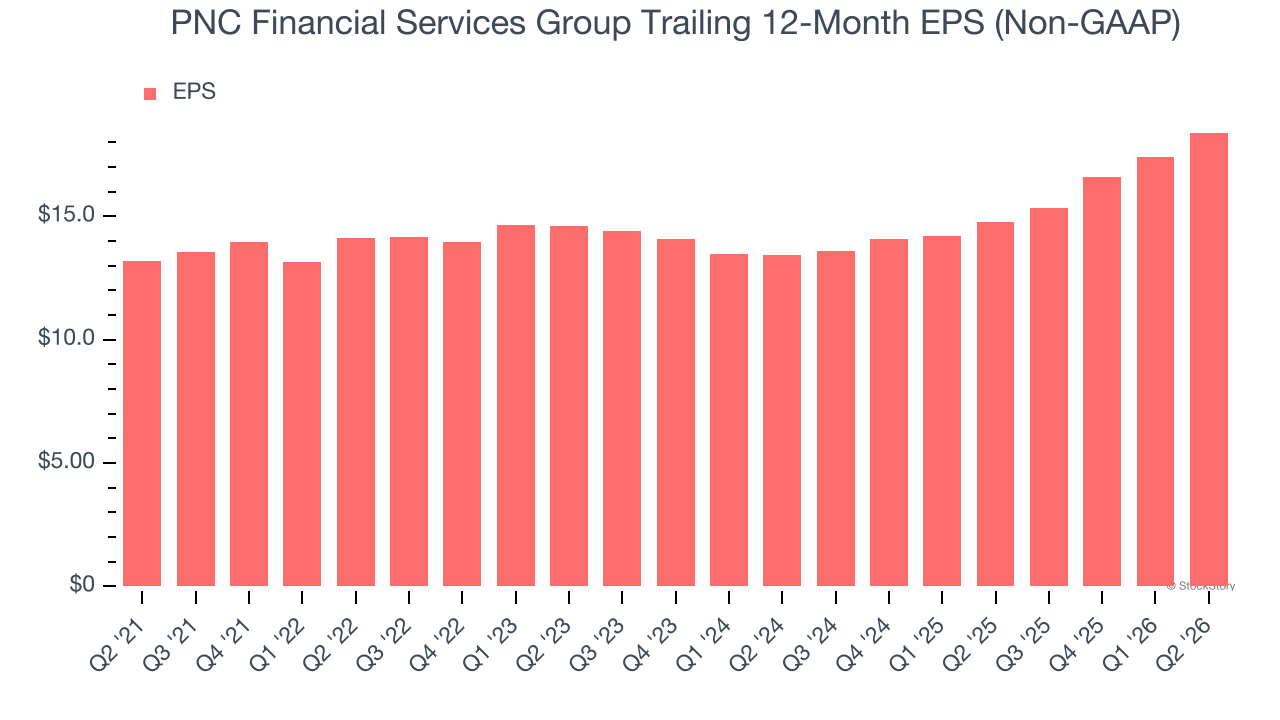
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
PNC Financial Services Group’s unimpressive 6.9% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
Final Judgment
PNC Financial Services Group isn’t a terrible business, but it doesn’t pass our quality test. With its shares topping the market in recent months, the stock trades at 1.6× forward P/B (or $243.93 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at the Amazon and PayPal of Latin America.
Stocks We Would Buy Instead of PNC Financial Services Group
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.