
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Enbridge (TSX:ENB) Could Be 17% Undervalued As Tallgrass Deal Tests Sentiment
Enbridge (TSX:ENB) has moved back into the spotlight after agreeing to acquire the crude oil operations of Tallgrass Energy and filing a follow-on equity offering of about CA$2.6b to help fund the deal.
Enbridge shares have slipped in the short term, with the 30 day share price return down 6.2% and the 90 day share price return down 15%, even as the 1 year total shareholder return sits at 3.4% and the 5 year total shareholder return is 82.59%. This points to long term momentum but fading recent sentiment as investors weigh the Tallgrass deal, the equity raise, and a planned CEO transition.
Scan how Enbridge compares with other income-focused infrastructure plays by reviewing our curated 2 dividend fortresses before deciding where fresh capital might work hardest.The recent pullback in Enbridge after the Tallgrass deal, equity raise, and leadership change could signal concern about execution or represent an emotional reset after a long run. Which explanation fits the current valuation better?
Most Popular Narrative: 17% Undervalued
Enbridge last closed at CA$66.23, while the most followed narrative pegs fair value at CA$80.14. That gap raises a simple question for investors who see Tallgrass, the equity raise, and the CEO transition all hitting at once: which story is the market really pricing in?
The strategic build-out responding to surging electricity and data center needs, including utility-scale renewables, gas transmission expansions, and power generation projects, underpins multi-year earnings and cash flow growth as power demand accelerates through the decade.
See why 272 investors see Enbridge as 17% undervalued.
Result: Fair Value of CA$80.14 (UNDERVALUED)
Still, the Enbridge narrative could be knocked off course if regulatory setbacks delay projects or if decarbonization policies reduce long term demand for its legacy pipelines.
Find out about the key risks to this Enbridge narrative.
Another View On Enbridge’s Valuation
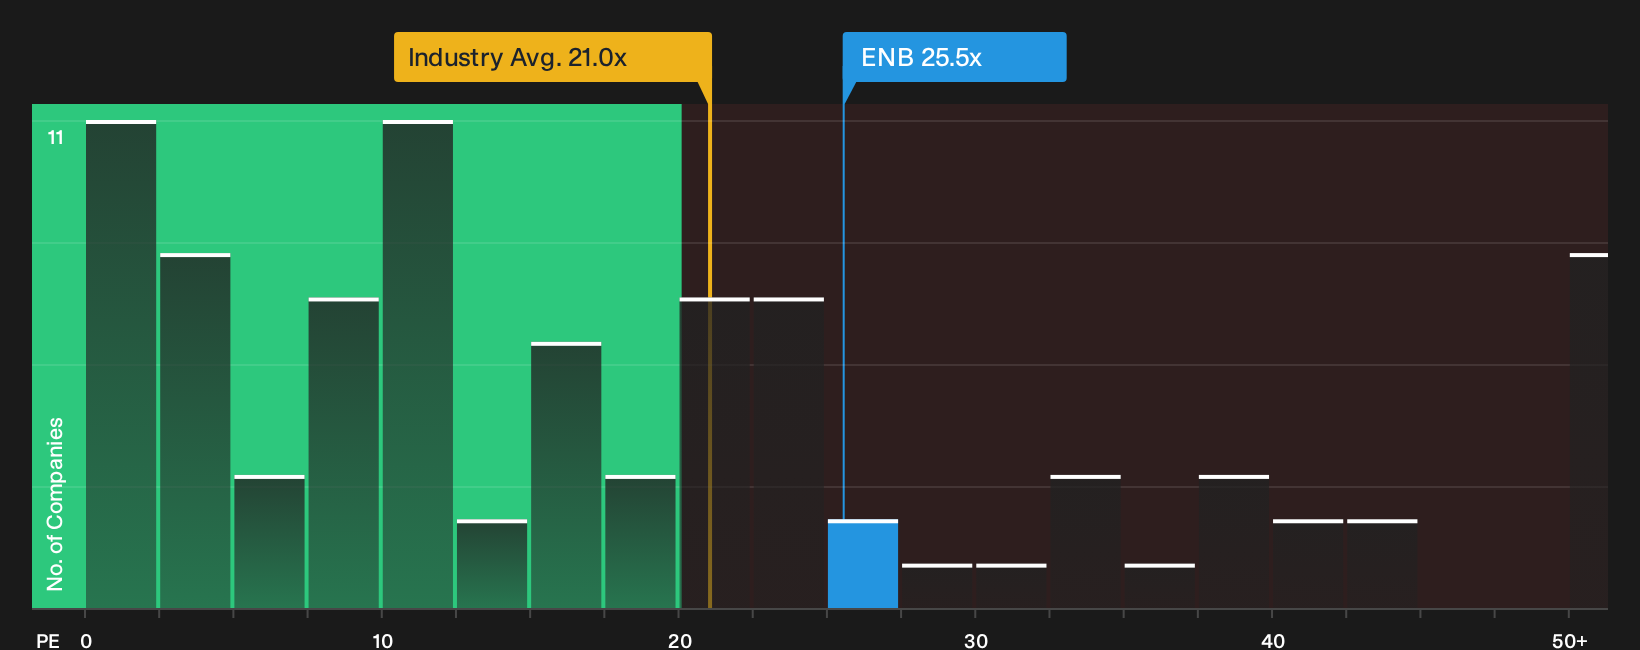
That CA$80.14 fair value hinges on detailed earnings forecasts and discounted cash flows. The market is telling a different story when you look at simple pricing. Enbridge trades on a P/E of 25.5x, while the Canadian Oil and Gas group averages 21x and the fair ratio sits at 25.1x.
This means Enbridge is priced above its sector and slightly above the fair ratio. This tilts the risk toward paying up for quality rather than buying a clear bargain. The question is whether you think Enbridge’s income profile and asset mix justify that premium or whether you prefer to wait for a better entry point.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether recent Enbridge headlines signal opportunity or risk and want to ground that instinct in hard numbers before moving on?
Move quickly, scan the evidence on both sides, then decide where you land after reviewing 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Enbridge?
If Enbridge has sharpened your focus on income, quality and risk, broaden the playbook and pressure test your next move across a wider field of opportunities.
- Target resilient compounding potential by reviewing our 5 high quality undervalued stocks and see which companies the data suggests may offer more value for every dollar you commit.
- Prioritise capital protection by scanning the 1 resilient stocks with low risk scores and focus on businesses that score well on stability and downside resilience.
- Hunt for tomorrow’s quiet overachievers with the 9 high quality undiscovered gems before other investors start paying serious attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com