
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does FDA Filing Acceptance Change The Bull Case For United Therapeutics Stock?
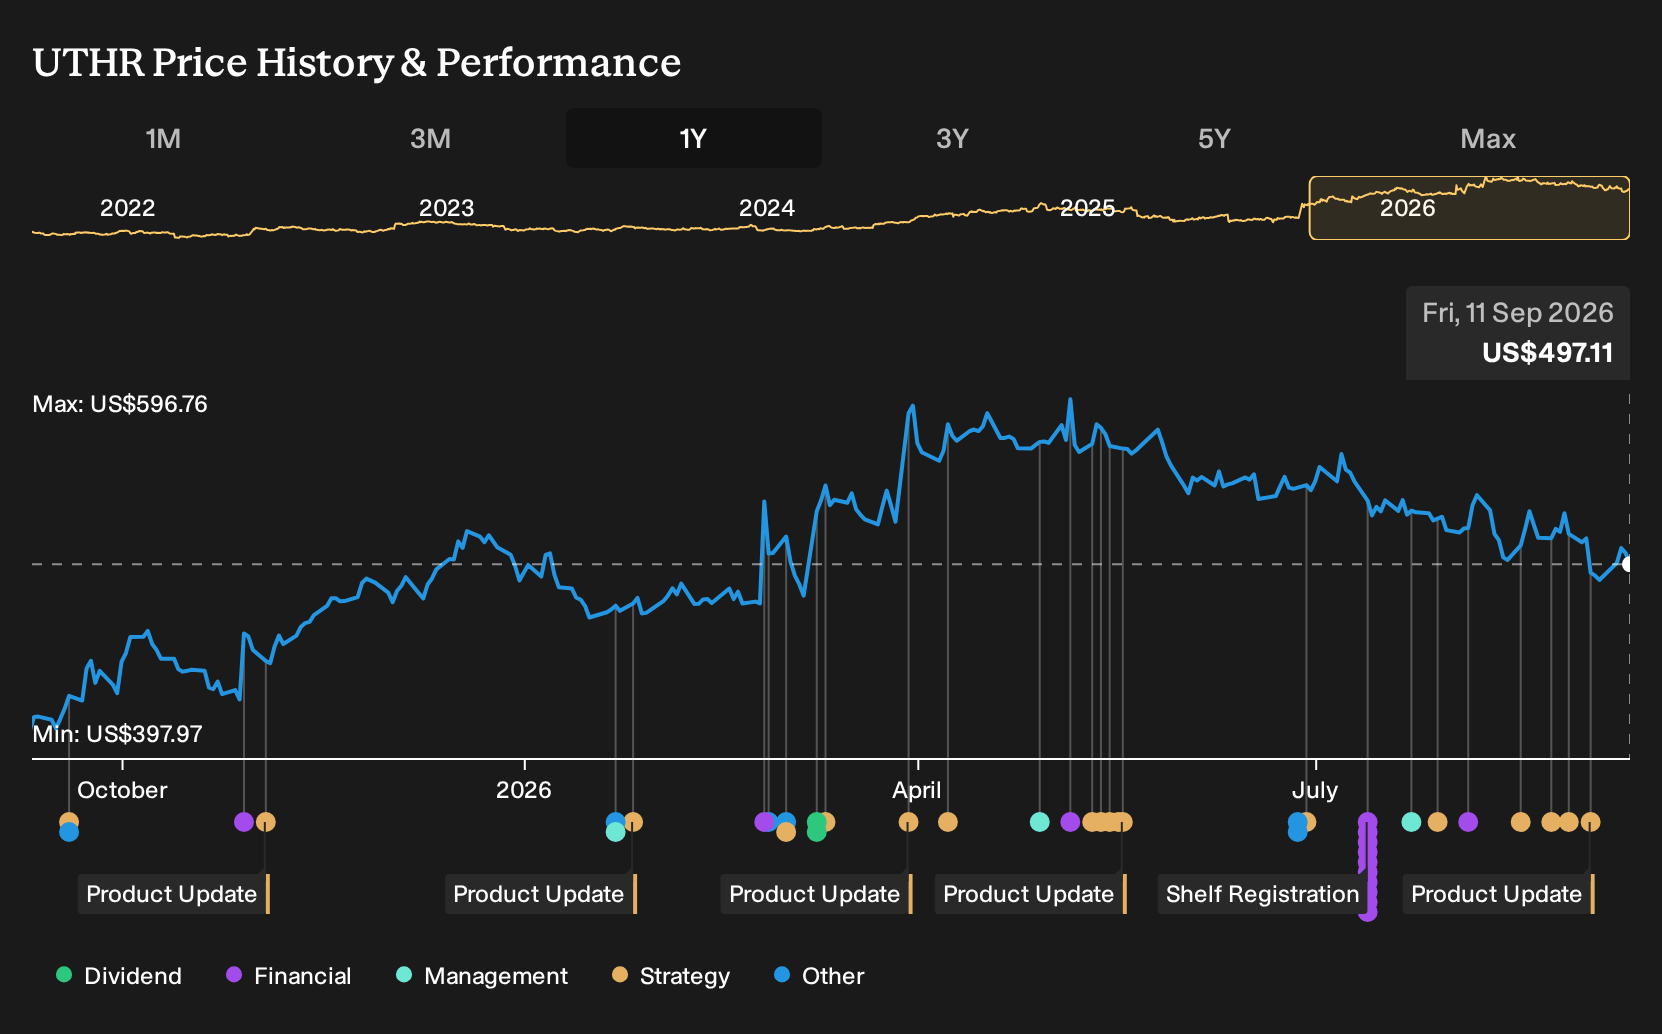
- United Therapeutics reported that in early September 2026 the FDA accepted its supplemental New Drug Application for nebulized Tyvaso in idiopathic pulmonary fibrosis, based on phase 3 TETON data that met the primary endpoint on forced vital capacity.
- This development pushes United Therapeutics deeper into fibrotic lung disease, potentially stretching the Tyvaso franchise into a new use case that could influence future R&D priorities, commercial resourcing, and manufacturing capacity planning.
- We will now look at how United Therapeutics' investment narrative could shift if nebulized Tyvaso expands into idiopathic pulmonary fibrosis.
United Therapeutics Investment Narrative Recap
To own United Therapeutics, you need to believe its pulmonary focus can keep generating strong cash flow while it pushes treprostinil into adjacent diseases. The FDA acceptance of the nebulized Tyvaso sNDA in idiopathic pulmonary fibrosis shifts a key binary event from data risk to regulatory timing, with late April 2027 now the next clear decision point.
In the near term, the biggest operational swing factor still sits in how resilient the Tyvaso franchise remains against branded and generic pressure, especially inhaled competitors. The main risk is that heavier pulmonary arterial hypertension and IPF investment lifts R&D and commercial spend without a corresponding future revenue contribution.
The sNDA acceptance for nebulized Tyvaso in IPF is the announcement that matters most here. It ties directly to earlier TETON phase 3 readouts that analysts had flagged as a pivotal catalyst for extending the Tyvaso life cycle beyond pulmonary arterial hypertension and PH ILD into a separate, serious fibrotic indication.
This step does not remove regulatory, safety, or commercial hurdles. It does give United Therapeutics a defined review clock and a concrete label expansion opportunity to discuss at upcoming investor conferences in September 2026. Execution now turns on manufacturing readiness, prescriber education in IPF, and how payers respond if approval arrives on the expected timeline.
United Therapeutics' consensus story points to US$4.5b in revenue and US$1.8b in earnings by 2029, based on analysts modeling 12.3% yearly top line growth and an earnings increase of about US$500m from US$1.3b today.
Discover how United Therapeutics' fair value points to a 34% potential upside compared with its current price before the market closes that gap.
Exploring Other Perspectives
For United Therapeutics, the bearish twist centers on reliance risk rather than new IPF upside. The lowest analysts were modeling flat earnings of about US$1.3b on only US$3.1b of 2029 revenue before this FDA sNDA news. That is a much more cautious stance. Use this moment to compare those expectations with several alternative views.
Explore 2 other United Therapeutics fair value estimates, including one that suggests it could be worth just $664.33!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your United Therapeutics research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for United Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Therapeutics?
Once you have a view on United Therapeutics, it can help to put that thesis in context by reviewing a few other stocks with very different risk and income profiles using the Simply Wall St Screener.
- If you are hunting for potential mispricings with strong fundamentals behind them, line up your next watchlist candidates using our 32 high quality undervalued stocks.
- For readers who want income visibility alongside capital preservation, focus on companies in our 6 dividend fortresses that pair higher yields with resilient cash generation.
- When capital protection sits at the top of your priorities, filter for companies that screen well on stability and financial strength through our 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com