
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Exploring Undiscovered Gems in the US Market September 2026
In the last week, the United States market has been flat, yet it has shown a robust 14% increase over the past year with earnings forecasted to grow by 17% annually. In this dynamic environment, identifying stocks that are underappreciated but have strong growth potential can be key to uncovering valuable opportunities.
Top 10 Undiscovered Gems With Strong Fundamentals In The United States
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Insteel Industries | NA | -1.98% | -26.25% | ★★★★★★ |
| Imperial Petroleum | NA | 29.81% | 34.96% | ★★★★★★ |
| OptimumBank Holdings | 29.02% | 36.10% | 35.25% | ★★★★★★ |
| Perma-Pipe International Holdings | 31.47% | 11.47% | 32.99% | ★★★★★★ |
| TOYO | 36.72% | 208.58% | 54.90% | ★★★★★☆ |
| Meridian | 77.88% | -7.73% | -15.61% | ★★★★☆☆ |
| Kingstone Companies | 2.94% | 9.01% | 64.05% | ★★★★☆☆ |
| Deluxe | 191.02% | 0.87% | 5.66% | ★★★☆☆☆ |
| F&G Annuities & Life | 48.57% | 13.75% | -26.95% | ★★★☆☆☆ |
| GDEV | NA | -1.59% | 54.97% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
Imperial Petroleum (IMPP)
Simply Wall St Value Rating: ★★★★★★
Overview: Imperial Petroleum Inc., along with its subsidiaries, offers seaborne transportation services globally and has a market capitalization of $261.79 million.
Operations: Imperial Petroleum generates revenue primarily from its transportation-shipping segment, amounting to $190.63 million.
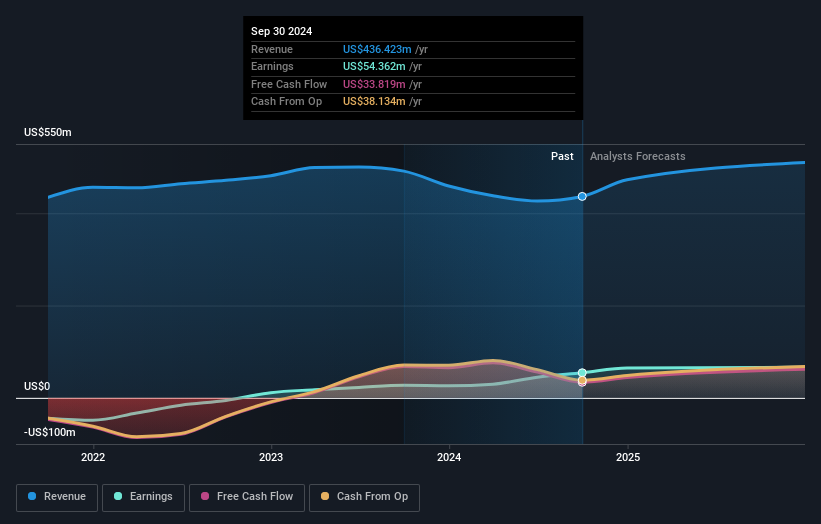
Imperial Petroleum, a nimble player in the oil and gas sector, has shown impressive growth with earnings soaring by 54% over the past year. The company operates without debt, allowing it to focus on strategic fleet expansion into drybulk carriers alongside tankers. Trading at 82% below its estimated fair value, Imperial seems like a bargain compared to industry peers. However, shareholders experienced substantial dilution recently and revenue declines pose challenges. Despite this, forecasts suggest annual earnings growth of nearly 23%, driven by strong demand for energy transport and an expected price target of US$9 per share highlights potential upside.
Power Solutions International (PSIX)
Simply Wall St Value Rating: ★★★★★★
Overview: Power Solutions International, Inc. designs, engineers, manufactures, markets, and sells engines and power systems across various regions including the United States and internationally, with a market cap of $971.29 million.
Operations: PSIX generates revenue primarily from its Engineered Integrated Electrical Power Generation Systems, amounting to $676.19 million. The company's market cap is approximately $971.29 million.
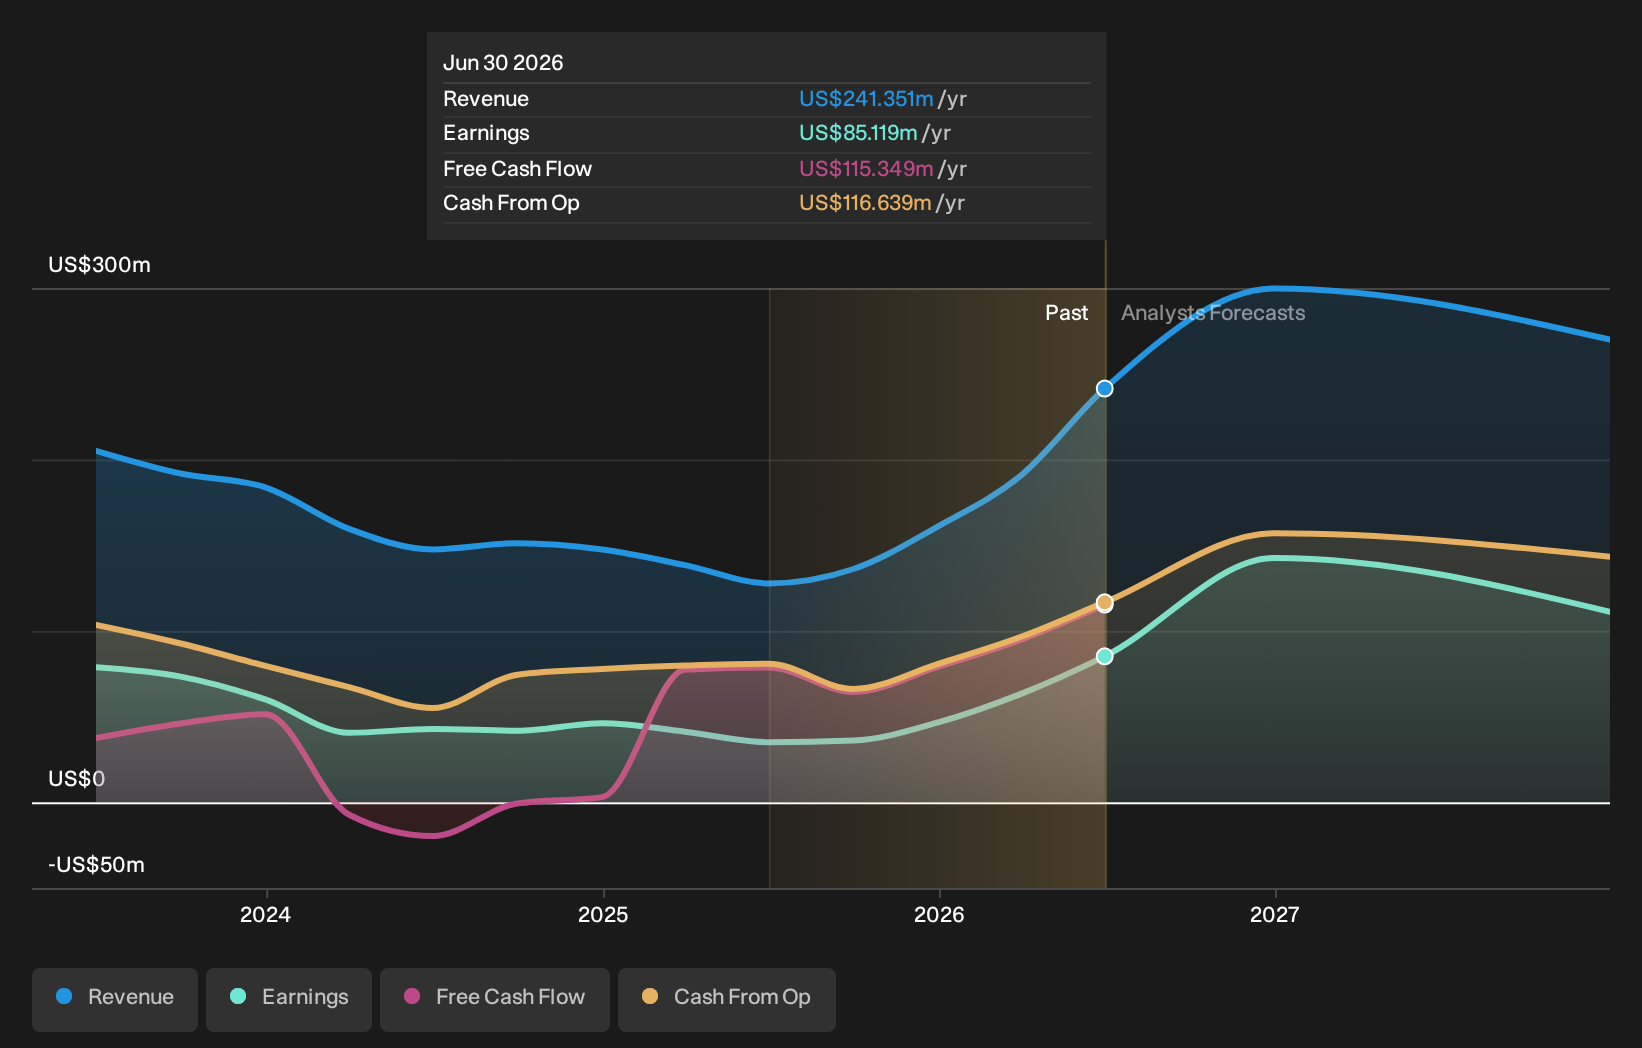
Power Solutions International, a dynamic player in the energy sector, has shown resilience despite recent challenges. The company reported Q2 2026 sales at US$152.54 million, a dip from US$191.91 million the previous year, while net income reached US$16.86 million compared to last year's US$51.21 million. Despite this, their debt situation has improved with positive shareholder equity after five years of negative figures and an impressive interest coverage ratio of 13x EBIT over interest payments. With new leadership under CEO Richard Hu and projected earnings growth of 26% annually, PSIX seems poised for potential recovery and expansion in its market niche.
- Click to explore a detailed breakdown of our findings in Power Solutions International's health report.
Understand Power Solutions International's track record by examining our Past report.
Perma-Pipe International Holdings (PPIH)
Simply Wall St Value Rating: ★★★★★★
Overview: Perma-Pipe International Holdings, Inc. is a company that designs, engineers, manufactures, and sells specialty piping and leak detection systems across various international markets including the United States, Canada, the United Arab Emirates, and Saudi Arabia with a market cap of approximately $253.31 million.
Operations: PPIH generates its revenue primarily from the sale of piping systems, amounting to $226.11 million. The company's financial performance can be evaluated through its gross profit margin, which reflects the efficiency in managing production costs relative to sales revenue.
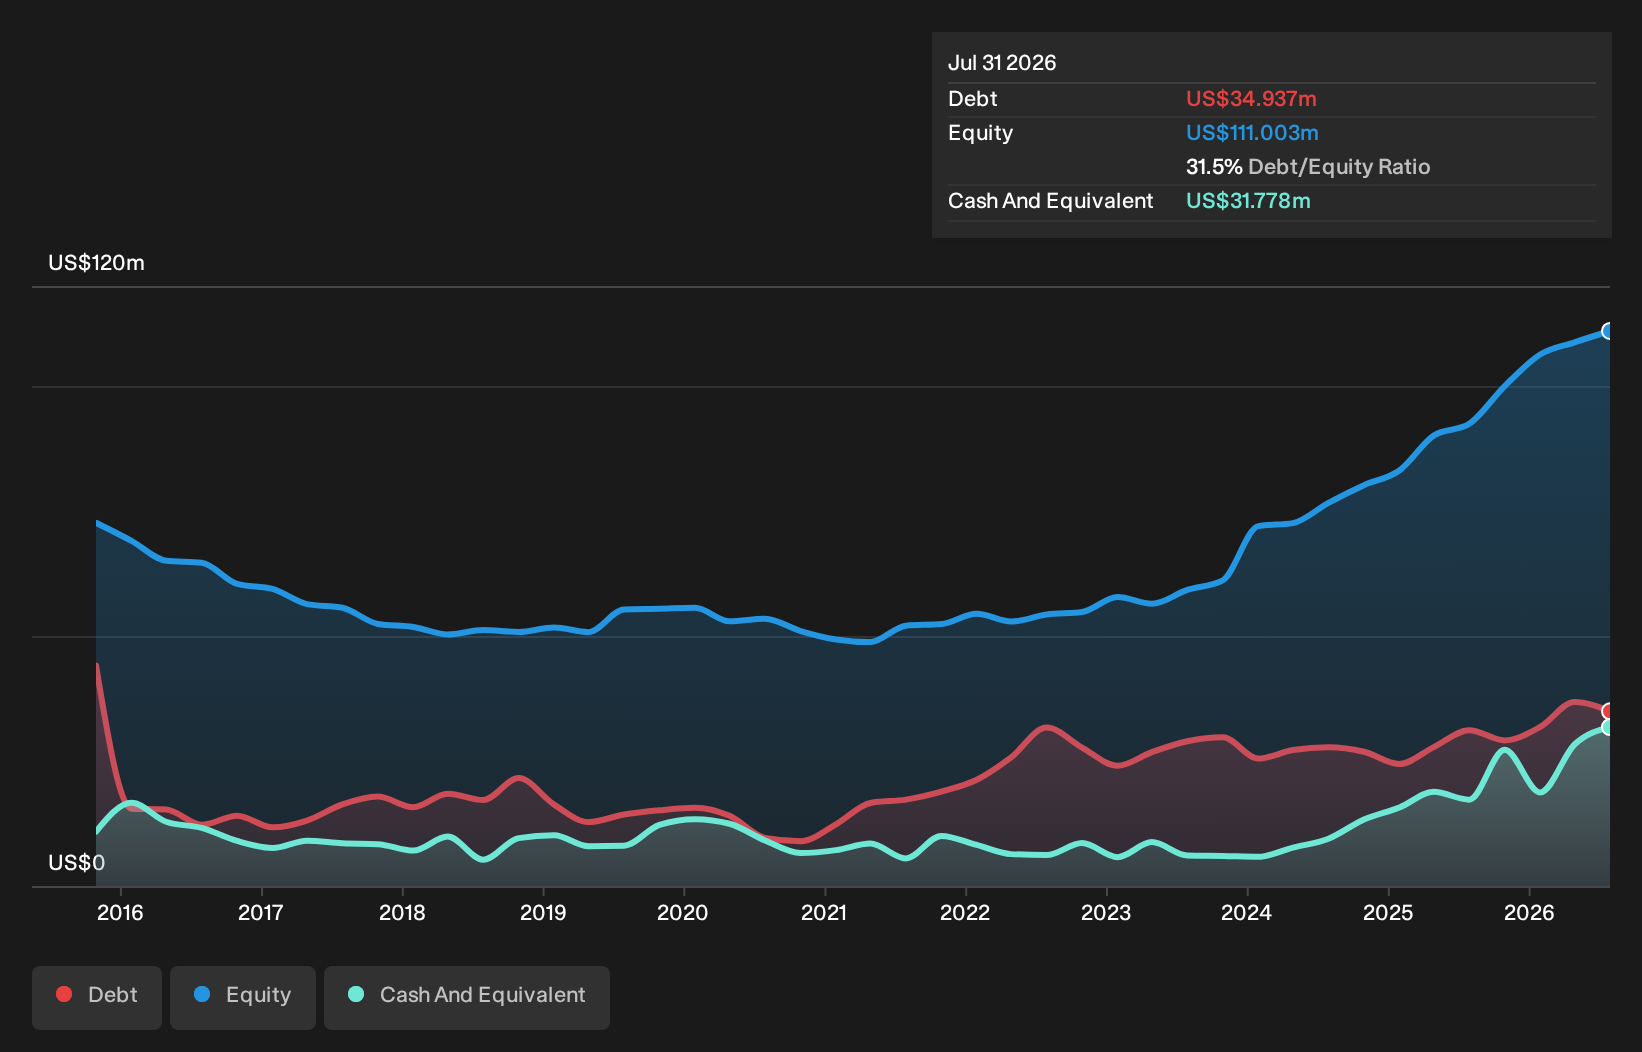
Perma-Pipe International Holdings, a company with a knack for strategic growth, recently reported impressive financial results. Sales for the second quarter reached US$59.57 million, up from US$47.9 million the previous year, while net income jumped to US$2.55 million from US$0.851 million. Earnings per share also saw an increase to US$0.31 from last year's US$0.11 for continuing operations. The company's debt-to-equity ratio has been trimmed down to 31.5% over five years and its net debt-to-equity ratio stands at a satisfactory 2.8%. With earnings growing by 55% in the past year and trading at 59% below estimated fair value, Perma-Pipe seems well-poised in its industry landscape, further bolstered by new credit facilities enhancing liquidity and flexibility for future ventures like its joint venture in Jordan's infrastructure projects.
Seize The Opportunity
- Unlock more gems! Our US Undiscovered Gems With Strong Fundamentals screener has unearthed 16 more companies for you to explore.Click here to unveil our expertly curated list of 19 US Undiscovered Gems With Strong Fundamentals.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com