
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Have Bank First Insiders Been Selling Stock?
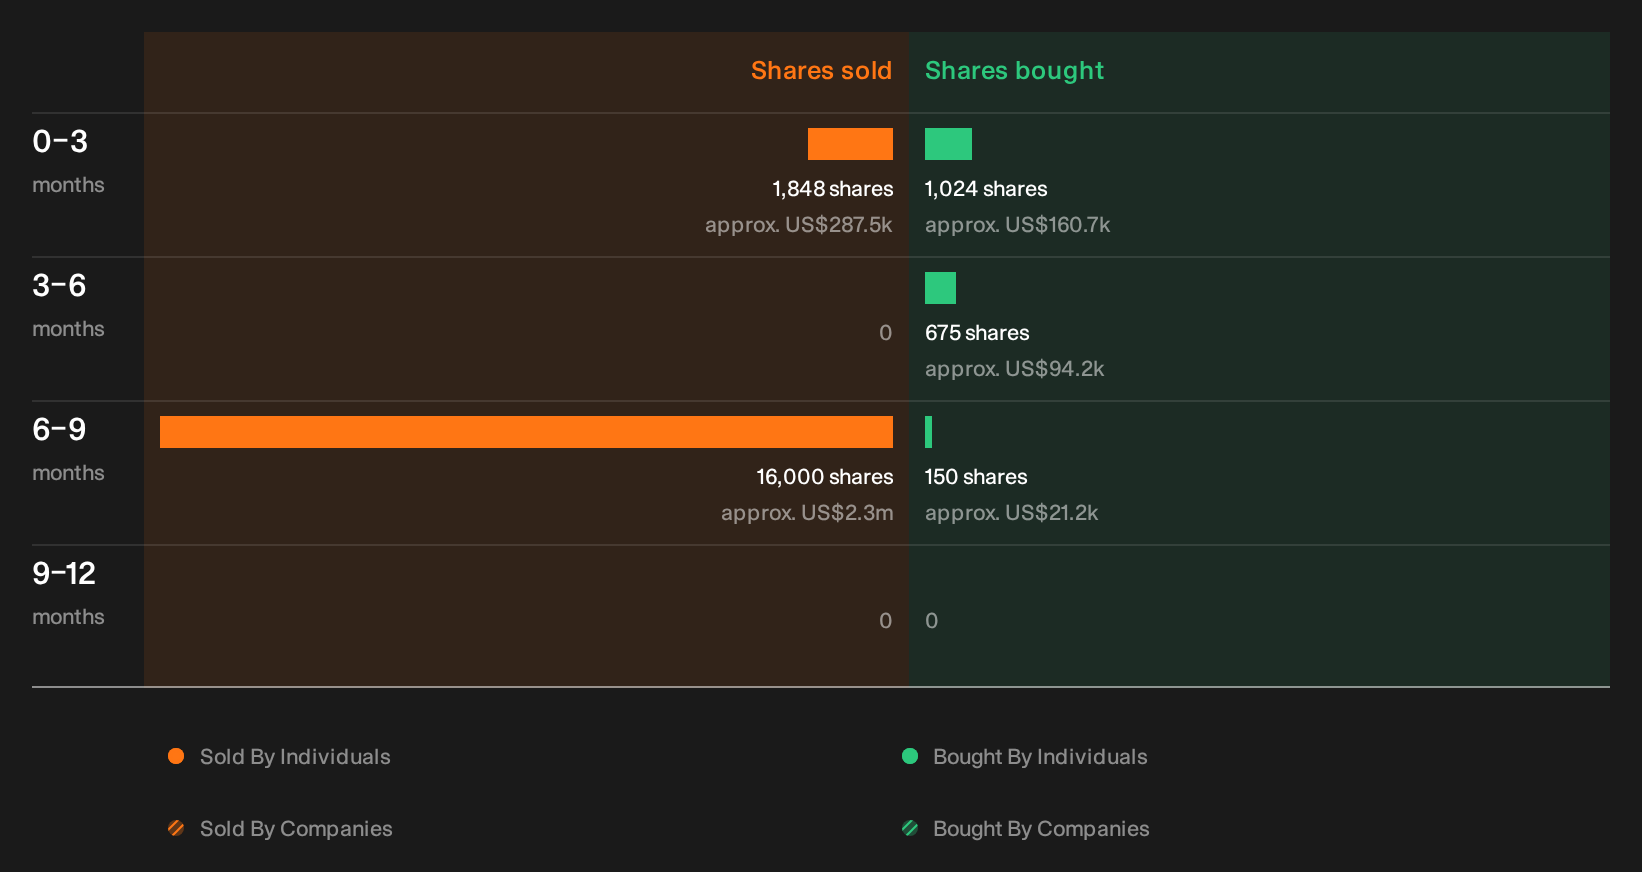
We'd be surprised if Bank First Corporation (NASDAQ:BFC) shareholders haven't noticed that the Independent Director, Peter Van Sistine, recently sold US$287k worth of stock at US$156 per share. The eyebrow raising move amounted to a reduction of 19% in their holding.
Bank First Insider Transactions Over The Last Year
The Director, Steven Eldred, made the biggest insider sale in the last 12 months. That single transaction was for US$2.4m worth of shares at a price of US$152 each. That means that even when the share price was slightly below the current price of US$154, an insider wanted to cash in some shares. When an insider sells below the current price, it suggests that they considered that lower price to be fair. That makes us wonder what they think of the (higher) recent valuation. While insider selling is not a positive sign, we can't be sure if it does mean insiders think the shares are fully valued, so it's only a weak sign. It is worth noting that this sale was only 8.1% of Steven Eldred's holding.
Happily, we note that in the last year insiders paid US$276k for 1.85k shares. But insiders sold 17.85k shares worth US$2.7m. In total, Bank First insiders sold more than they bought over the last year. You can see a visual depiction of insider transactions (by companies and individuals) over the last 12 months, below. By clicking on the graph below, you can see the precise details of each insider transaction!
Check out our latest analysis for Bank First
If you are like me, then you will not want to miss this free list of small cap stocks that are not only being bought by insiders but also have attractive valuations.
Insider Ownership Of Bank First
Looking at the total insider shareholdings in a company can help to inform your view of whether they are well aligned with common shareholders. Usually, the higher the insider ownership, the more likely it is that insiders will be incentivised to build the company for the long term. It's great to see that Bank First insiders own 10% of the company, worth about US$178m. I like to see this level of insider ownership, because it increases the chances that management are thinking about the best interests of shareholders.
So What Does This Data Suggest About Bank First Insiders?
Unfortunately, there has been more insider selling of Bank First stock, than buying, in the last three months. And our longer term analysis of insider transactions didn't bring confidence, either. But since Bank First is profitable and growing, we're not too worried by this. While insiders do own a lot of shares in the company (which is good), our analysis of their transactions doesn't make us feel confident about the company. So these insider transactions can help us build a thesis about the stock, but it's also worthwhile knowing the risks facing this company. In terms of investment risks, we've identified 1 warning sign with Bank First and understanding it should be part of your investment process.
But note: Bank First may not be the best stock to buy. So take a peek at this free list of interesting companies with high ROE and low debt.
For the purposes of this article, insiders are those individuals who report their transactions to the relevant regulatory body. We currently account for open market transactions and private dispositions of direct interests only, but not derivative transactions or indirect interests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.