
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Going On With Apollo Global Management (APO)?
Apollo Global Management (APO) is back in focus as investors weigh rising interest rate risk, stalled private credit shares, and the firm’s move to limit redemptions in a key private credit fund.
Recent price action has been softer, with Apollo Global Management’s share price down 8.37% over the past 30 days and 12.03% year to date. However, the 5 year total shareholder return of 143.18% indicates that longer term holders have still seen substantial gains, even though momentum has faded recently.
Scan how Apollo Global Management compares with other financials facing the same rate pressure by reviewing our hand picked 11 resilient stocks with low risk scores list.Apollo Global Management now trades at a double discount, both to analyst targets and to an intrinsic value estimate, after a choppy stretch for private credit. Is that caution signaling deeper risk, or is it mispricing the stock’s underlying earnings power?
Preferred P/E of 40.3x for Apollo Global Management: Is it justified?
Valuation on Apollo Global Management is caught between two signals. The stock trades at a premium P/E of 40.3x compared to the US Diversified Financial industry average of 17.6x, yet it also trades at a discount to both analyst targets and an internal estimate of fair value based on future cash flows.
The P/E multiple measures how much investors are currently willing to pay for each dollar of earnings. For a diversified alternative asset manager like Apollo Global Management, that ratio often reflects expectations for fee growth, performance income, and the durability of its retirement services earnings more than near term reported profit swings.
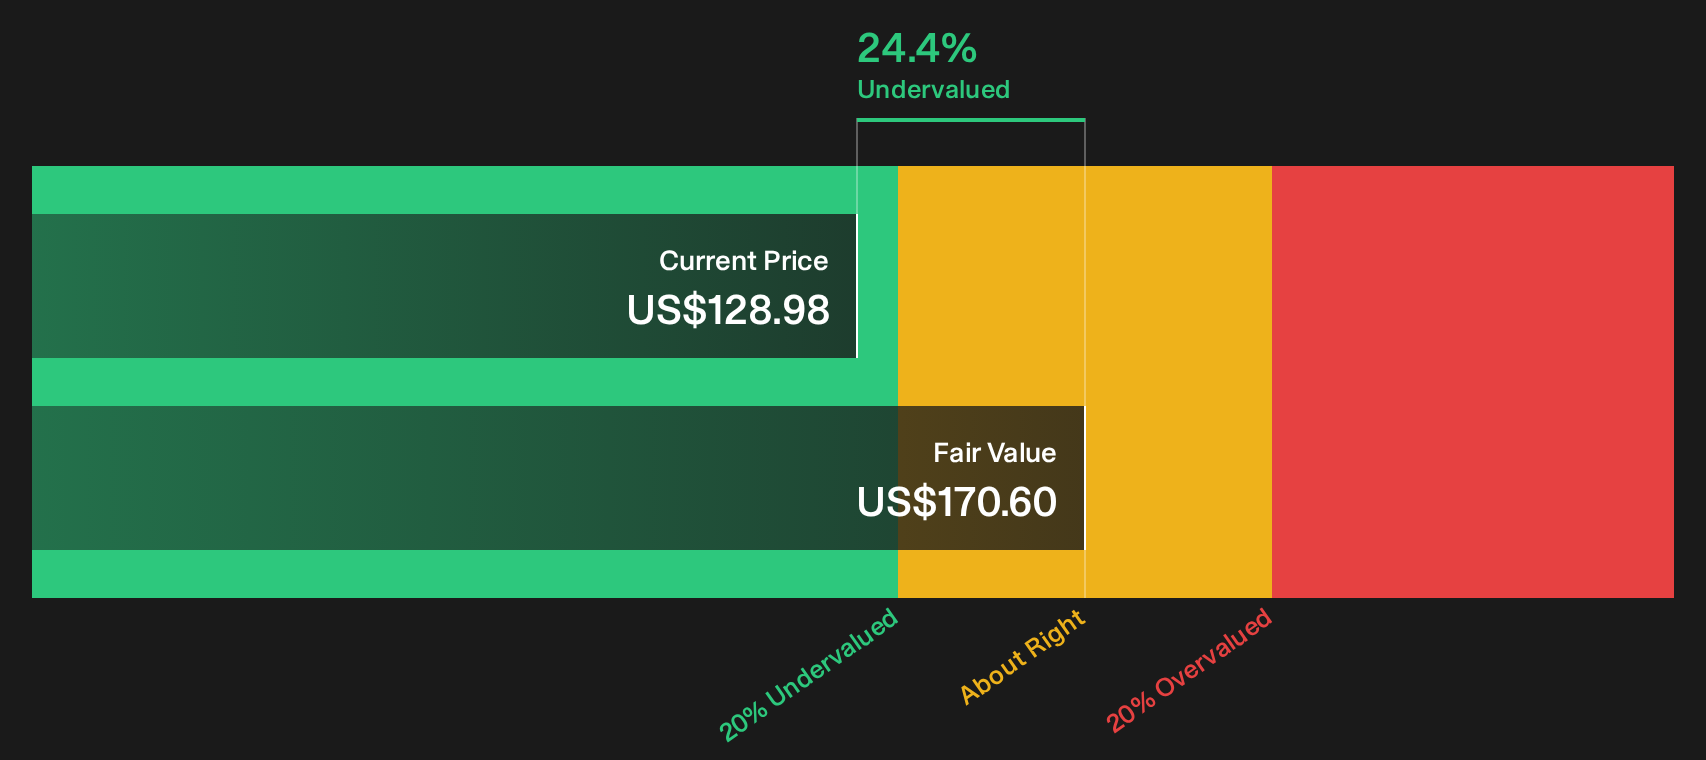
On simple comparison, a 40.3x P/E looks expensive relative to the industry average of 17.6x. The gap to an estimated fair P/E of 26.9x reinforces that the current multiple is high compared to the level the market could reasonably move toward if sentiment cools or earnings forecasts are recalibrated. At the same time, the share price at $128.98 is 24.4% below an internal fair value estimate of $170.60 based on the SWS DCF model, which projects future cash flows and discounts them back to today, so earnings expectations and cash flow assumptions are telling different stories about valuation.
Explore the SWS fair ratio for Apollo Global Management.
Result: Price-to-earnings of 40.3x (OVERVALUED)
Still, Apollo Global Management faces clear pressure points if higher rates keep private credit volumes muted and if redemption limits unsettle clients in its retirement and credit platforms.
Find out about the key risks to this Apollo Global Management narrative.
Another View on Apollo Global Management’s Valuation
The SWS DCF model presents a different view of Apollo Global Management. On this analysis, the stock at $128.98 screens as undervalued relative to an estimated fair value of $170.60. That gap suggests investors are pricing earnings more cautiously than the long term cash flow profile implies.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Apollo Global Management for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Apollo Global Management’s valuation and risk will not settle themselves. Review the data, pressure test the key drivers, and then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Apollo Global Management?
If Apollo Global Management has sharpened your thinking on valuation and risk, do not stop here. Broaden your watchlist with fresh ideas that match your goals.
- Target potential bargains with solid fundamentals by scanning our 32 high quality undervalued stocks to see which businesses the numbers suggest may be priced below their worth.
- Build a steadier income stream by reviewing a curated set of high yield payers through the 6 dividend fortresses before the next round of payouts is locked in.
- Strengthen your downside protection by focusing on robust financial footing using the list of solid balance sheet and fundamentals (23 results) while others overlook balance sheet quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com