
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bank of New York Mellon (BNY) Stock Could Be 11% Above Fair Value On Excess Returns
Bank of New York Mellon Corporation has delivered a powerful run over the past few years, which naturally puts the focus on what investors are really paying for. With BNY, the live issue is whether that higher price tag lines up with the returns it earns on its capital.
- BNY has returned roughly 290.6% over the past 3 years, so the question now is how fully those past gains already reflect the returns the business can generate on the capital it deploys.
- The company’s role as a large custodian and asset servicer can support a business model that often leans heavily on efficient use of balance sheet capital and fee based activities, which directly shapes how much value it can create from each dollar it invests back into operations.
- Prefer to judge Bank of New York Mellon on earnings? See what Bank of New York Mellon's 18.3x P/E says about the price.
The stock’s next move may depend on whether BNY’s current share price is justified by the returns it earns on its capital today and can reasonably sustain.
If you want to test the same question about returns on capital across a wider field, compare Bank of New York Mellon Corporation with the companies in the 11 resilient stocks with low risk scores.
Does Bank of New York Mellon Look Pricey on Excess Returns?
The Excess Returns model looks at what Bank of New York Mellon Corporation earns above its estimated cost of equity and then capitalises those extra profits. It compares those implied economics with what you are being asked to pay at the current share price of $162.66.
In this framework, BNY is assumed to generate stable earnings of $10.66 per share on a stable book value of $66.22 per share, with an average return on equity of 16.10%. The model treats the cost of equity as $6.16 per share, leaving an excess return of $4.50 per share. In this context, the emphasis is less on rapid expansion and more on how consistently the bank can recycle capital at a premium over that hurdle rate.
The Excess Returns projections put Bank of New York Mellon's estimated intrinsic value modestly below the current share price, which suggests the market is already pricing in a fair amount of that surplus profitability. You are essentially paying for a mature financial institution that the model assumes will continue to earn returns on equity comfortably above its required rate of return. Find out what Bank of New York Mellon could be worth using our Excess Returns estimate.
The Bank of New York Mellon Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Bank of New York Mellon Corporation pick up where the valuation puzzle leaves off and map out what growth, margin and earnings paths would need to unfold for the shares to look meaningfully cheaper or richer than today. They sit on the Community page and, instead of giving a single output from a model, they spell out the future that output leans on so you can watch in real time whether the story is still tracking.
One of the top community narratives on Bank of New York Mellon: roughly fairly valued
"Expanding digital capabilities and leadership in digital assets are driving improved margins, efficiency, and new revenue opportunities through advanced technology and innovative offerings..."
Discover why this Narrative puts Bank of New York Mellon at roughly fairly valued.
One more open question for Bank of New York Mellon Corporation
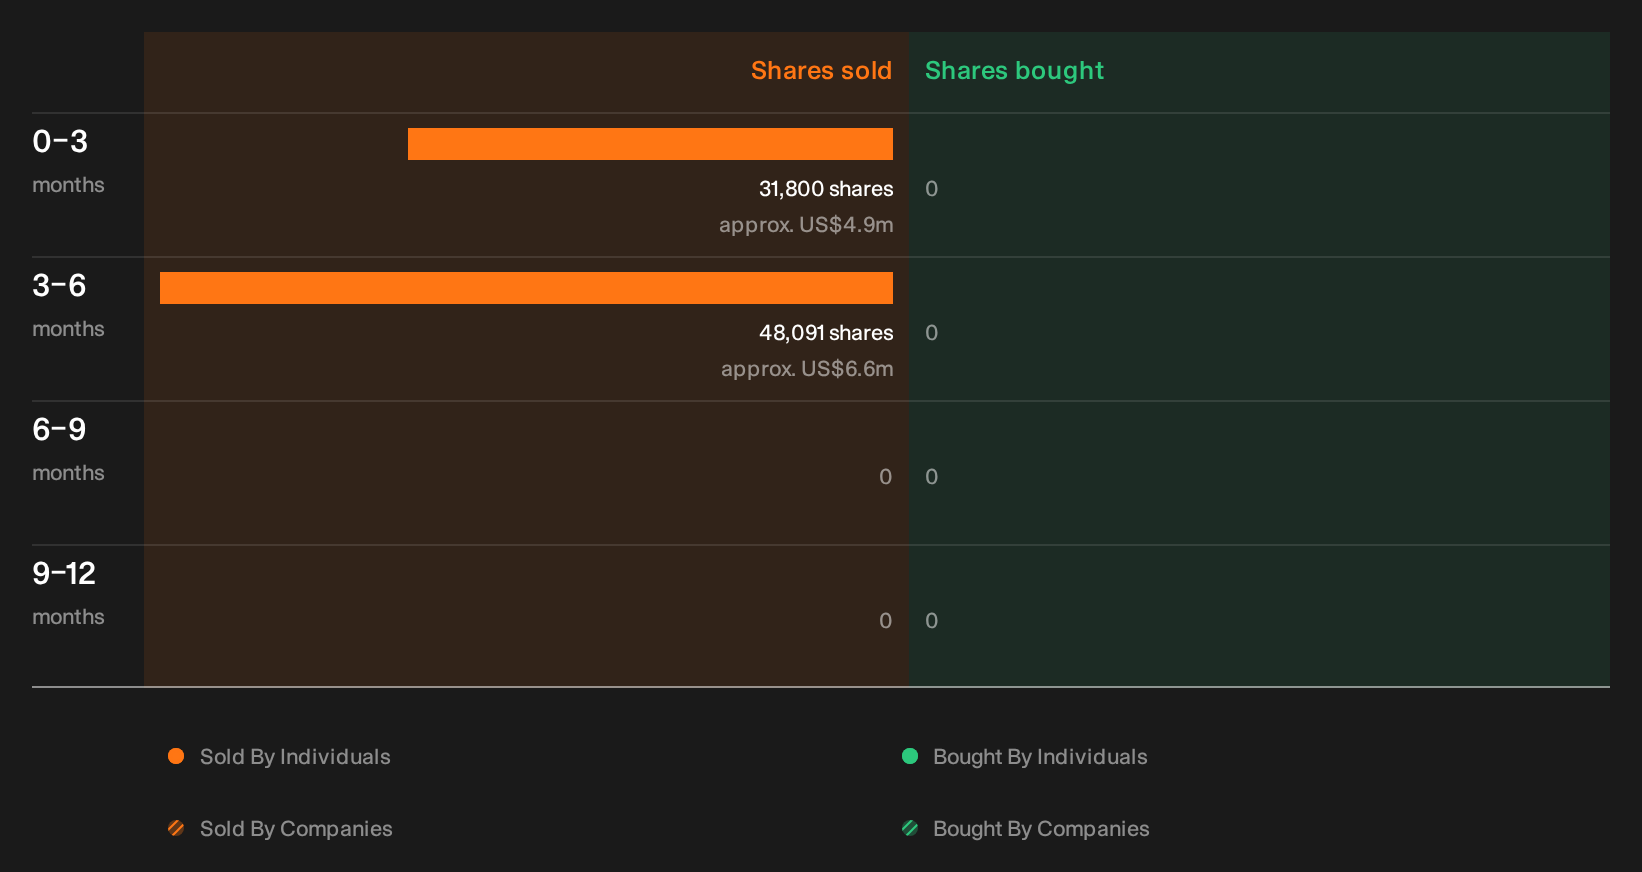
Valuation tells only part of the story for Bank of New York Mellon Corporation, because recent trading by people inside the business can raise fresh questions about incentives, timing and conviction that investors often want to inspect closely. See the recent insider selling flagged for Bank of New York Mellon.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com