
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Certara (CERT) Software Growth Meets Restructuring Costs, Is The Stock Still A Bargain?
Certara (CERT) moved back into focus after reporting second quarter 2026 results that combined higher software revenue and bookings with a net loss tied to restructuring and a fresh US$50 million share repurchase authorization.
Certara shares closed at US$7.55. The 90 day share price return of 24.8% contrasts with a year to date share price decline of 13.6%, while the 1 year total shareholder return has fallen 32.7%. This hints at improving short term momentum against a weaker longer term record as investors reassess the impact of restructuring and buybacks on risk and potential growth.
Compare Certara's restructuring story with other healthcare and life science specialists under quiet accumulation by screening for 15 high quality undiscovered gems that share strong fundamentals but mixed recent share price performance.
Certara has started to recover on restructuring hopes and buybacks, yet the share price still reflects a long slide. Is the recent rebound the main course or just the starter before any valuation upside?
Most Popular Narrative: 8% Undervalued
Certara last closed at $7.55, while the most followed narrative pegs fair value at $8.19. This puts the current rebound against a modest valuation gap and a long earnings recovery story.
The upcoming commercial launch of Certara's next-generation, AI-enabled MIDD platform and CertaraIQ QSP software leverages advanced analytics and machine learning, providing differentiated capabilities that democratize access and increase the potential customer base, which should translate to higher recurring revenue and margin expansion through cloud-based SaaS models.
See why 7 investors see Certara as 8% undervalued.
Result: Fair Value of $8.19 (UNDERVALUED)
Still, Certara’s reliance on large pharma clients, along with rising investment in AI and acquisitions, could pressure earnings if adoption slows or key customers delay spending.
Find out about the key risks to this Certara narrative.
Another View: Certara On Sales-Based Valuation
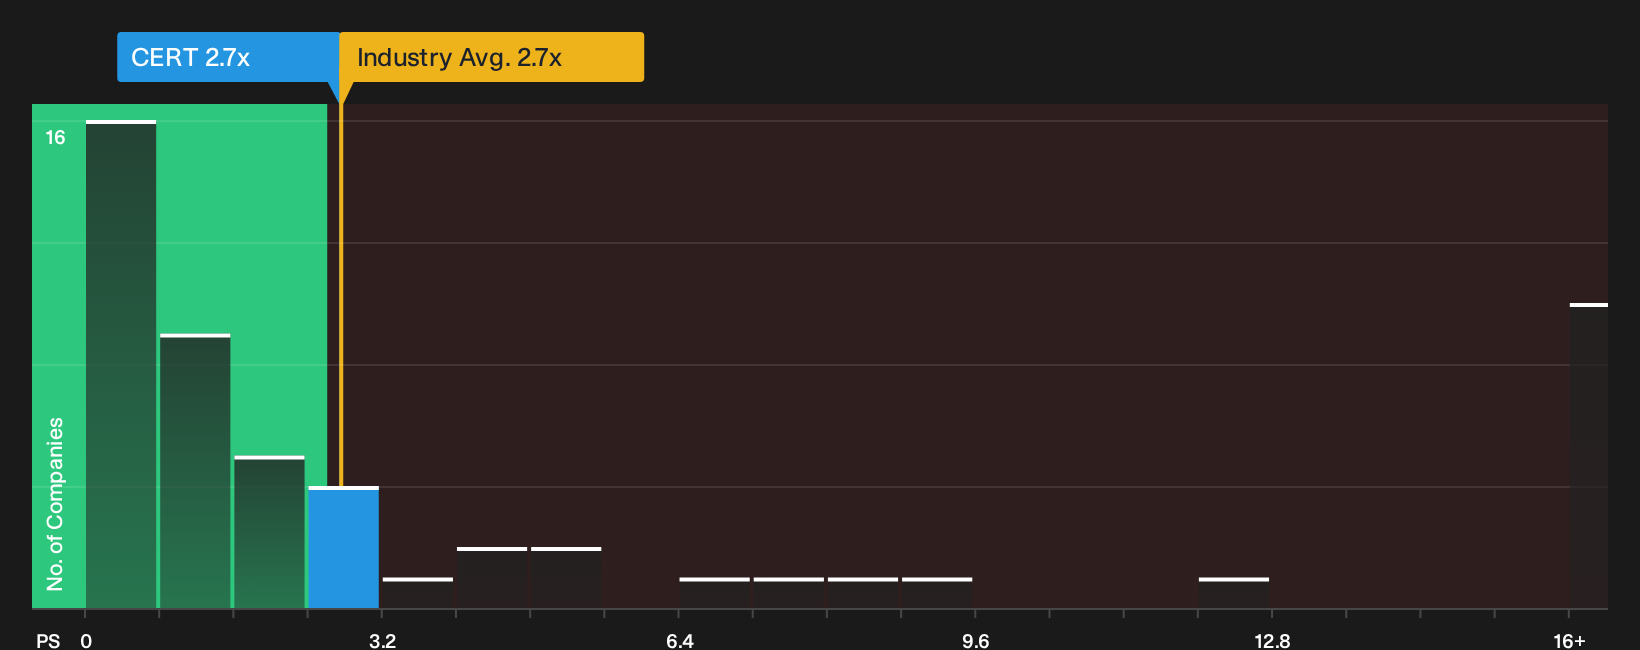
The initial perspective presents Certara as undervalued relative to a fair value of $8.19, yet its P/S ratio suggests a more cautious interpretation. The stock trades at 2.7x sales, while the fair ratio model indicates closer to 1.5x and peer averages sit around 2.5x. That additional premium can suggest less of a clear bargain and more of an ongoing pricing debate. How much are you willing to pay upfront for gradual growth and a still-loss-making profile?
To understand what this may imply in practice for potential upside and downside risk, it is useful to see how the current multiple compares across peers and against the fair ratio target in one place, which you can do through See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Certara is split, which is exactly when data can help you move fast and build your own conviction. To see what the current optimism is tied to, start with the 2 key rewards
Looking for more Certara style investment ideas?
Do not stop your research with Certara. Broaden your watchlist using focused screeners that surface stocks with different risk and return trade offs in seconds.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that keeps financially robust businesses on your radar before the crowd catches on.
- Hunt for mispriced opportunities through the 32 high quality undervalued stocks and see which companies currently trade below their assessed fair value on key fundamentals.
- Dial down portfolio risk by filtering a 11 resilient stocks with low risk scores that highlights stocks with steadier profiles when you want fewer surprises.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com