
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Diamondback Energy (FANG) On Efficiency Gains And Strong Returns Still Looks Undervalued
Diamondback Energy (FANG) continues to draw attention after recent trading, with the share price at $204.97 as of the latest close. Investors are weighing long term returns, profitability, and current valuation signals.
The recent share price slip of 0.20% over the last day sits against a much stronger backdrop. Diamondback Energy has posted a 34.55% year-to-date share price return and a 56.03% total shareholder return over one year, suggesting momentum has been building rather than fading.
Scan beyond Diamondback Energy and compare its recent momentum with a curated set of energy producers using our 32 high quality undervalued stocks to see how pricing and quality stack up.
Diamondback Energy has the share price strength and a large, profitable Permian operation to back it up. The question now is whether that kind of business quality is already fully reflected in the current valuation.
Most Popular Narrative: 11.7% Undervalued
Against the last close at $204.97, the most followed narrative for Diamondback Energy points to a fair value of about $232 per share. This frames today’s rally inside a still supportive valuation gap built on future cash generation and capital returns.
Consistent operational efficiency improvements (record drilling times, workover programs, optimization of older wells, and improved gas capture) point to sustainable cost reductions and productivity enhancements. This supports resilient net margins and robust free cash flow even in a volatile oil price environment.
See why 74 investors see Diamondback Energy as 12% undervalued.
Result: Fair Value of $232.17 (UNDERVALUED)
Still, two pressure points could challenge the Diamondback Energy story in a hurry: rising Permian operating costs and any prolonged period of weaker oil prices.
Find out about the key risks to this Diamondback Energy narrative.
Another View on Diamondback Energy’s Valuation
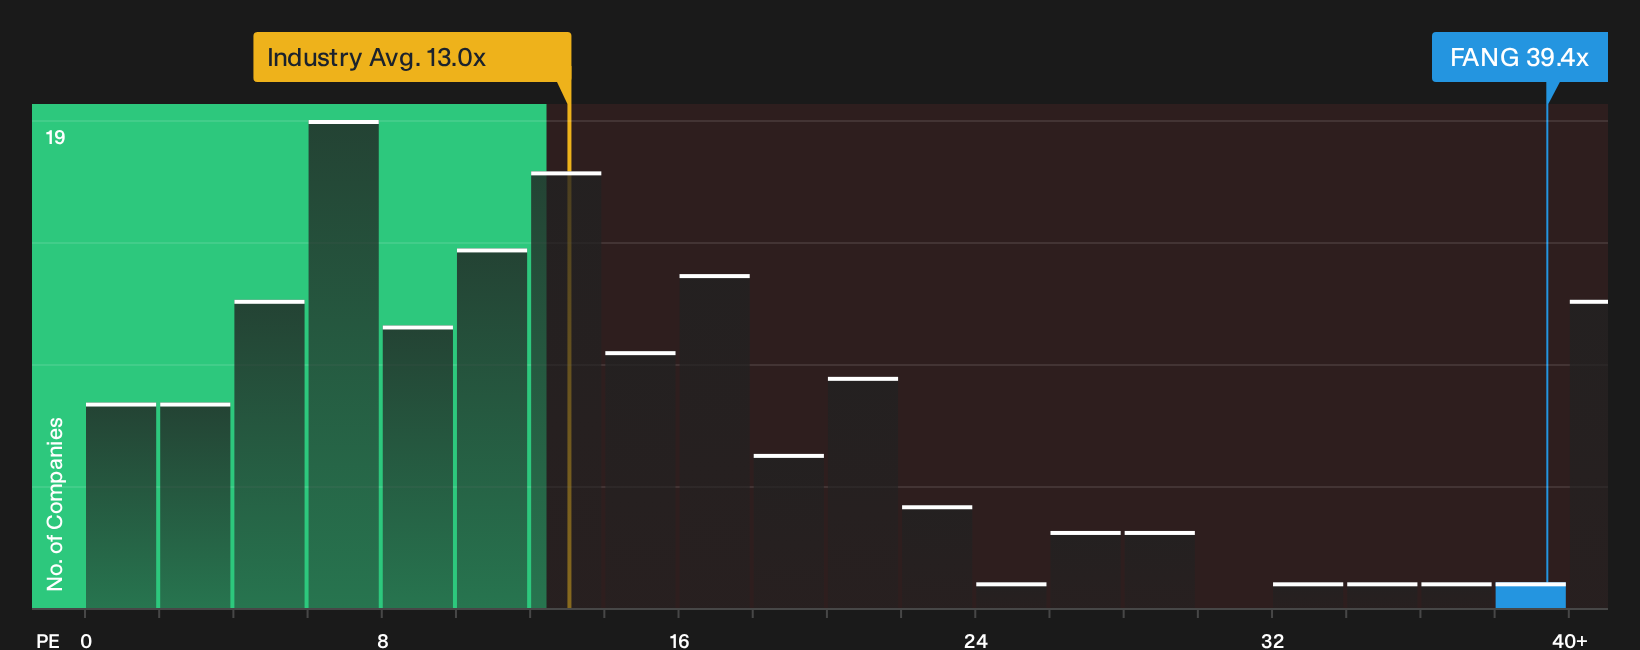
There is a very different message coming from the P/E ratios. Diamondback Energy trades on about 39.4x earnings, which is higher than the US Oil and Gas industry at roughly 13x and also above peers at 12.3x. It also screens above a fair ratio of 27.8x, which points to valuation risk if sentiment cools.
For investors comparing these signals, the question is whether the earnings outlook or the current multiple ends up moving more.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Diamondback Energy’s valuation and risk profile can feel confusing, so review the data while it is fresh and stress test it yourself against the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Diamondback Energy?
If Diamondback Energy has your attention, do not stop here. Broaden your watchlist with fresh ideas that match your style before those opportunities move further away.
- Spot potential turnaround stories early by scanning the 21 elite penny stocks with strong financials that already combine market attention with stronger balance sheets and cleaner financials.
- Target quality at a sensible price by reviewing the 32 high quality undervalued stocks that blend solid cash generation with balance sheets that can support future plans.
- Prioritize resilience and sleep-better-at-night holdings through the 11 resilient stocks with low risk scores that already clear strict financial health and risk filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com