
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Branch Closures Might Change The Case For Investing In JACCS Stock (TSE:8584)
- JACCS Co., Ltd. has approved an organizational restructuring that will consolidate its credit screening operations from 11 sites to 7 by April 1, 2027, closing branches in Sapporo, Nagoya, Fukuoka and Okayama and introducing workforce rationalization for affected employees.
- The restructuring aligns with the medium term "Do Next!" plan, as JACCS leans further into digital credit processes and concentrates decision making in Tokyo and Osaka to reduce complexity and tighten cost control.
- With that context, the focus now shifts to how this consolidation of credit screening hubs may influence JACCS' broader investment narrative for investors.
What Is JACCS' Investment Narrative?
For anyone considering JACCS, the core belief is simple. You need to think of a consumer finance platform that leans into digital credit, tighter underwriting and disciplined cost control, and can still create value even if growth is relatively measured. The consolidation of screening centers and promotion of a new executive for the guarantee unit both point to management trying to simplify operations, remove duplication and keep capital spending focused on systems rather than branches. In the short term, the key watchpoints remain execution on digital processes, credit quality and funding costs.
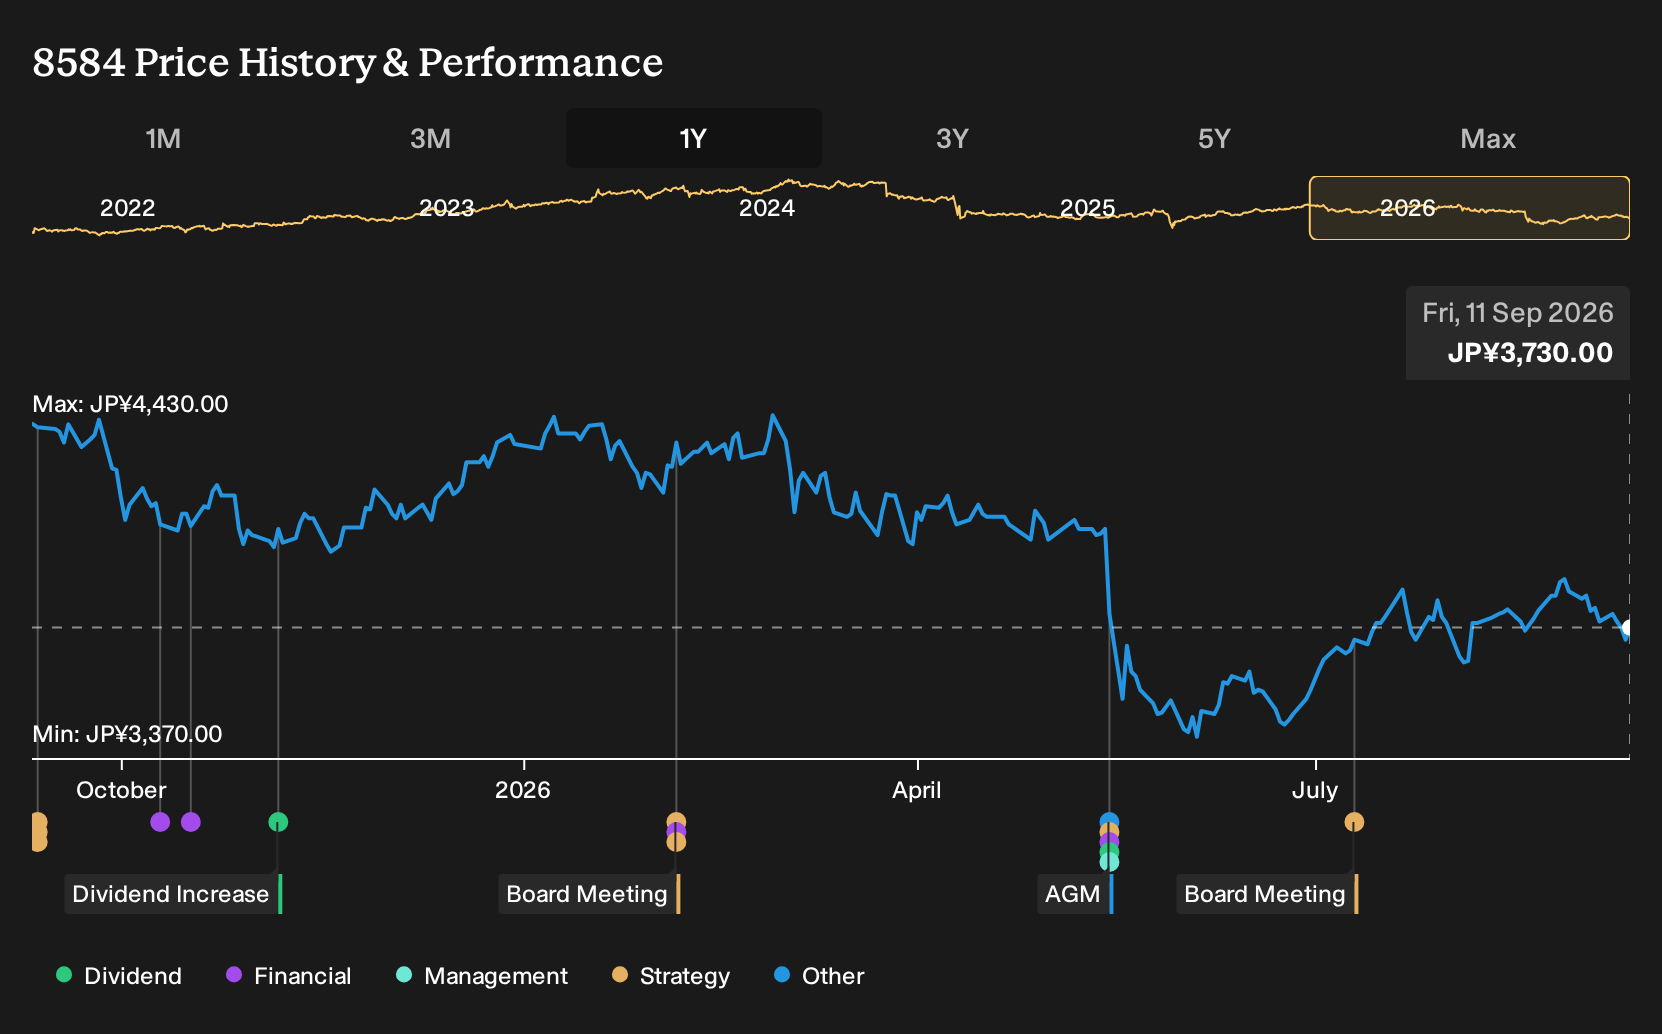
The recent 1 year share price decline of about 11% and a longer stretch of weaker earnings trends put more pressure on this restructuring to translate into better profitability. Debt coverage by operating cash flow is flagged as an issue, so efficiency moves matter for balance sheet resilience, not just optics. An investor also has to be comfortable that a business with forecast earnings growth of 3.4% and a P/E of 11.1x can still justify a thesis built around value and gradual improvement, rather than rapid expansion.
That said, there is a structural weak spot in the JACCS story that could quickly matter a lot more if ...
There's only one way to know the right time to buy, sell or hold JACCS. Head to Simply Wall St's company report for the latest analysis of JACCS's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your JACCS research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for JACCS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JACCS' overall financial health at a glance.
Looking For More Ideas Beyond JACCS?
If you want to put JACCS in context, it helps to compare it with other companies that share similar qualities or offer very different risk and return profiles. The Simply Wall St Screener lets you quickly surface groups of stocks built around the traits you care about most, from resilient balance sheets to income potential.
- If capital preservation matters most, you might start with companies that have steadier risk profiles and review the 10 resilient stocks with low risk scores that score well on that front.
- For readers who like the idea of solid financial footing, scan the list of solid balance sheet and fundamentals (19 results) to see which businesses pair healthy balance sheets with consistent fundamentals.
- If you are hunting for mispriced opportunities and want a wider watchlist, take a look at the 16 high quality undervalued stocks that screen for quality fundamentals at lower valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com