
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
I.D.I. Insurance (TASE:IDIN) Faces A CEO Change, Is The Stock Undervalued?
CEO transition puts I.D.I. Insurance in focus
The planned CEO change at I.D.I. Insurance (TASE:IDIN) has put the insurer back on investor watchlists. After more than eight years in the role, Kobi Haber has informed the board that he intends to step down.
Recent trading tells a mixed story for I.D.I. Insurance. The share price slipped 2.6% over the last day and 6.6% over the week, yet it still shows a 15.2% 90 day share price return and a 1 year total shareholder return of 31.6%, with multi year total shareholder returns running into several times the original investment. This suggests that investors may be reassessing short term leadership risk after a strong run rather than abandoning the longer term thesis.
Scan how I.D.I. Insurance compares with other insurers working through leadership changes by reviewing our curated 100 resilient stocks with low risk scores.I.D.I. Insurance has produced strong total returns over several years, yet the latest pullback and CEO transition raise a sharper question: Is this still a strong business offered at a sensible price today?
Price-to-earnings of 10.1x for I.D.I. Insurance: Is it justified?
I.D.I. Insurance trades on a P/E of 10.1x, which sits below the Asian insurance sector average of 11.3x even though it is above the 9.4x peer group average. That mix of signals puts the current ₪252.3 share price in a kind of middle ground where the stock screens as relatively inexpensive against the broader region but not obviously cheap against closer comparables.
The P/E ratio compares what investors pay today for each unit of current earnings. For insurers like I.D.I. Insurance, it offers a quick read on how the market prices the business relative to its profit stream, which is especially useful when growth forecasts are limited or unclear.
Context matters here. The firm has grown earnings by 22% per year over the past 5 years, while the most recent yearly increase was 1.3%. There is insufficient data to judge how profits or revenue might develop from here. That combination suggests the current P/E may be capturing a strong multi year earnings record alongside a more muted recent trend, without any explicit market view on future acceleration.
The cross check against sector data is sharp. I.D.I. Insurance is described as good value versus the wider Asian insurance industry on its 10.1x P/E, yet it is labelled expensive relative to a 9.4x peer average. That contrast signals that investors are paying a premium compared to immediate peers but still at a discount compared to the broader regional group. This balance could change if sentiment toward either cluster changes.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 10.1x (ABOUT RIGHT)
Still, the CEO handover and any shift in how I.D.I. Insurance balances profit with claims and capital needs could unsettle that steady long term performance narrative.
Find out about the key risks to this I.D.I. Insurance narrative.
Another view on I.D.I. Insurance’s value
The P/E paints I.D.I. Insurance as roughly fairly placed, but the SWS DCF model points in a different direction. On that approach, the estimated future cash flow value is ₪360.44 per share versus a market price of ₪252.3, which implies the stock trades at about a 30% discount. The real puzzle is whether this gap reflects caution around the CEO transition or an opportunity that the market has not fully priced in yet.
Look into how the SWS DCF model arrives at its fair value.
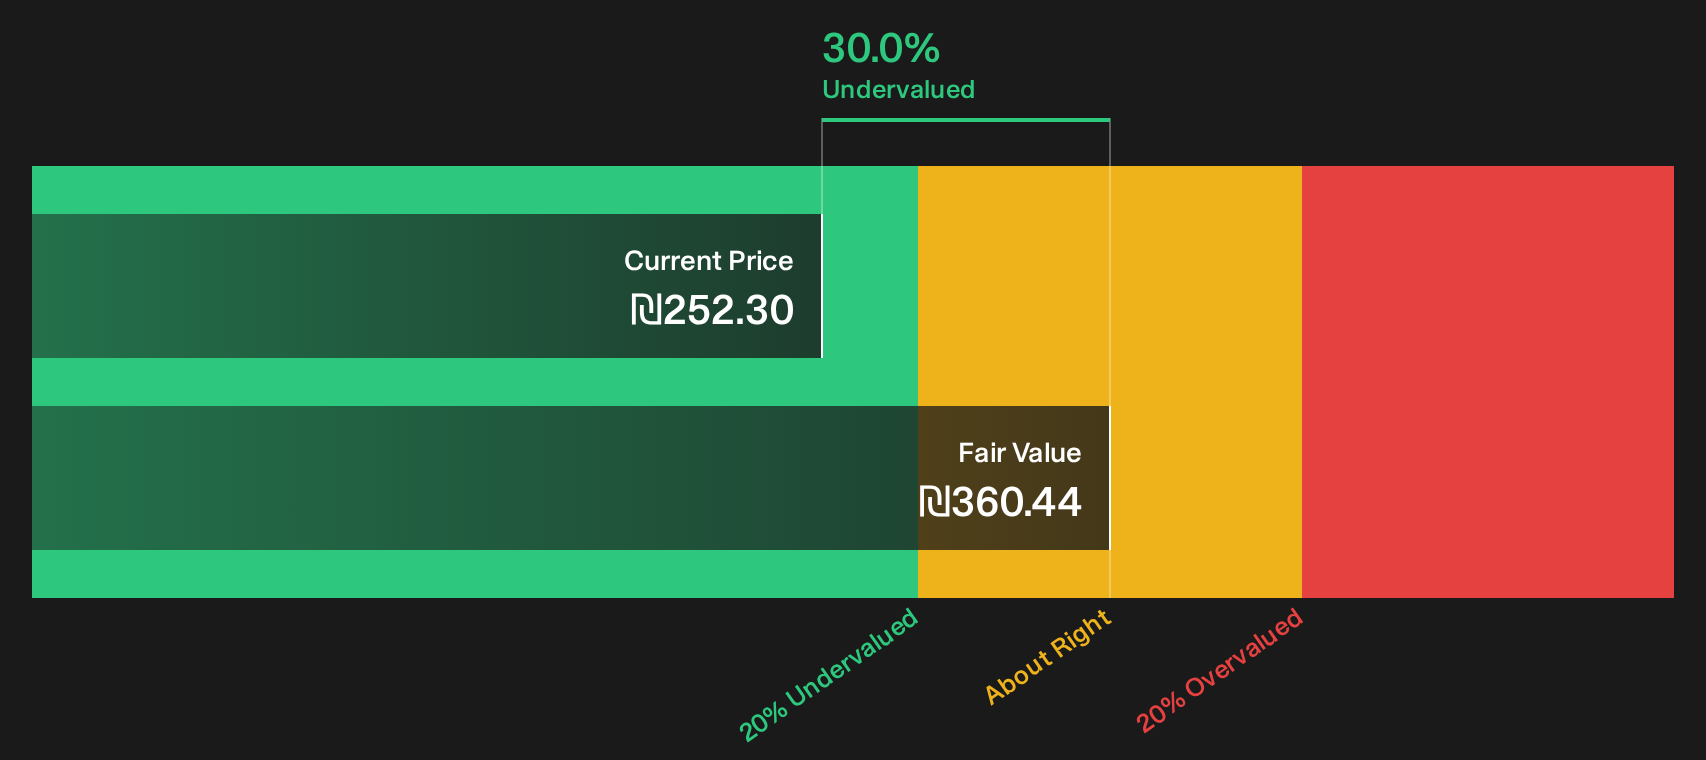
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out I.D.I. Insurance for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around I.D.I. Insurance is clearly mixed, so if this CEO transition and valuation gap matter to you, move quickly and ground your own view in the underlying numbers by weighing both the potential upsides and the issues that could hold the business back through 2 key rewards and 1 important warning sign
Looking for more ideas beyond I.D.I. Insurance?
If I.D.I. Insurance has caught your attention, do not stop your research here. Broaden your opportunity set and compare it with other potential candidates.
- Target potential mispricings by scanning companies that screen as stronger value opportunities through the 182 high quality undervalued stocks.
- Strengthen your income watchlist by reviewing the 163 dividend fortresses that could complement or contrast I.D.I. Insurance in a portfolio.
- Prioritise resilience by checking the list of solid balance sheet and fundamentals (194 results) so you do not miss sturdier alternatives while markets are still offering choice.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com