
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 U.S. Mortgage Servicer Stocks That Could Gain From Higher Rates
Higher rate expectations, stickier inflation signals and oil above US$100 are reshaping which parts of the market feel pressure and which quietly gain leverage. That combination is creating pockets of opportunity and risk for mortgage servicers and mortgage-credit insurers, whose fortunes can shift as borrowing costs stay elevated. This article explains the story behind the headlines and outlines three stocks exposed to this news backdrop that investors may want to keep on their radar.
The three stocks discussed below are only a starter sample. The full screen surfaced 33 more U.S. mortgage servicers and mortgage-credit insurers with equally compelling narratives that are not covered in this article.
To go straight to the source and identify, compare and analyze the highest-conviction ideas in this niche, head into the U.S. Mortgage Servicers and Mortgage-Credit Insurers Benefiting from Higher-for-Longer Rates screener.
Finance of America Companies (FOA)
Finance of America Companies focuses on home equity based financing for retirees, a niche that can benefit when higher-for-longer rates slow traditional refinancing and increase the value of servicing cash flows. Retirement Solutions produced about US$279 million of revenue, Portfolio Management about US$111 million, on a U.S. base of roughly US$337 million, with a market value near US$264 million.
Finance of America Companies provides targeted exposure to mortgage servicing economics tied to home equity and reverse mortgages during a period of higher-for-longer rates that keep prepayments in check. The stock offers this thematic exposure through a smaller market cap and one unresolved funding pressure that could affect margins if conditions change.
That funding question is exactly why a closer look at the 2 key rewards and 1 important major warning sign could be useful as higher-for-longer economics reshape Finance of America Companies.

Redwood Trust (RWT)
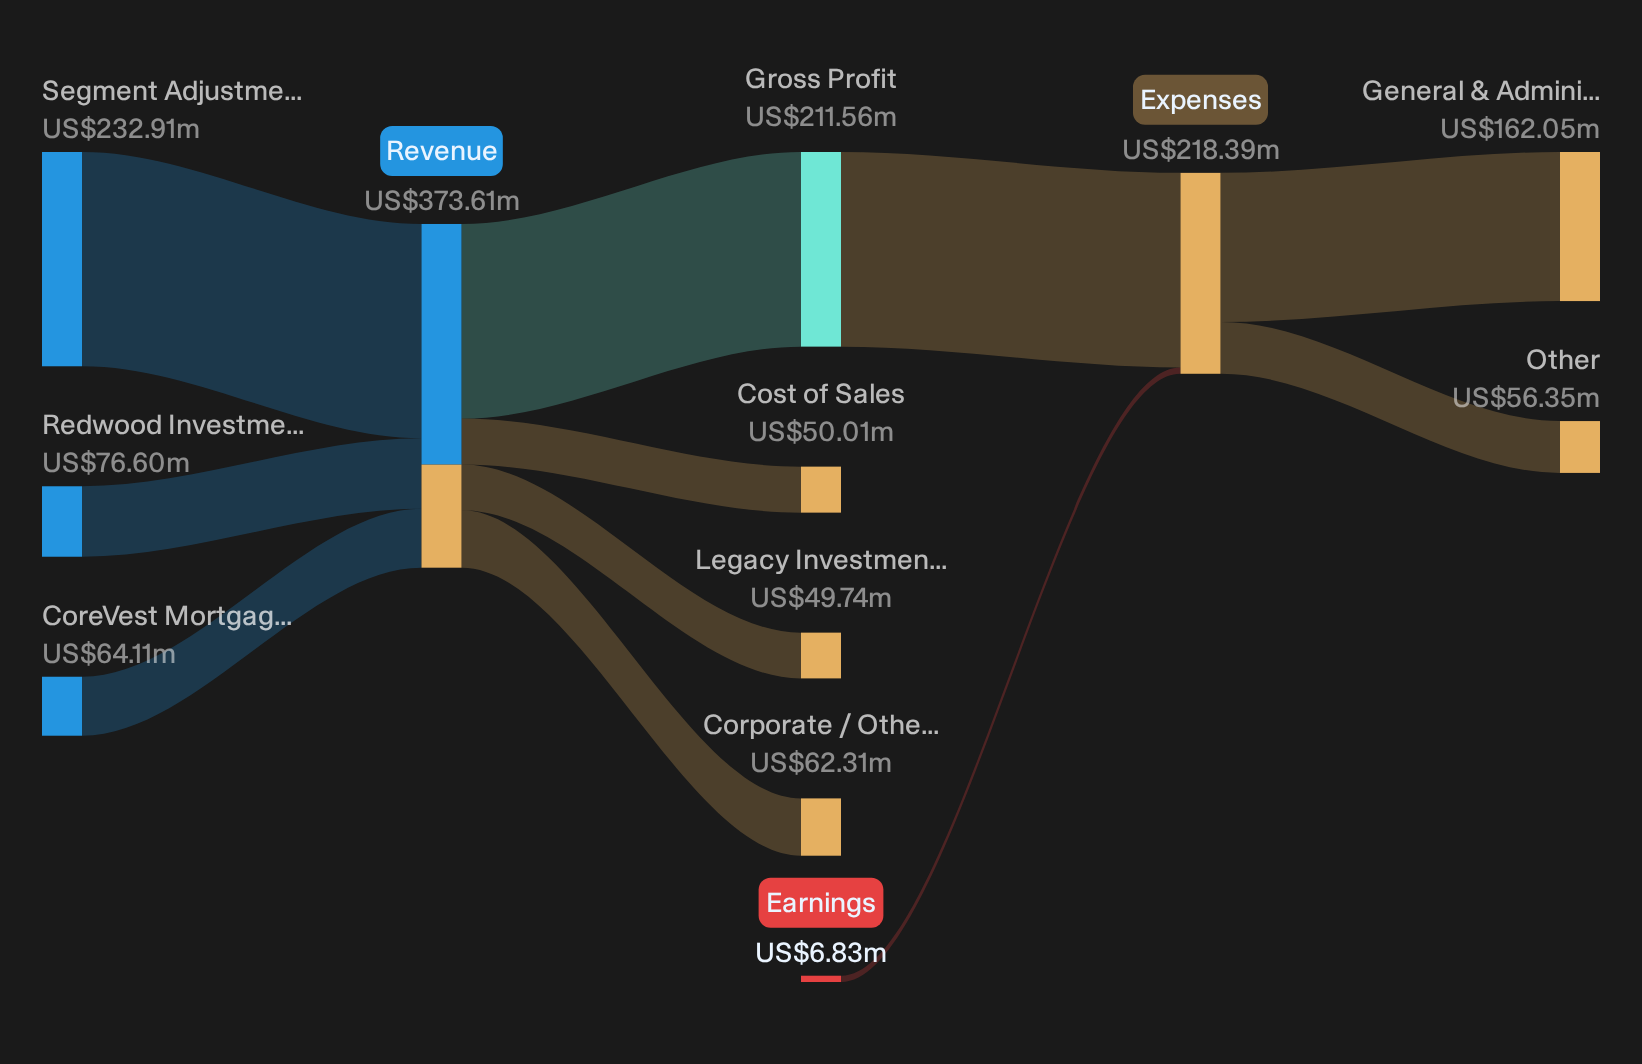
Redwood Trust is a mortgage-focused finance company that acquires and securitizes residential loans, with all of its US$262 million of segment revenue tied to U.S. housing credit and servicing economics. Redwood Investments generated about US$77 million, CoreVest Mortgage Banking about US$64 million, and the group carries a market value near US$446 million.
Redwood Trust gives you pure exposure to mortgage credit and servicing spreads that can benefit when higher-for-longer rates slow prepayments. However, it relies entirely on wholesale funding and an uncovered high dividend, so everything comes down to how the pressure on its cost of money resolves for margins and growth potential.
That funding pivot is exactly where the story gets interesting, and the 3 key rewards and 2 important warning signs (2 are major!) lays out how those pressures could be masking upside or amplifying downside.
Walker & Dunlop (WD)
Walker & Dunlop sits squarely in the higher-for-longer theme, originating, selling and servicing multifamily and commercial real estate loans that can build valuable mortgage servicing rights when prepayments slow, with about US$686 million from Capital Markets, US$497 million from Servicing & Asset Management, US$11 million from Corporate and a roughly US$1.4b market cap.
For investors focused on mortgage servicers that may benefit from slower refinancing and stickier servicing income, Walker & Dunlop offers something different. The business leans on multifamily and commercial real estate credit, where loan performance and fee streams often hinge on rate stability as much as rate direction.
"Investments in technology platforms (small balance lending, appraisal, Galaxy, Client Navigator) are resulting in higher client acquisition (17% of YTD volume from new clients), increased operational efficiency, and improved margins, suggesting longer-term enhancement of net margins and top-line growth."
What really matters now is how one less visible pressure on those fee streams ultimately shapes the earnings path investors are counting on.
That earnings pressure is exactly why reading the full narrative for Walker & Dunlop can help you see where Walker & Dunlop’s fee engine may be quietly accelerating next.

Seeking Fresh Alternatives Before They Fly
New themes can move quickly, and early breakouts rarely stay under the radar for long. Identify momentum while it still matters, before prices adjust further, and consider potential opportunities at an earlier stage.
- Review cash-generative AI companies before they appear crowded by exploring the curated list of 74 profitable AI stocks that aren't just burning cash while they are still under the radar for now.
- Focus on companies with strong balance sheets and resilient earnings power using the list of solid balance sheet and fundamentals (23 results) list before defensive quality is more widely recognized.
- Explore miners with operational leverage to bullion price moves using the 35 elite gold producer stocks group while sentiment shifts may still be creating mispricings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com