
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
MediPal Holdings (TSE:7459) Faces Investor Pressure, Is The Discount Too Wide?
Investor pressure is now front and center at MediPal Holdings (TSE:7459) after Silchester International Investors called for an extraordinary shareholder meeting to seek board change, higher payouts, and a sizeable capital return.
MediPal Holdings now trades at ¥2,886, with a 90 day share price return of 10.60% and a 1 year total shareholder return of 9.61%. This suggests that momentum has been building as activism around capital returns and the JR-446 trial comes into focus.
Scan how activism and capital return themes are playing out across other opportunities by reviewing the hand-picked 16 high quality undervalued stocks currently catching investors' attention alongside MediPal Holdings.
Recent gains at MediPal Holdings could be read as a vote of confidence in its broad healthcare platform, or as a short term reaction to activist pressure and JR-446 headlines. Which story does the valuation reflect?
Preferred P/E of 12.7x for MediPal Holdings: Is it justified?
MediPal Holdings trades at ¥2,886, and the current P/E of 12.7x lines up with a stock that appears cheaper than both its peers and an estimated fair earnings multiple.
The P/E ratio compares what investors pay for each unit of earnings, which is especially relevant for a mature distributor and healthcare platform where profits and cash generation matter more than rapid expansion.
For MediPal Holdings, the market is applying a 12.7x P/E, while the JP Healthcare industry averages 13.5x and the estimated fair P/E ratio is 19x. This represents a discount relative to both the industry and the estimated fair multiple.
Explore the SWS fair ratio for MediPal Holdings.
Result: Price-to-Earnings of 12.7x (UNDERVALUED)
Still, the JR-446 outcome and any shift in activism at MediPal Holdings could quickly challenge the current P/E story and reset expectations around capital returns.
Find out about the key risks to this MediPal Holdings narrative.
Another View on MediPal Holdings Using Cash Flows
The earnings multiple points to MediPal Holdings trading cheaply, and the SWS DCF model goes further. At ¥2,886 against a future cash flow value estimate of ¥3,986.95, the share price screens as undervalued on a cash flow lens as well. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
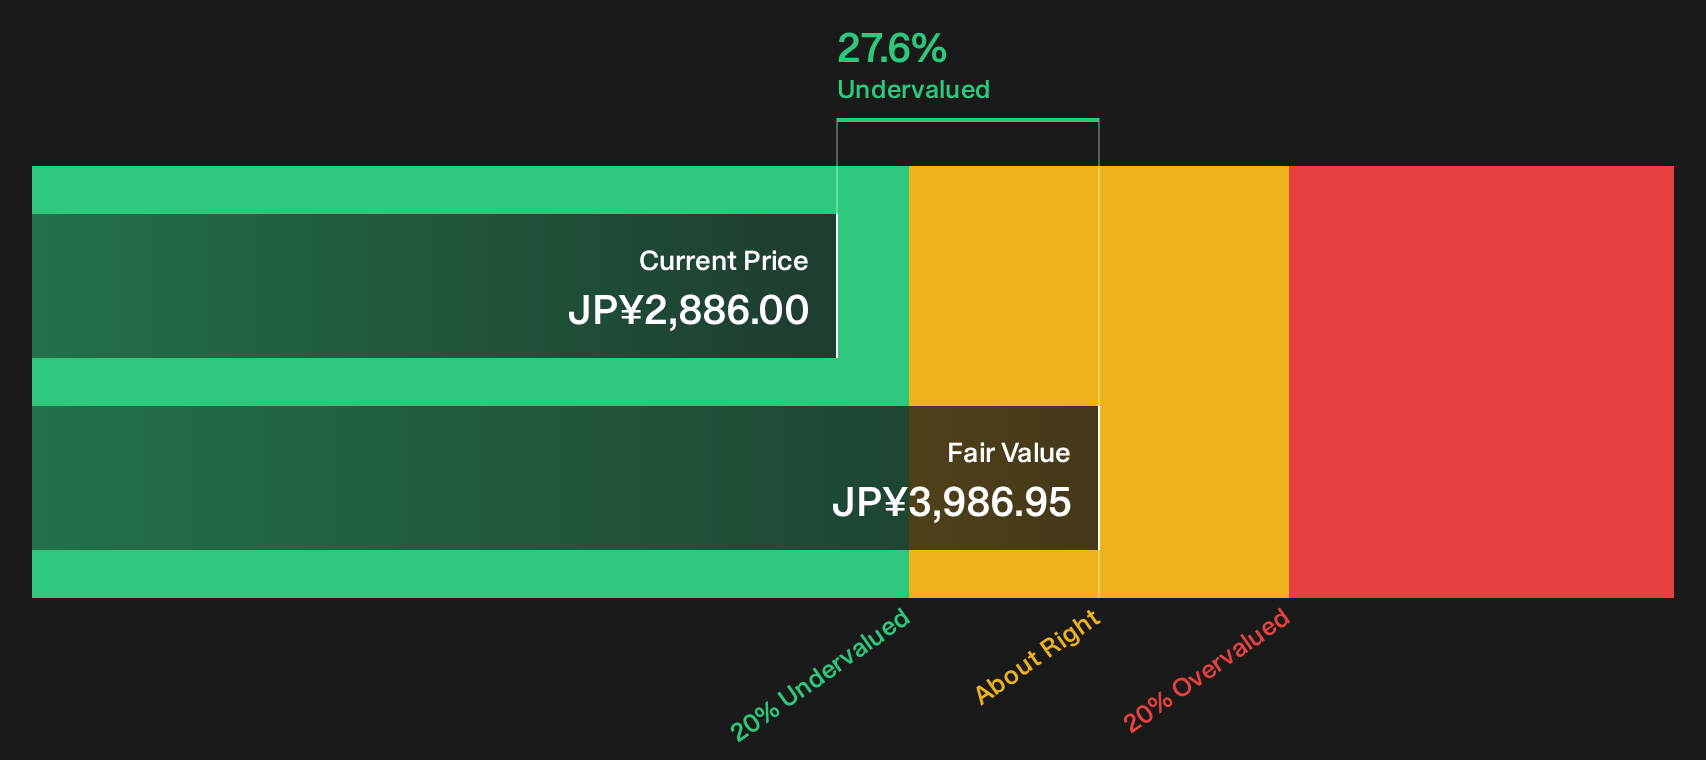
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MediPal Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum, activism and JR-446 headlines all pull sentiment in different directions, so move quickly, review the underlying data, and decide how you feel about MediPal Holdings by checking the 5 key rewards.
Looking for more investment ideas beyond MediPal Holdings?
Once you have a view on MediPal Holdings, you may want to broaden your watchlist with a few targeted ideas that could help you decide where to allocate your next yen.
- Target resilience by reviewing a curated 10 resilient stocks with low risk scores that may help you focus on businesses with steadier profiles when markets start to feel unpredictable.
- Seek value by scanning the 73 high quality undiscovered gems that screen well on quality yet still fly under most investors' radar.
- Strengthen your core holdings by filtering for companies in the list of solid balance sheet and fundamentals (19 results) that might support more durable performance through different market conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com