
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Banca Monte Dei Paschi Di Siena (BIT:BMPS) Issued Green Notes, Is The Stock Now Overvalued?
Why Banca Monte dei Paschi di Siena’s New Bond Deal Matters For Equity Investors
Banca Monte dei Paschi di Siena (BIT:BMPS) has raised about €497.5 million through subordinated fixed to floating rate notes due 2037, structured as callable green bonds under Regulation S.
The issue adds a fresh layer of long dated, variable rate funding that sits below senior creditors. This can influence how you think about the bank’s capital stack and risk profile as a shareholder.
The new green bond lands while Banca Monte dei Paschi di Siena’s share price has risen 28.11% year to date, with a 9.39% 90-day share price return and a very large 3-year total shareholder return above 500%. This suggests that investors are rewarding perceived progress while reassessing long-term risk around the bank’s funding mix.
Spot similar stories where banks are reshaping their funding mix and equity case by scanning the list of solid balance sheet and fundamentals (194 results) alongside Banca Monte dei Paschi di Siena’s latest bond move.Banca Monte dei Paschi di Siena now carries a fresh layer of subordinated green debt and a share price that already reflects strong recent gains. Does that mix still leave enough upside to compensate you for the risk?
Most Popular Narrative: 2% Overvalued
Banca Monte dei Paschi di Siena’s most followed valuation narrative sets a fair value of €11.77 against a last close of €11.98, which points to a small premium and puts even more focus on how durable today’s earnings power really is.
The bank's recent strong profit growth and improved asset quality appear to reflect favorable Italian economic conditions. However, with interest rates expected to decline and structural macro headwinds like Italy's aging population persisting, credit demand and loan growth could slow over the longer term. This could compress revenues and ultimately earnings. Current robust net interest income benefits from strong lending volumes and retail deposit growth. The anticipated environment of declining rates in the EU, however, threatens net interest margins and makes it difficult to maintain the current level of profitability, which may lead to margin pressure ahead.
See why 27 investors see Banca Monte dei Paschi di Siena as 2% overvalued.
Result: Fair Value of €11.77 (OVERVALUED)
Still, if Banca Monte dei Paschi di Siena keeps reducing non performing loans and the proposed Mediobanca tie up delivers the projected synergies, this cautious valuation story could change quickly.
Find out about the key risks to this Banca Monte dei Paschi di Siena narrative.
Another View On Banca Monte dei Paschi di Siena’s Value
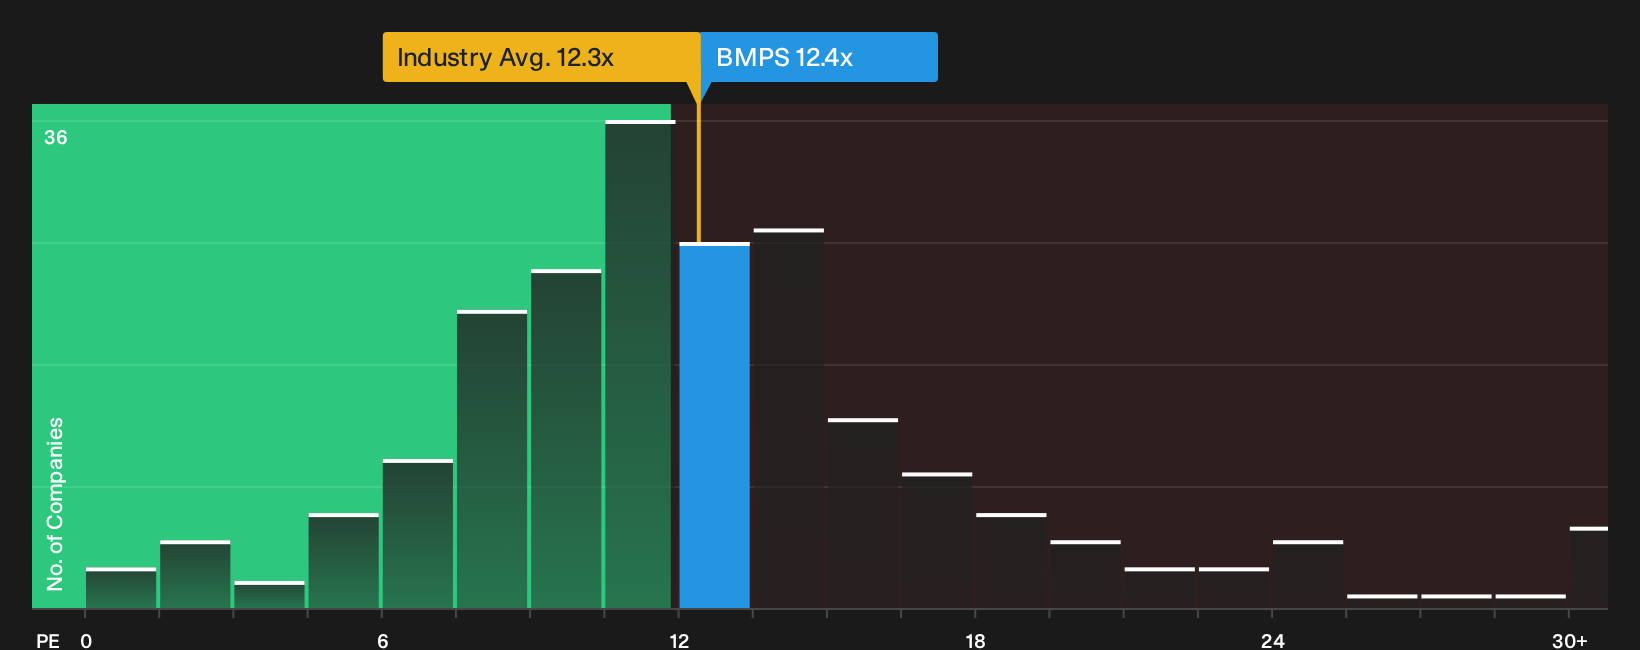
Analysts see Banca Monte dei Paschi di Siena as slightly overvalued at €11.98 versus a €11.77 fair value, yet the P/E picture tells a different story. The shares trade on 12.4x earnings compared with the Italian market at 17.4x and a fair ratio of 13.9x. This points to a cheaper entry point on this metric. Is the market underpricing risk here, or providing a margin of safety that the DCF framework does not fully capture?
See what the numbers say about this price in more depth with our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty in this Banca Monte dei Paschi di Siena story looks encouraging, yet some signals still flash caution. Move quickly, review both sides of the debate, and ground your stance in the 4 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Banca Monte dei Paschi di Siena?
If Banca Monte dei Paschi di Siena has sharpened your focus on risk, return, and balance sheet strength, you may want to broaden your opportunity set with a few targeted idea lists.
- Target resilient cash generators by scanning the 182 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their financial strength.
- Prioritize capital preservation by reviewing the 100 resilient stocks with low risk scores that score well on balance sheet robustness and earnings stability.
- Get ahead of the crowd by researching the 618 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com