
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Universal Insurance Holdings (UVE) Undervalued Following Its $100 Million Debt Exchange Offer?
Universal Insurance Holdings (UVE) has kicked off a fixed income exchange offer for its 7.75% senior unsecured notes due June 30, 2031, covering US$100 million in principal. The move immediately puts the insurer’s capital structure in focus for equity investors.
Over the past year, Universal Insurance Holdings has seen steady momentum build, with a 90 day share price return of 19.62%, a year to date share price gain of 39.80%, and a 1 year total shareholder return of 78.34%.
Capitalize on the attention around Universal Insurance Holdings' exchange offer by comparing it with a hand picked group of insurers and financials screened for balance sheet strength in our list of solid balance sheet and fundamentals (23 results).After a run like this and a recent move on its debt stack, Universal Insurance Holdings presents a straightforward decision point: should investors step in now, or wait for a clearer entry after additional valuation analysis?
Most Popular Narrative: 1% Overvalued
The most followed narrative currently anchors Universal Insurance Holdings to a fair value of $44, which sits almost exactly on the recent $44.33 close, leaving only a small implied premium once the 7.1% discount rate is applied.
Recent strong premium growth outside Florida (+25.4% year-over-year), alongside higher overall policies in force, demonstrates the company's success diversifying geographically. This reduces concentration risk and is expected to help stabilize and support future revenue growth and earnings. The company is capturing higher premiums due to increases in property values and inflation adjustments, which aligns with broader rising reconstruction and replacement costs. This is likely to support sustained top-line growth and improve total revenue.
See why 6 investors see Universal Insurance Holdings as 1% overvalued.
Result: Fair Value of $44 (OVERVALUED)
Still, the narrative can wobble if higher ceded premium costs and expense ratios squeeze underwriting results, or if Florida competition further chips away at direct premiums.
Find out about the key risks to this Universal Insurance Holdings narrative.
Another View: Universal Insurance Holdings Through Earnings Multiples
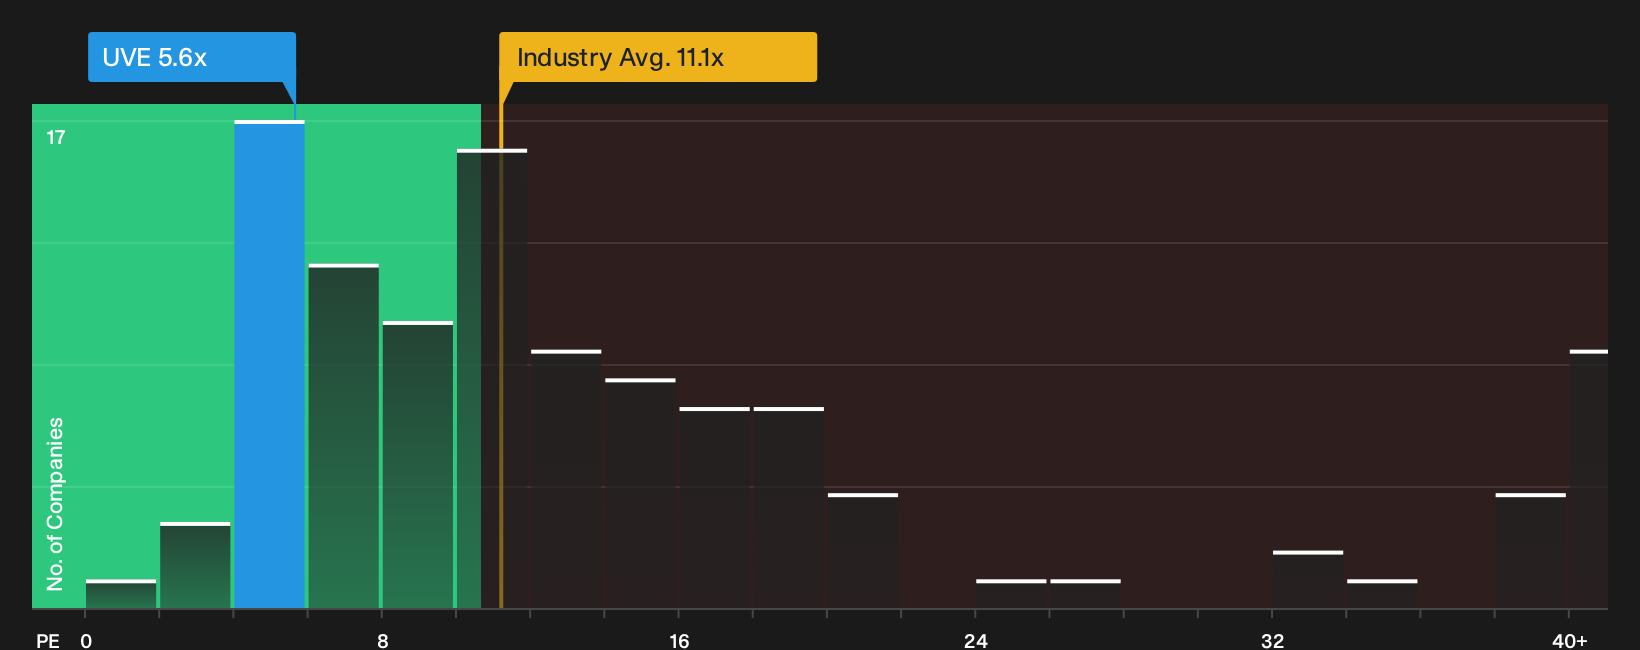
That fair value narrative sits awkwardly next to what the market is actually paying for Universal Insurance Holdings today. The shares trade on a P/E of 5.6x while the US Insurance group averages 11.1x and the fair ratio sits at 7.7x, which points to a sizeable valuation gap that could either close through price moves or changing fundamentals. For investors, the key question is whether that discount reflects temporary caution or a more permanent reset in expectations.
To see how this pricing gap lines up with the rest of the numbers, including peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Universal Insurance Holdings story so far. If you want to move quickly and build your own view from the ground up, start by weighing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Universal Insurance Holdings?
Do not stop with Universal Insurance Holdings. Use the broader toolkit to spot fresh opportunities, compare quality, and pressure test your thesis against completely different business profiles.
- Chase potential mispricing by scanning a curated pool of companies screened for quality and valuation through the 32 high quality undervalued stocks.
- Build a steadier income stream by hunting for businesses with stronger yield profiles and payout support using the 6 dividend fortresses.
- Prioritize resilience by sorting for companies screened on financial strength and low risk markers via the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com