
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
MDU Resources Group (MDU) Pulls Back, Is It Trading Below Fair Value?
MDU Resources Group (MDU) has drawn fresh attention after recent trading left the stock down about 7% over the past month and roughly 9% over the past 3 months.
That recent slide sits within a more mixed picture for MDU Resources Group, where the share price has drifted lower in the short term, but the 1-year total shareholder return of 21.5% and 3-year total shareholder return of 85.1% still point to strong longer run gains.
Scan beyond MDU Resources Group and compare this recent pullback with other regulated utilities on our hand picked 39 power grid technology and infrastructure stocks to see how similar infrastructure focused stocks are trading right now.
Bulls view MDU Resources Group as a regulated utility with steady operations and a pullback that may improve the odds of a fair deal. Bears see a value trap following a strong multi year run. Which side does current pricing support?
Most Popular Narrative: 18% Undervalued
On the most followed view of MDU Resources Group, a fair value of $23.29 sits above the recent close at $19.20. This puts the latest pullback in a different light for anyone weighing risk against potential upside.
Strong ongoing and future investment in U.S. infrastructure, including large pipeline expansion projects and potential new transmission or generation to serve data centers, positions MDU to benefit from robust construction demand and growing energy needs, providing significant future revenue and earnings uplift.
A growing, diversified project pipeline and storage opportunities in the Bakken, supported by state interest and customer commitments, offer optionality for incremental growth beyond what is currently forecast, increasing upside potential for future earnings and cash flows.
See why 4 investors see MDU Resources Group as 18% undervalued.
Result: Fair Value of $23.29 (UNDERVALUED)
Still, the bullish setup around MDU Resources Group can unravel if energy transition policy accelerates away from natural gas, or if large capital projects face cost or regulatory setbacks.
Find out about the key risks to this MDU Resources Group narrative.
Another Angle On MDU Resources Group’s Valuation
The SWS DCF model paints a different picture for MDU Resources Group. On that view, the recent price of $19.20 sits slightly above an estimated future cash flow value of $18.84, which points to a stock that screens as modestly overvalued rather than clearly cheap.
That gap is small in absolute terms, yet it raises a practical question for you as an investor. Is the current price reflecting optimism about growth that may not fully materialize in cash flows, or is this just normal noise around a fair value range?
Look into how the SWS DCF model arrives at its fair value.
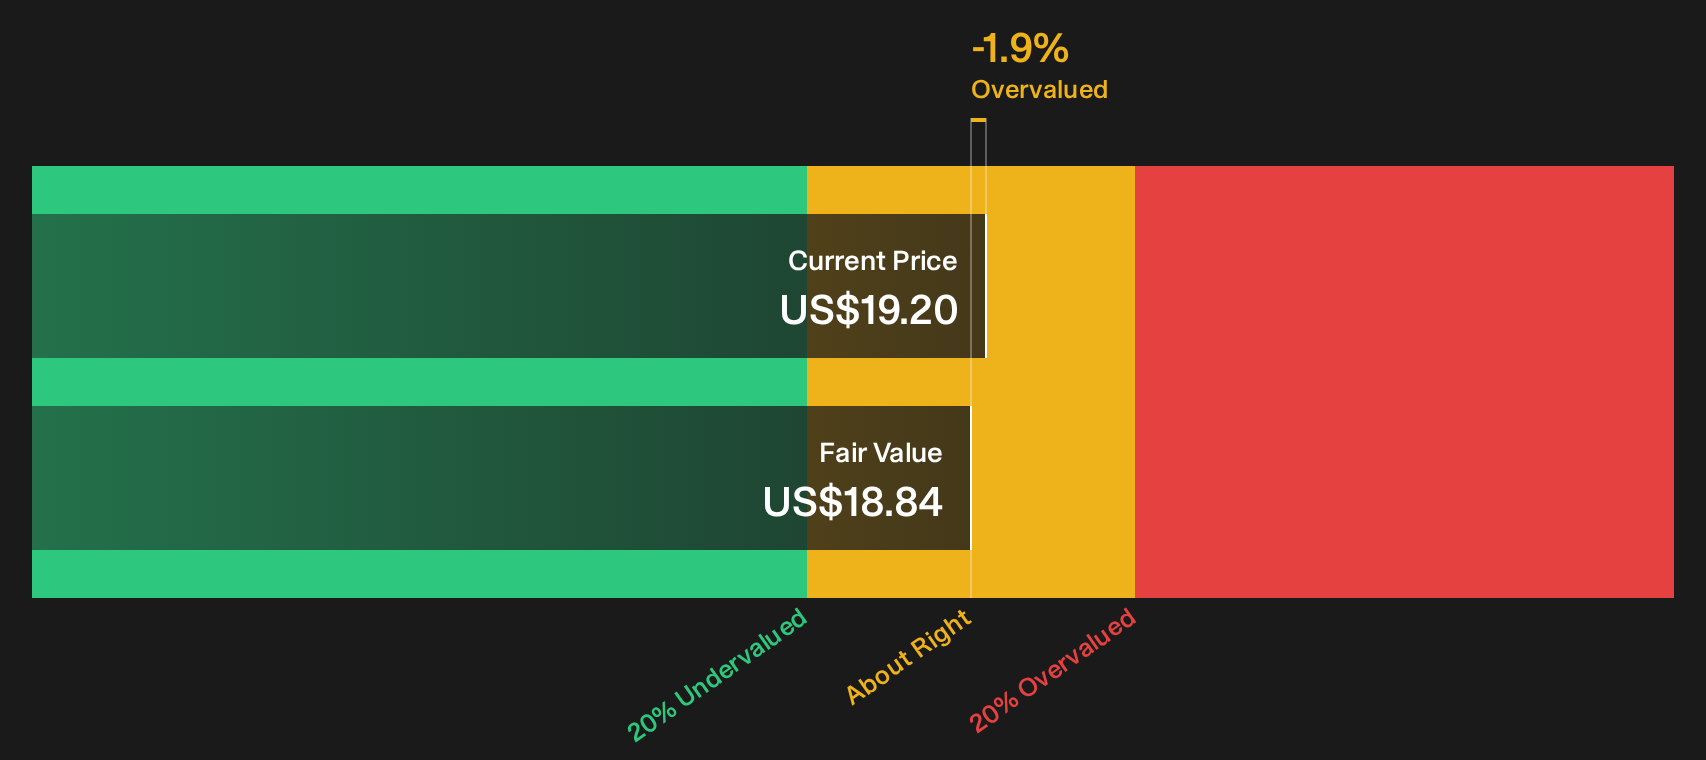
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MDU Resources Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on MDU Resources Group so far. If you want to move quickly and build your own view from the ground up, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond MDU Resources Group?
You have seen how mixed signals can shape MDU Resources Group. Do not stop here. Use the same disciplined lens to compare other opportunities and pressure test your next move.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (23 results) that lets you focus on businesses with durable finances backing their operations.
- Chase value with guardrails using a 32 high quality undervalued stocks that highlights companies combining quality metrics with prices that still look reasonable.
- Hunt for early stage potential through a 15 high quality undiscovered gems that surfaces lesser known stocks with fundamentals that may warrant a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com