
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
European Undervalued Small Caps With Insider Activity For September 2026
In September 2026, European small-cap stocks are navigating a challenging landscape marked by rising oil prices and inflation concerns, as the pan-European STOXX Europe 600 Index fell by 1.66% amid geopolitical tensions and an interest rate hike from the ECB. Despite these headwinds, opportunities may arise for investors seeking value in small-cap companies with insider activity, as these stocks can offer unique insights into potential growth prospects within a volatile market environment.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genus | 5.1x | 2.2x | 33.56% | ★★★★★★ |
| Franchise Brands | 27.5x | 2.0x | 47.13% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 13.13% | ★★★★☆☆ |
| Saniona | 7.6x | 3.3x | 28.90% | ★★★★☆☆ |
| Linc | 12.7x | 13.2x | 31.24% | ★★★★☆☆ |
| Eurocell | 21.8x | 0.3x | 49.35% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 21.26% | ★★★☆☆☆ |
| KlaraBo Sverige | 7.2x | 2.8x | -176.79% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -212.32% | ★★★☆☆☆ |
| Krona Public Real Estate | 8.7x | 4.9x | 35.34% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
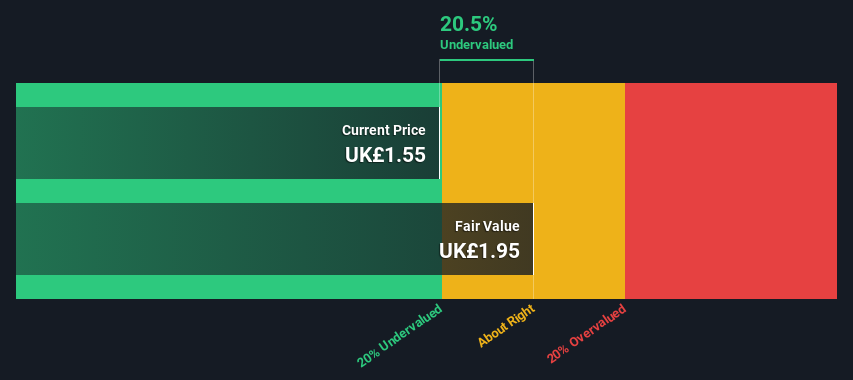
Franchise Brands (AIM:FRAN)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Franchise Brands is a multi-brand franchisor focused on building market-leading businesses primarily in the B2C, Azura, Pirtek, Filta International, and Water & Waste Services sectors with a market cap of approximately £0.25 billion.
Operations: Franchise Brands generates revenue primarily from Pirtek (£63.99 million), Filta International (£36.50 million), and Water & Waste Services (£44.57 million). The company's gross profit margin has shown variation, reaching 59.62% in the latter part of 2025, indicating changes in cost management or pricing strategies over time.
PE: 27.5x
Franchise Brands, a smaller European company, shows potential with recent insider confidence as Stephen Hemsley purchased 72,500 shares for £84,200 in July 2026. Despite relying solely on external borrowing for funding, the company reported a sales increase to £75.6 million and net income growth to £6.13 million for the first half of 2026 compared to last year. Earnings per share rose alongside a proposed interim dividend increase of 9%. Earnings are projected to grow by approximately 8% annually.
- Click here to discover the nuances of Franchise Brands with our detailed analytical valuation report.
Assess Franchise Brands' past performance with our detailed historical performance reports.
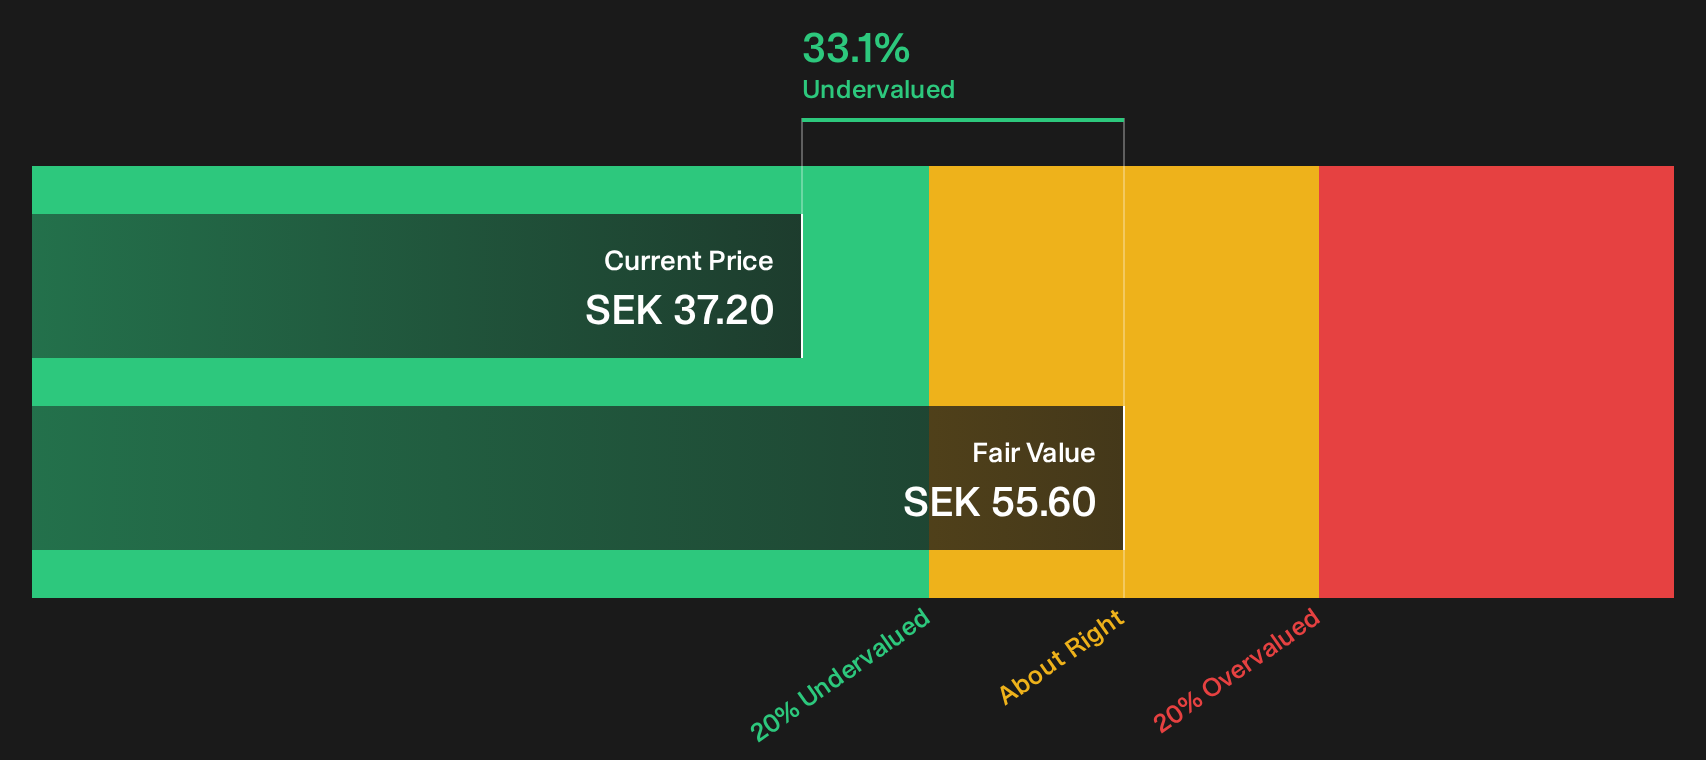
Hexatronic Group (OM:HTRO)
Simply Wall St Value Rating: ★★★★★☆
Overview: Hexatronic Group specializes in providing fiber optic solutions, data center products, and equipment for harsh environments, with a market capitalization of approximately SEK 23.5 billion.
Operations: With a significant portion of revenue derived from Fiber Solutions at SEK 4.73 billion, the company's net income margin has shown variability, with recent figures as low as -0.18% and up to 12.30%. The gross profit margin has seen fluctuations, reaching up to 44.63% but also declining to around 38.01%. Operating expenses have consistently impacted profitability, with general and administrative expenses being a major component.
PE: 188.8x
Hexatronic Group, a European fiber solutions company, has seen dynamic changes with Pernilla Lindén transitioning to President Fiber Solutions by November 2026. Recent earnings highlight an increase in sales to SEK 2.3 billion for Q2 2026 from SEK 1.9 billion the previous year, with net income rising to SEK 131 million from SEK 77 million. The company is expanding its submarine fiber-optic cable production line at Hudiksvall, enhancing capacity and aligning with growing demand for offshore wind infrastructure. Despite volatile share prices recently, Hexatronic's strategic investments and leadership shifts could position it well for future growth in the competitive telecom market landscape.
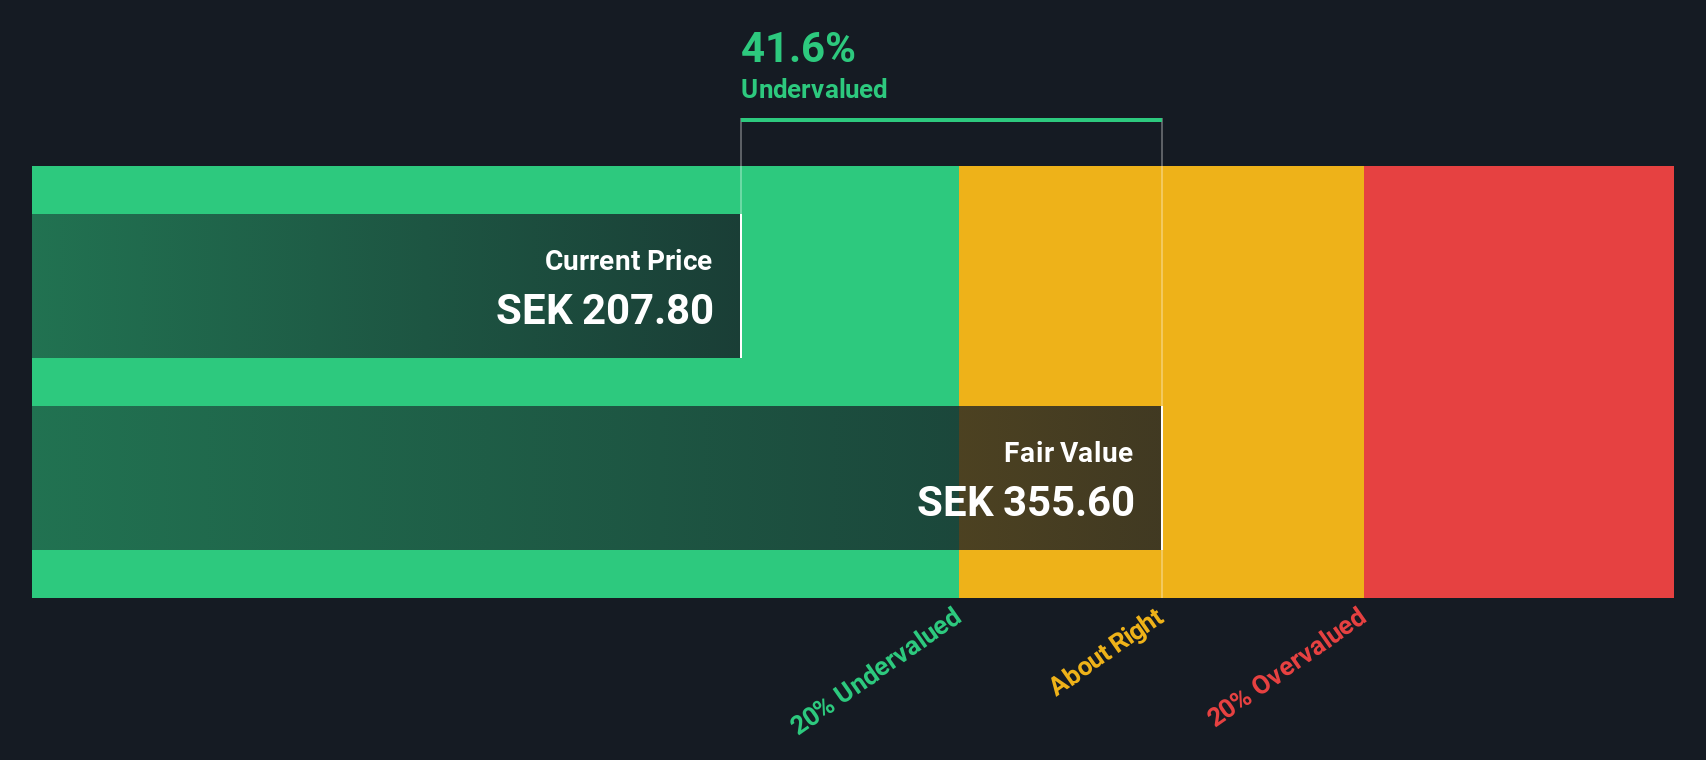
Inwido (OM:INWI)
Simply Wall St Value Rating: ★★★★★★
Overview: Inwido is a company engaged in the design, manufacture, and sale of windows and doors across various segments including East, West, E-Commerce, and Scandinavia with a market capitalization of approximately SEK 8.04 billion.
Operations: The company's revenue primarily comes from its East, West, E-Commerce, and Scandinavia segments. Over recent periods, the gross profit margin has shown fluctuations, with a notable figure of 25.84% in the last reported period. Operating expenses include significant allocations to sales and marketing as well as general and administrative costs.
PE: 20.1x
Inwido, a European player in the building products sector, shows promising potential despite its reliance on high-risk external borrowing. Their recent earnings report for Q2 2026 highlights a sales increase to SEK 2,720.5 million from SEK 2,339 million last year and net income growth to SEK 197.1 million from SEK 155.9 million. Insider confidence is evident as Independent Director Anders Wassberg significantly increased their stake by over two-fold recently with a transaction value of approximately SEK 173.68 million, suggesting belief in future growth prospects bolstered by an anticipated annual earnings rise of over 18%.
- Take a closer look at Inwido's potential here in our valuation report.
Explore historical data to track Inwido's performance over time in our Past section.
Summing It All Up
- Unlock more gems! Our Undervalued European Small Caps With Insider Buying screener has unearthed 33 more companies for you to explore.Click here to unveil our expertly curated list of 36 Undervalued European Small Caps With Insider Buying.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com