
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Fda Warning Letter Might Change The Case For Investing In Jabil Stock
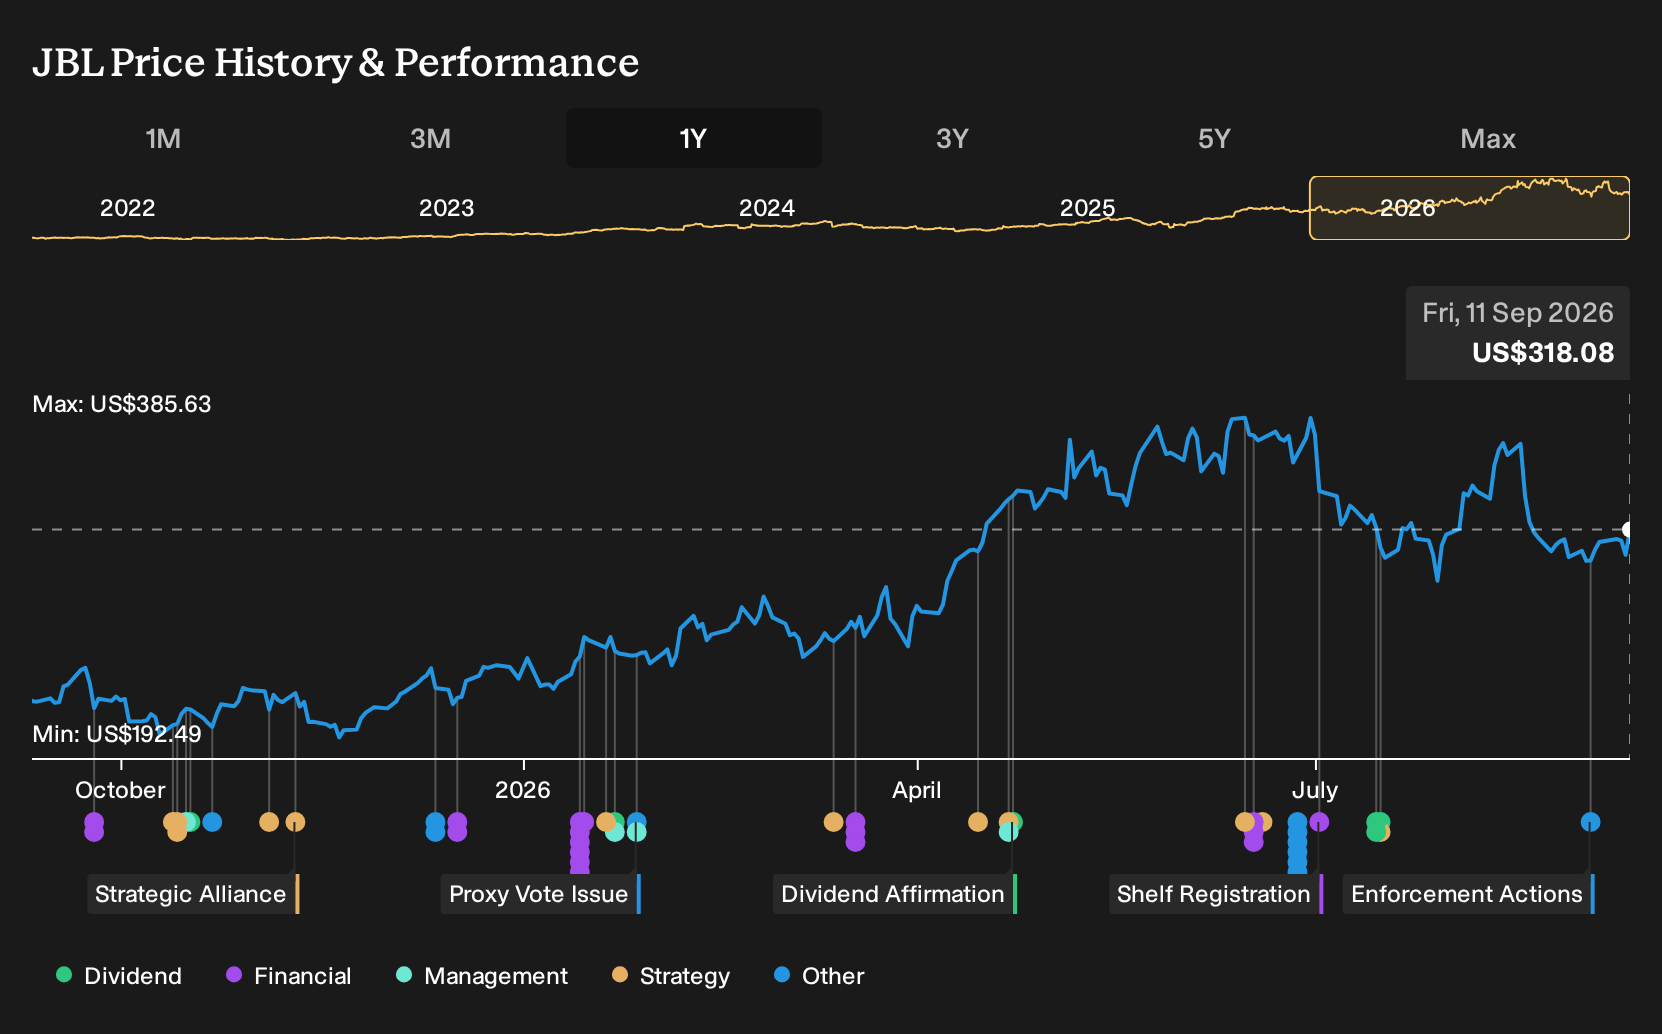
- Jabil received an FDA warning letter dated 2 September 2026 that cited significant Current Good Manufacturing Practice violations at its Pharmaceutics International Inc. sterile injectable facility, including recurring fungal contamination, inadequate investigations and weak corrective and preventive actions.
- The findings highlight operational strain within Jabil’s pharmaceutical manufacturing platform, with gaps in quality oversight, documentation and process validation that could affect remediation costs, production reliability and customer confidence in its drug solutions offering.
- This raises questions about how Jabil's broader investment narrative is affected by the FDA's warning on serious sterile manufacturing control failures.
Jabil Investment Narrative Recap
To own Jabil today, you need to believe the manufacturing platform can keep scaling across Regulated Industries, Intelligent Infrastructure and Connected Living without quality control becoming a drag on execution. The FDA warning around sterile injectables puts the pharmaceutical push under a cloud and, in the near term, pulls attention away from AI related demand and the wider contract manufacturing pipeline.
The nearest term swing factor now sits in how quickly Jabil can address the FDA findings at Pharmaceutics International Inc. The biggest risk is that remediation, production pauses or tighter oversight ripple into higher costs, delayed pharma revenue contribution and tougher conversations with highly regulated healthcare customers.
The acquisition of Pharmaceutics International Inc. was pitched as a way for Jabil to access a US$20b market in pharmaceutical solutions. This FDA letter now sits directly on that thesis, because the sterile injectable facility is central to proving the group can meet Current Good Manufacturing Practice requirements at scale.
For you as a shareholder, the question is less about headline growth targets and more about execution in this regulated vertical. The pharma move was one of the key catalysts, alongside AI demand and India expansion. Until Jabil shows sustained, documented control over investigations, CAPA and quality unit oversight at this site, that specific growth leg carries a higher operational risk tag.
Jabil's current analyst narrative points to US$54.9b in revenue and US$2.2b in earnings by 2029, based on an assumed 17.8% yearly increase in revenue and an earnings move of about US$1.3b from roughly US$862.0m today.
Uncover how Jabil's fair value indicates a 35% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Some of the lowest Jabil forecasts hinge on AI infrastructure demand cooling, which sharply contrasts with the pharma focused risk now in front of you. Those cautious analysts were penciling in about US$48.9b of revenue and US$2.0b in earnings by 2029. This FDA warning could push both bullish and bearish stories to evolve, so explore several viewpoints before deciding where you land.
Explore 2 other Jabil fair value estimates, including one that suggests it could be worth just $429.56!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Jabil research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Jabil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jabil's overall financial health at a glance.
Looking For More Investment Ideas Beyond Jabil?
Once you have a handle on how Jabil’s FDA warning fits into your overall thesis, it can help to widen the lens and compare it with other opportunities that score differently on quality, value and resilience. Use the Simply Wall St Screener to stress test your portfolio against a broad set of companies and avoid getting anchored to a single story.
- If you want potential mispricing alongside strong fundamentals, scan our curated 32 high quality undervalued stocks that meet strict quality and valuation filters.
- For investors who care most about balance sheet strength and financial resilience, focus on the list of solid balance sheet and fundamentals (23 results) and see which businesses carry less financial strain.
- Income focused readers can look toward cash flow support for payouts by checking the 6 dividend fortresses that offer 5%+ yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com