
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tsakos Energy Navigation (TEN) Looks Fully Valued After Strong Q2 Earnings
Tsakos Energy Navigation (NYSE:TEN) has drawn fresh attention after reporting second quarter 2026 net income of US$139.3 million, with basic earnings per share of US$4.40 from continuing operations.
The earnings release has arrived alongside a sharp move in Tsakos Energy Navigation's share price, with the stock up 7.13% on the day and a 30 day share price return of 15.56%, building on a powerful year to date gain of 118.82% and a 1 year total shareholder return of 129.45%. This points to momentum carrying over from longer term performance, including a 5 year total shareholder return of around 7x the starting level.
Scan beyond Tsakos Energy Navigation's surge to see which other shipping and energy names are flashing similar momentum and earnings strength inside our curated 32 high quality undervalued stocks
Tsakos Energy Navigation now couples a strong recent earnings story with a share price that has already run hard. The key issue for investors is whether that strength is already fully reflected in today’s valuation.
Most Popular Narrative: 4% Overvalued
Tsakos Energy Navigation last closed at $47.90, which sits a little above the most followed fair value estimate of $46.00, so the core debate is whether recent earnings power justifies that premium.
The company's significant investment in fleet modernization with a focus on eco friendly, dual fuel, and high specification vessels positions it to secure higher time charter rates from energy majors, control operating expenses, and meet upcoming environmental regulations. All of these factors are expected to improve net margins and earnings resilience. Prudent capital management highlighted by consistent debt reduction, sale of older vessels at premium prices, and reinvestment into modern ships strengthens the balance sheet, lowers interest expense, and enhances financial flexibility, supporting both future earnings and return on equity.
See why 11 investors see Tsakos Energy Navigation as 4% overvalued.
Result: Fair Value of $46 (OVERVALUED)
Still, Tsakos Energy Navigation leans heavily on fossil fuel transport and carries meaningful net debt, so weaker freight markets or tougher financing could quickly challenge the bullish story.
Find out about the key risks to this Tsakos Energy Navigation narrative.
Another View On Tsakos Energy Navigation’s Price Tag
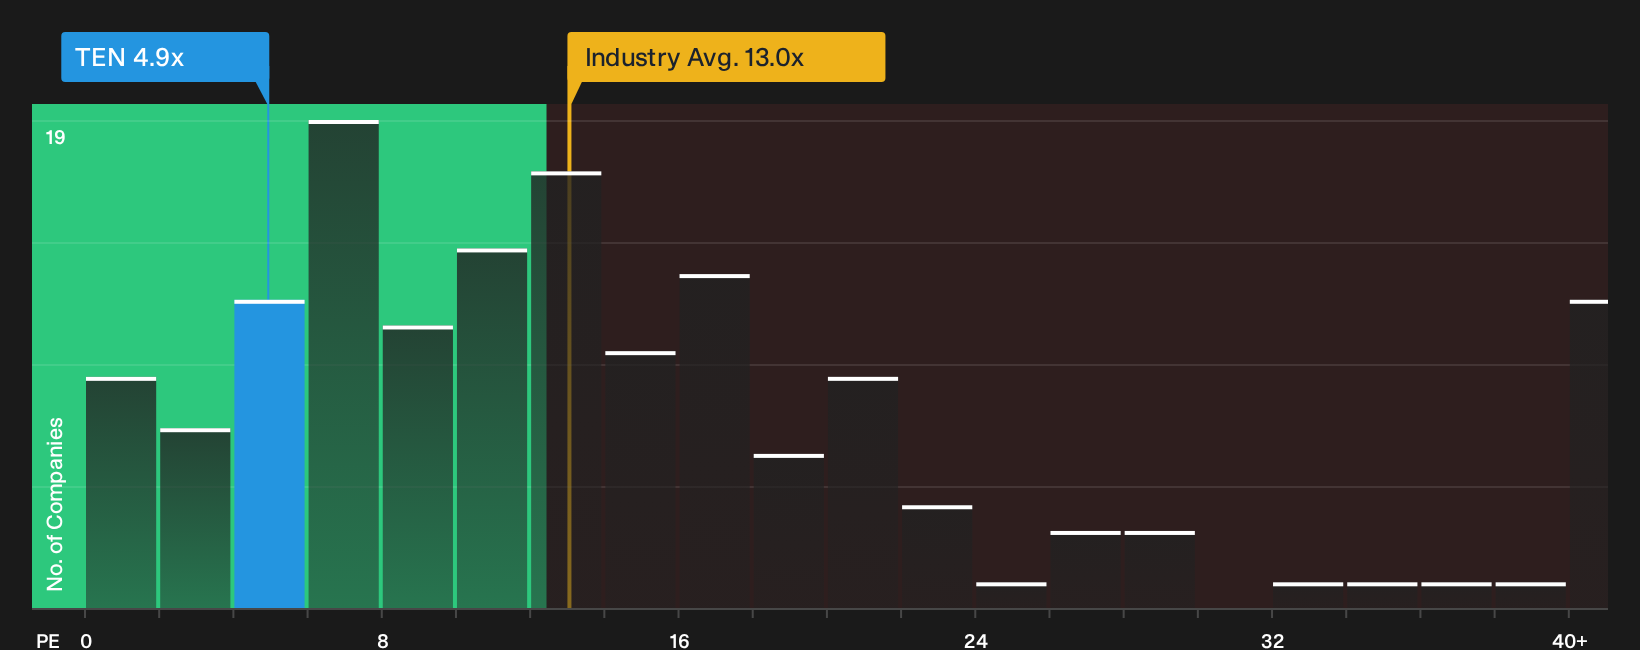
The most followed fair value for Tsakos Energy Navigation pegs the stock as slightly overvalued, yet the current P/E of 4.9x looks low against both peers at 17.1x and the US Oil and Gas industry at 13x. The fair ratio of 2.3x points the other way and suggests investors face real multiple risk if sentiment cools.
To see how that gap between current P/E, peers, and the fair ratio could narrow in either direction, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of enthusiasm and caution around Tsakos Energy Navigation? Treat this as your prompt to move fast, review the key figures, and weigh both the bright spots and the watchpoints through the 2 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Tsakos Energy Navigation?
If Tsakos Energy Navigation has sharpened your focus, do not stop here. Broaden your watchlist now and give yourself more quality options to compare.
- Target resilient income by checking companies that combine higher yields with balance sheet strength using the 6 dividend fortresses.
- Hunt for quality at a discount by scanning fundamentally strong businesses trading below their estimated worth through the 32 high quality undervalued stocks.
- Upgrade your opportunity set by reviewing a 15 high quality undiscovered gems before others start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com