
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lucid Group (LCID) Expands Into France, Is The Stock A Bargain?
Lucid Group (LCID) is entering the French electric vehicle market through an operational partnership with Emil Frey France, using the tie-up to support the launch of its Lucid Air and Lucid Gravity models.
For investors, that French expansion arrives after a tough stretch for Lucid Group’s stock, with the 30 day share price return down 32.15% and the year to date share price return down 62.15%, while the 1 year total shareholder return has declined 78.11%. This points to sentiment in which long term execution and recent executive changes, including the former CFO’s shift to a Senior Advisor role, are in sharp focus despite the latest growth initiatives.
Scan beyond Lucid Group and identify other electric vehicle and auto players that could be setting up for the next move with our hand picked list of solid balance sheet and fundamentals (23 results).
Lucid Group is working to build a premium EV brand, yet the share price has already absorbed heavy declines ahead of the French launch. Is the current valuation treating a developing business as a bargain or a warning sign?
Most Popular Narrative: 50% Undervalued
Lucid Group last closed at $4.22, while the most followed narrative pegs fair value at $8.40 using a 12.46% discount rate and long dated forecasts. That gap puts the focus squarely on whether Lucid can turn its technology story and partnerships into a sustainable business.
The upcoming launch of Lucid's midsized EV platform in late 2026 targets a much broader customer base with lower-cost, high-volume vehicles, directly expanding Lucid's addressable market and providing operating leverage for stronger top-line revenue growth and improved net margins as scale increases. Advancements in powertrain and battery technology, such as the in-house Atlas Drive Unit and extended-range battery packs, position Lucid as a technology leader, enhancing product differentiation and pricing power, which can drive higher gross margins and earnings through premium offerings.
See why 184 investors see Lucid Group as 50% undervalued.
Result: Fair Value of $8.40 (UNDERVALUED)
Still, heavy ongoing losses and reliance on fresh capital raises leave Lucid Group exposed if production ramps, cost controls, or Saudi plant timing turn out to be disappointing.
Find out about the key risks to this Lucid Group narrative.
Another View on Lucid Group’s Valuation
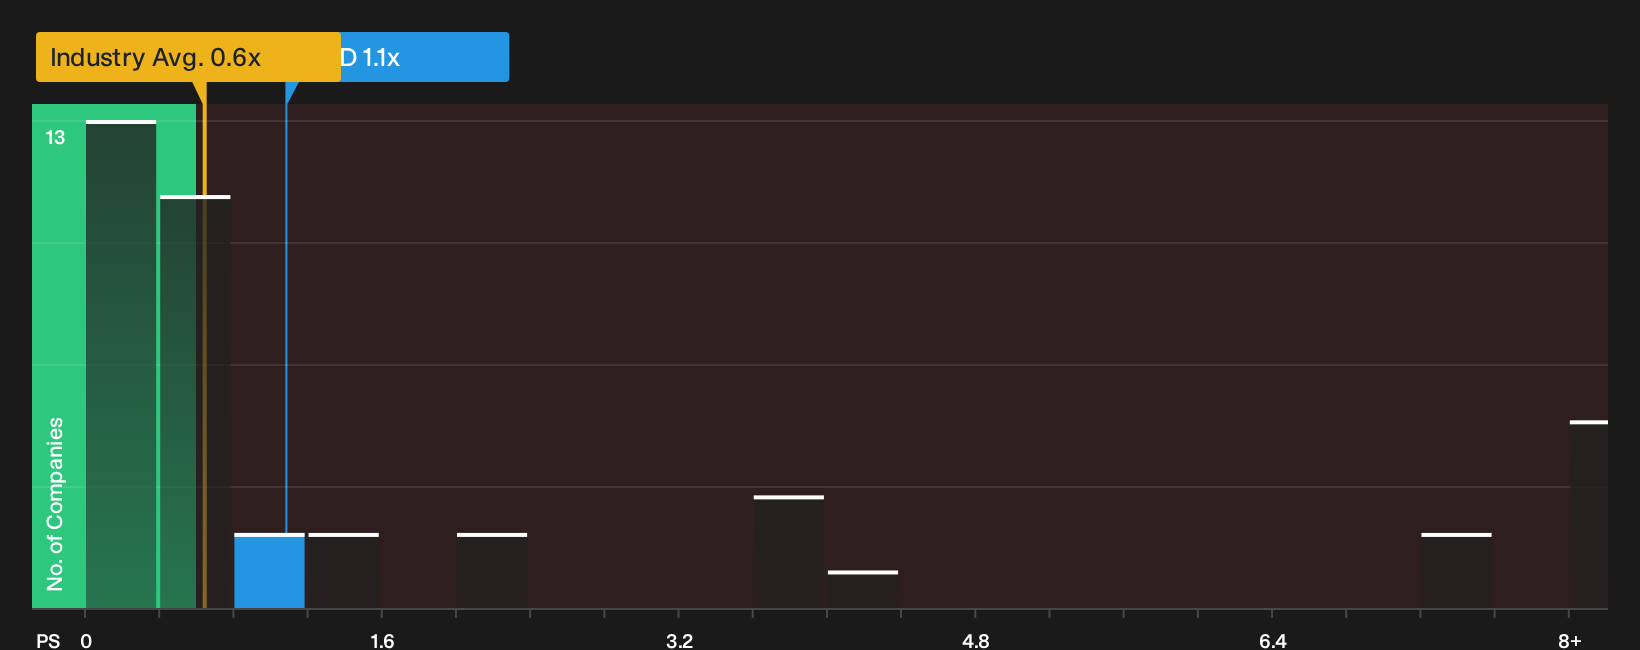
The fair value narrative around $8.40 leans heavily on long dated growth forecasts, yet the current price already reflects a P/S ratio of 1.1x. That is higher than both the US Auto industry at 0.6x and Lucid Group’s own fair ratio of 0x, which signals meaningful valuation risk if expectations reset.
For a second opinion on where that leaves the stock, it helps to look at what the numbers imply in a simpler ratio based framework, and then ask whether the story justifies paying almost double the industry multiple today or if patience is the better tool here.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Lucid Group can feel confusing, so move quickly from headlines to hard numbers and stress test the story yourself with 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Lucid Group?
Do not stop your research with Lucid Group. Use a focused stock screener to find other opportunities that may fit your goals and risk comfort.
- Target stability first and see which companies pass strict balance sheet and fundamentals checks with the list of solid balance sheet and fundamentals (23 results).
- Hunt for value by scanning for companies that combine quality metrics with pricing that looks potentially favorable using the 32 high quality undervalued stocks.
- Build a watchlist of potential future standouts by reviewing financially strong businesses that receive less attention through the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com