
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will iPhone 18 Deals Change T Mobile's Narrative For T Mobile Stock (TMUS)
- T-Mobile US recently outlined extensive promotions and flexible financing for Apple’s new iPhone 18 lineup, Apple Watch models and AirPods, while also stressing ongoing execution plans in 5G broadband, wireless services and future leadership succession.
- The launch of iPhone Handoff support and long-term wholesale expansion with Optimum highlight how T-Mobile is trying to deepen device usage and monetize its 5G network beyond traditional smartphone lines.
- We will now look at how T-Mobile US's richer iPhone offers and Handoff feature could influence the broader investment narrative.
T-Mobile US Investment Narrative Recap
To own T-Mobile US, you need to back a story of steady postpaid and broadband growth, heavier use of its 5G network and disciplined capital allocation, all while carrying a high debt load. The iPhone 18 promotions and Handoff feature feed directly into that thesis by pushing premium plans and broader device usage across the same subscriber.
The near term swing factor still sits in service revenue and churn. Aggressive iPhone discounts and extended 36 month financing might support customer additions, yet they can also pressure margins if competitive promos escalate. On balance, the recent device offers look incremental to the story rather than a fundamental shift.
The iPhone 18 launch package is the key disclosure here. It ties T-Mobile US’s premium plans, long duration equipment installment options and new Handoff capability into one push that leans on its 5G network and digital tools such as the T Life app. That aligns with management’s focus on higher postpaid ARPA and deeper ecosystem engagement.
For investors, the central issue is execution quality. Rich trade in credits, bundled Apple Watch deals, Handoff at US$5 per month and home internet plus AirPods offers can support customer growth and data usage. They also raise the bar on cost control and retention as peers respond with their own device heavy promotions over the coming quarters.
T-Mobile US' analyst narrative references revenues of US$104.8b and earnings of US$17.9b by 2029, which implies 4.4% yearly revenue growth and an earnings increase of about US$7.3b from current earnings of US$10.6b.
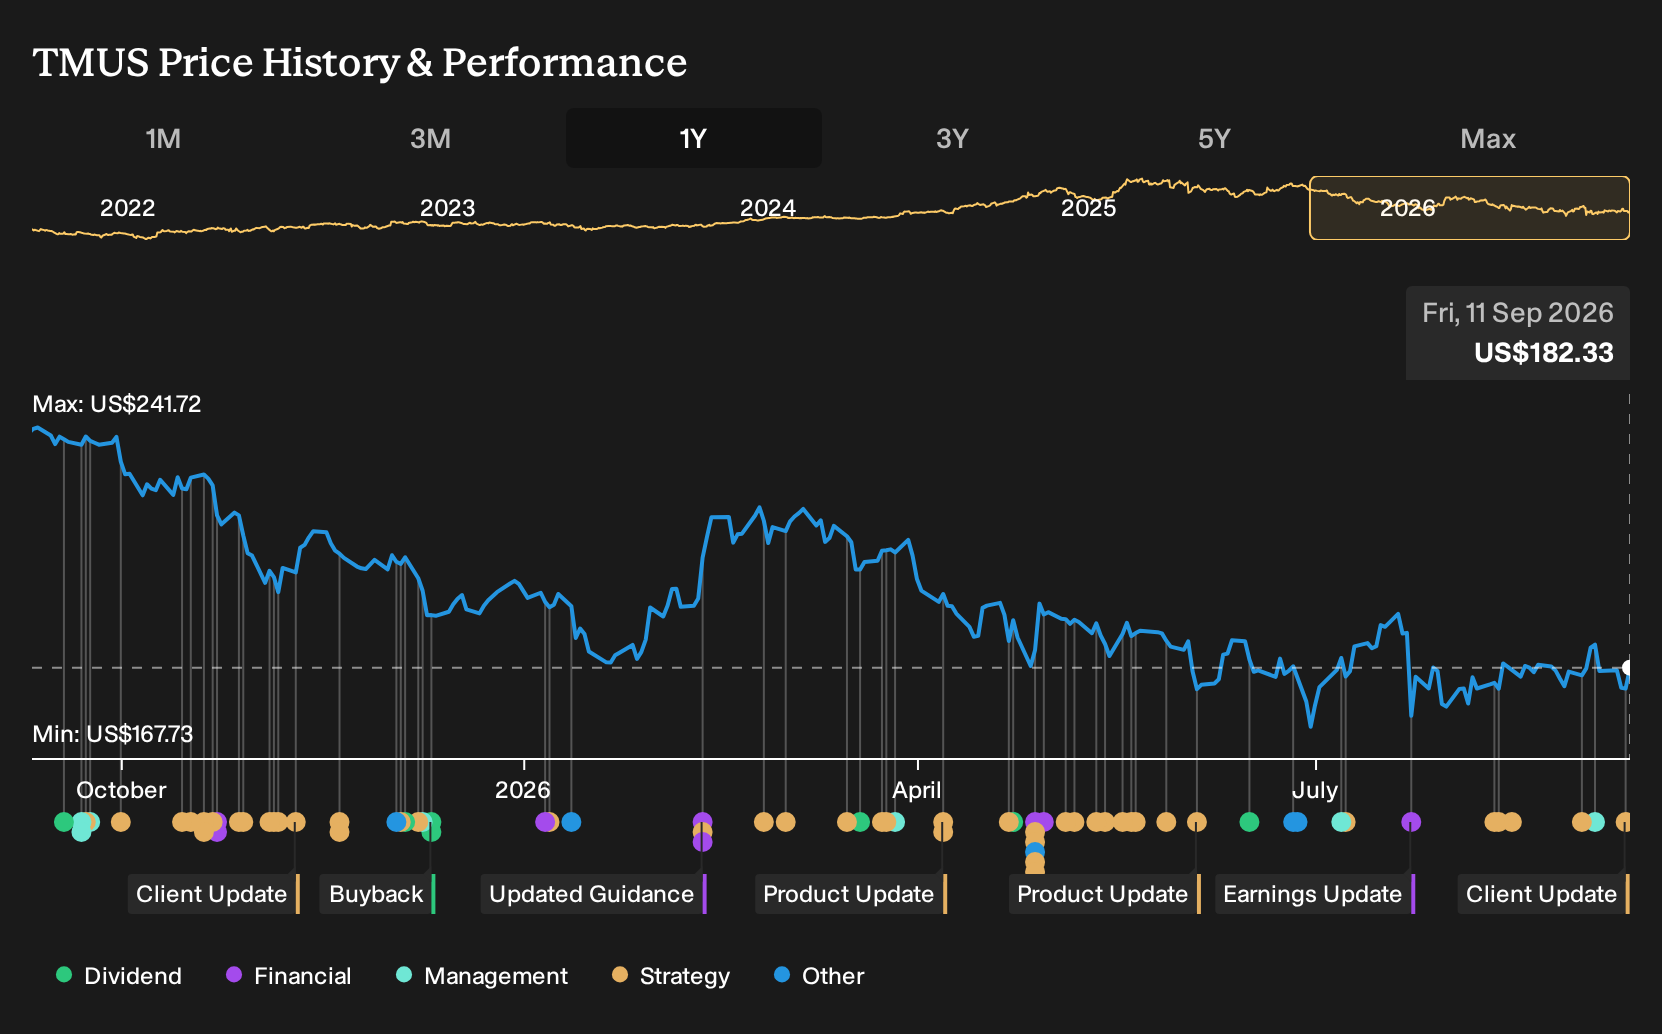
Uncover how T-Mobile US' fair value indicates a 33% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One bullish twist in the alternate T-Mobile US story is how strongly some analysts lean into earnings power. Before this iPhone 18 and Handoff news, the most optimistic forecasts already penciled in about US$106.4b of revenue and US$21.5b of earnings by 2029. That is far above the consensus US$17.9b path. It shows how wide opinion can run, and why it can help to compare several narratives and decide which assumptions feel realistic to you as this new device cycle filters into future estimates.
Explore 3 other T-Mobile US fair value estimates, including one that suggests as much as 222% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Exceptional investment results rarely come from following the herd, so go with your instincts.
- A great starting point for your T-Mobile US research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T-Mobile US. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T-Mobile US' overall financial health at a glance.
Looking for more investment ideas beyond T-Mobile US?
If the T-Mobile US story has sharpened your thinking about growth, risk and balance sheet strength, it can help to widen the lens and review other listed businesses through the same filters.
- For investors focused on stability first and returns second, a good next step is to review a 11 resilient stocks with low risk scores that score well on resilience factors.
- If income is a priority, consider using a screener that highlights 6 dividend fortresses that combine meaningful yields with underlying business strength.
- To hunt for opportunities that may not be widely followed yet, cast the net over a 15 high quality undiscovered gems and compare their fundamentals with what you see at T-Mobile US.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com