
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Franklin Electric (FELE) Could Be 17% Undervalued As Momentum Cools
Franklin Electric (FELE) has drawn fresh attention after its recent share performance. The price closed at US$97.83 and showed mixed returns over the past week, month, and past 3 months.
Over a longer window, Franklin Electric has delivered a 4.5% total shareholder return over the past year. The share price is roughly flat year to date and has recently eased over 30 and 90 days, which points to momentum that has cooled after earlier gains.
Scan beyond Franklin Electric's cooled momentum and evaluate other industrials with sturdy fundamentals by running your own screen with list of solid balance sheet and fundamentals (23 results).
Franklin Electric has cooled after a solid run, yet the current price still sits below some valuation markers and analyst targets. Is most of the easy upside gone? Or is the market still underpricing it?
Most Popular Narrative: 17% Undervalued
Franklin Electric last closed at $97.83, while the most followed valuation narrative pegs fair value around $118.50. This puts a clear gap between price and that fair value anchor in the current setup.
Ongoing modernization and digitalization of water infrastructure, such as adoption of smart monitoring technology (e.g., EVO ONE), together with increased presence in global growth markets, provide recurring and higher-margin revenue channels, boosting earnings durability and expanding long-term net margins.
See why 2 investors see Franklin Electric as 17% undervalued.
Result: Fair Value of $118.50 (UNDERVALUED)
Still, Franklin Electric's story can be knocked off course if cyclical end markets weaken, or if acquisitions keep pressure on margins instead of easing them.
Find out about the key risks to this Franklin Electric narrative.
Another View: Franklin Electric Looks Priced Rich On Earnings
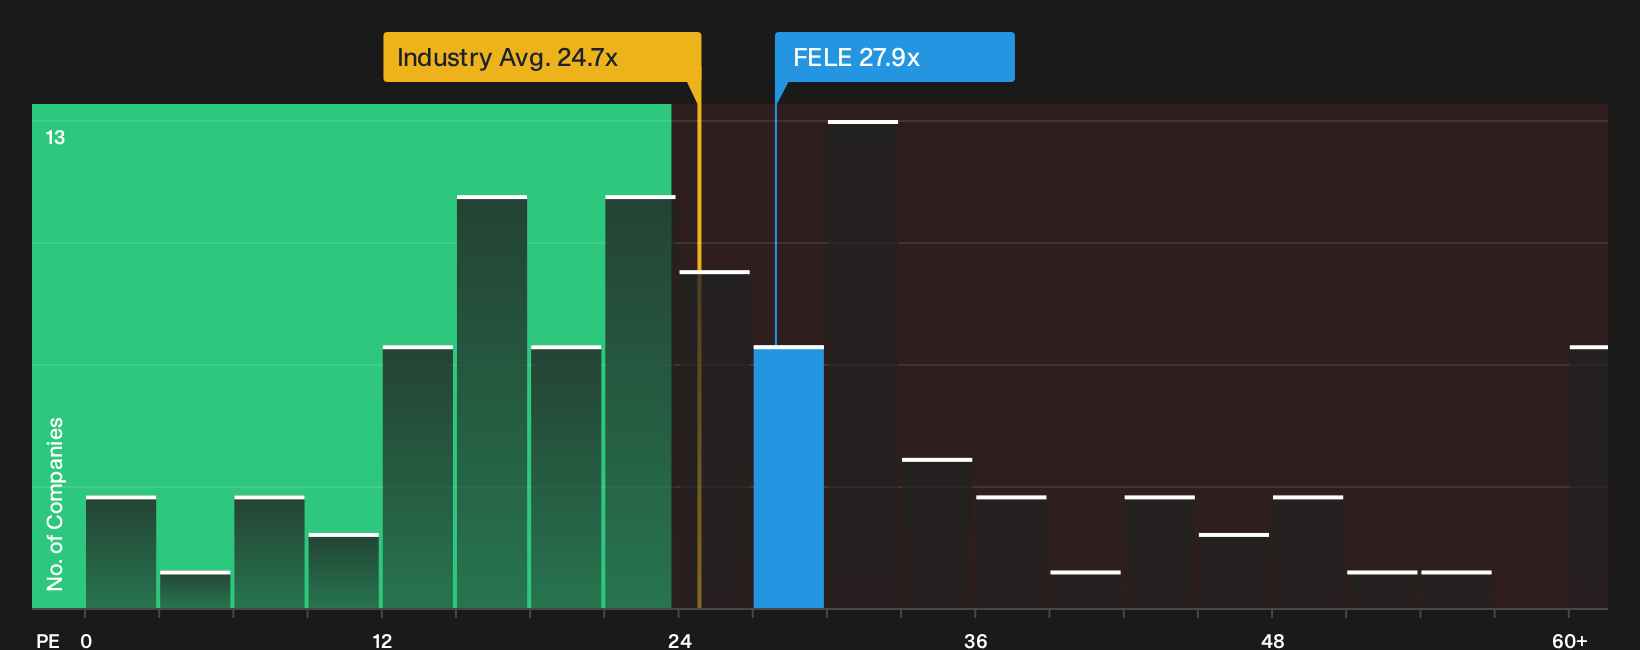
While Franklin Electric screens as undervalued on cash flow and fair value estimates, its current P/E of 27.9x tells a tougher story. That multiple sits above both the peer average of 22.9x and a fair ratio of 26.4x, which points to less margin for error if expectations shift.
Investors weighing Franklin Electric on this earnings multiple lens are effectively paying a premium against the Machinery industry and against where the fair ratio suggests the market could move to, so the question becomes whether that extra valuation risk feels worth it for the current growth profile.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Franklin Electric's valuation can make the picture feel noisy, so move quickly, review the full data, and weigh both sides through 3 key rewards and 1 important warning sign
Looking for more Franklin Electric sized ideas?
If Franklin Electric has you thinking bigger about your portfolio, do not stop here. Use fresh stock ideas to keep your watchlist working for you.
- Target steady compounding by reviewing companies that combine quality earnings with attractive prices through the 32 high quality undervalued stocks.
- Prioritize income potential by scanning for reliable high-yield payers using the 6 dividend fortresses.
- Dial down portfolio stress by hunting for financially resilient businesses in the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com