
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Be Sure To Check Out KRBL Limited (NSE:KRBL) Before It Goes Ex-Dividend
It looks like KRBL Limited (NSE:KRBL) is about to go ex-dividend in the next three days. The ex-dividend date is two business days before a company's record date in most cases, which is the date on which the company determines which shareholders are entitled to receive a dividend. The ex-dividend date is of consequence because whenever a stock is bought or sold, the trade can take two business days or more to settle. In other words, investors can purchase KRBL's shares before the 18th of September in order to be eligible for the dividend, which will be paid on the 24th of October.
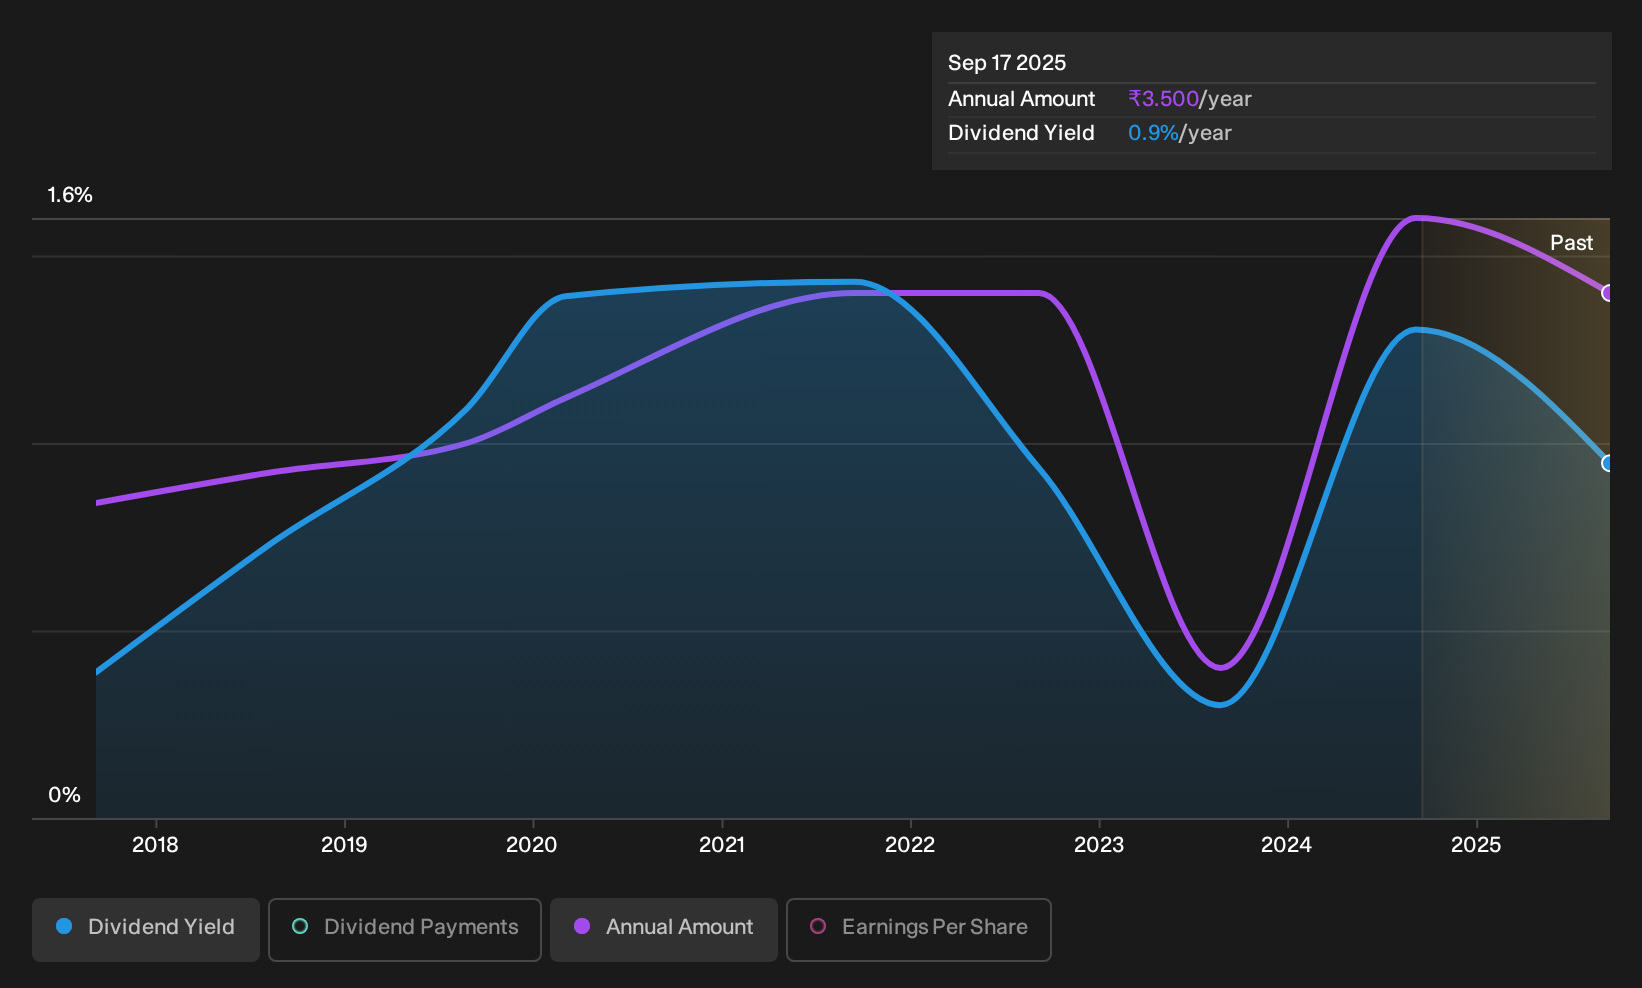
The company's upcoming dividend is ₹4.50 a share, following on from the last 12 months, when the company distributed a total of ₹4.50 per share to shareholders. Calculating the last year's worth of payments shows that KRBL has a trailing yield of 1.1% on the current share price of ₹421.05. Dividends are an important source of income to many shareholders, but the health of the business is crucial to maintaining those dividends. So we need to check whether the dividend payments are covered, and if earnings are growing.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable - hardly an ideal situation. KRBL paid out just 16% of its profit last year, which we think is conservatively low and leaves plenty of margin for unexpected circumstances. Yet cash flows are even more important than profits for assessing a dividend, so we need to see if the company generated enough cash to pay its distribution. What's good is that dividends were well covered by free cash flow, with the company paying out 9.3% of its cash flow last year.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
View our latest analysis for KRBL
Click here to see how much of its profit KRBL paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Companies with consistently growing earnings per share generally make the best dividend stocks, as they usually find it easier to grow dividends per share. Investors love dividends, so if earnings fall and the dividend is reduced, expect a stock to be sold off heavily at the same time. This is why it's a relief to see KRBL earnings per share are up 6.9% per annum over the last five years. Earnings per share have been growing at a decent rate, and the company is retaining more than three-quarters of its earnings in the business. If profits are reinvested effectively, this could be a bullish combination for future earnings and dividends.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. In the past 10 years, KRBL has increased its dividend at approximately 9.0% a year on average. It's encouraging to see the company lifting dividends while earnings are growing, suggesting at least some corporate interest in rewarding shareholders.
Final Takeaway
Is KRBL worth buying for its dividend? Earnings per share have been growing moderately, and KRBL is paying out less than half its earnings and cash flow as dividends, which is an attractive combination as it suggests the company is investing in growth. It might be nice to see earnings growing faster, but KRBL is being conservative with its dividend payouts and could still perform reasonably over the long run. KRBL looks solid on this analysis overall, and we'd definitely consider investigating it more closely.
With that in mind, a critical part of thorough stock research is being aware of any risks that stock currently faces. To help with this, we've discovered 1 warning sign for KRBL that you should be aware of before investing in their shares.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.