
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Labor Deal Require Action From First International Bank of Israel (TASE:FIBI) Investors?
- First International Bank of Israel reported that on 3 September 2026 it signed a memorandum of understanding with Matam Computer and Financial Operations, the Histadrut Maof and the Matam Employees' Committee, cancelling the previously declared labor dispute and returning employees to full work while negotiations on Matam's merger into the bank run through 31 October 2026.
- The end of the labor dispute at Matam removes an immediate operational overhang for First International Bank of Israel and sets a defined timetable to work through merger execution issues, including staffing, systems integration and ongoing cost responsibilities.
- Attention now turns to how First International Bank of Israel's investment narrative could be affected by the cleared labor dispute as merger talks progress.
What Is First International Bank of Israel's Investment Narrative?
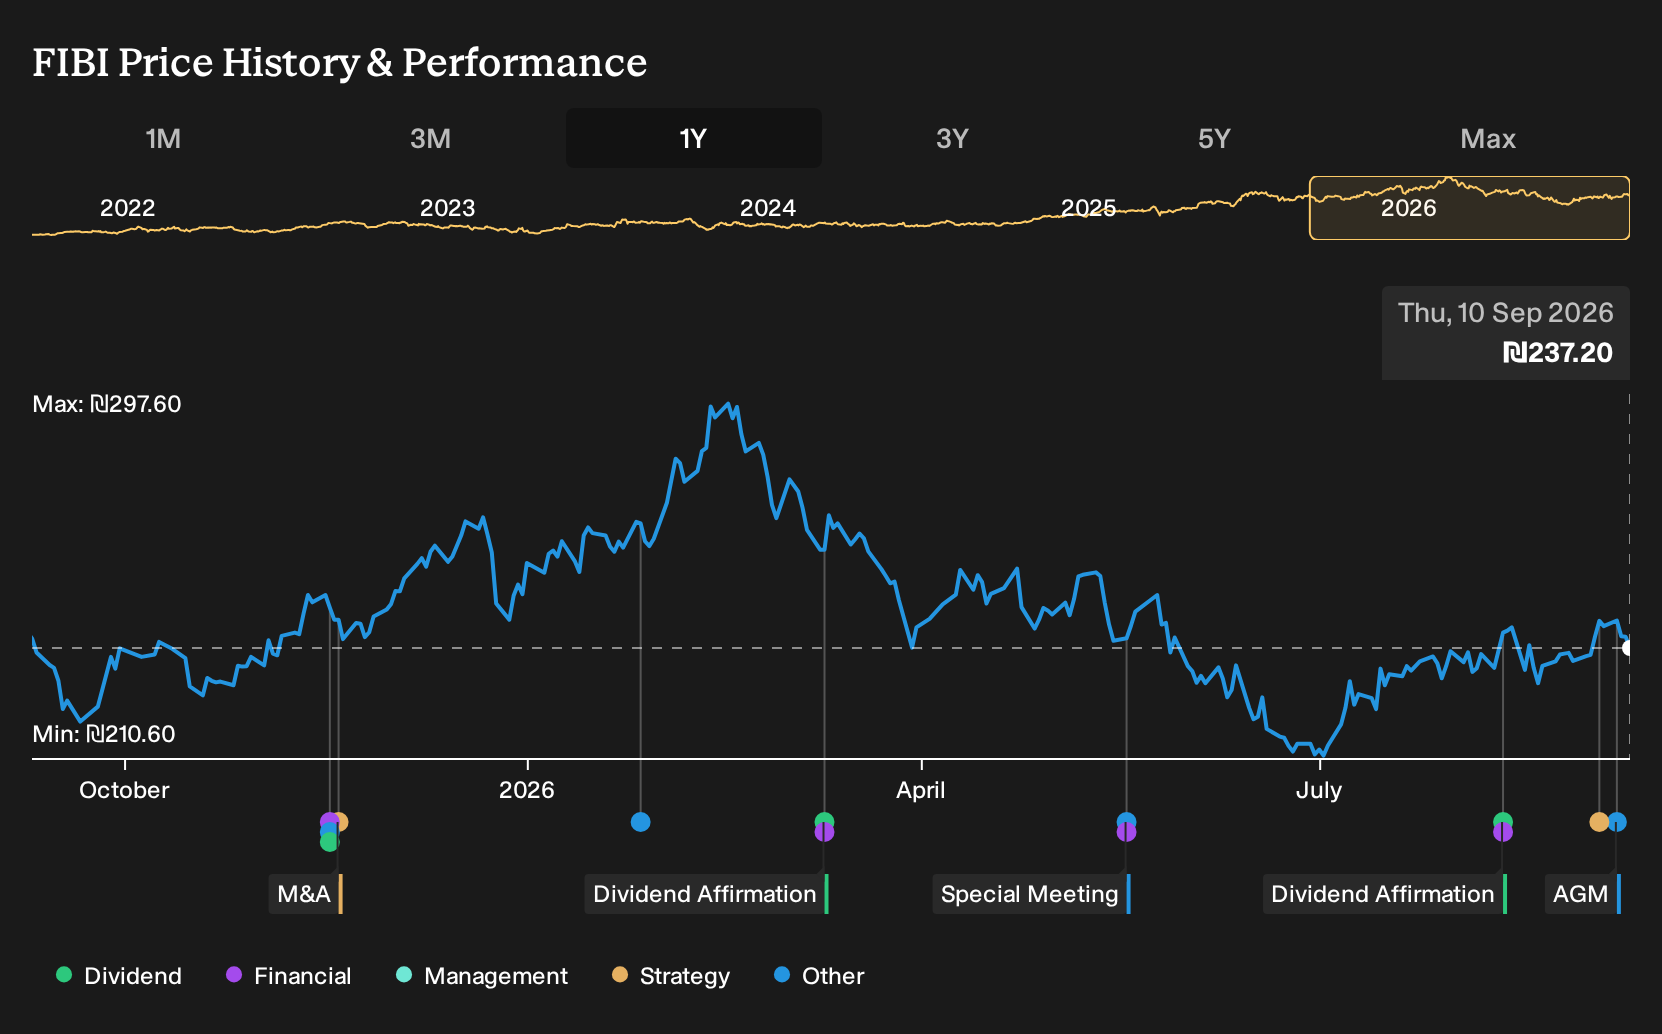
For anyone considering First International Bank of Israel, the basic belief is simple. You need to think this is a solid, fairly run lender that can keep turning a diversified domestic footprint into steady earnings, even if headline growth is not the main attraction. The share price is down about 8.1% year to date, despite a 3 year total return that is very large, and the stock trades around ₪237.2, which is about 16.8% below one estimate of fair value and on an 11x P/E that is slightly higher than Asian banks on average.
The fresh memorandum of understanding around the Matam merger matters because it takes immediate disruption risk off the table and lets management focus on execution. Information so far points to talks running through 31 October 2026, which keeps the spotlight on IT integration, ongoing cost allocation and any productivity gains from pulling Matam fully into the bank. In the short term, the key watchpoints remain profit margins, which recently eased from 33.7% to 31.6%, a Return on Equity of 14.5% that is described as low, plus an unstable dividend record that sits awkwardly next to an otherwise experienced board and management team.
Even so, there is one awkward aspect of the First International Bank of Israel story that only really shows up once you look at ...
There's only one way to know the right time to buy, sell or hold First International Bank of Israel. Head to Simply Wall St's company report for the latest analysis of First International Bank of Israel's Fair Value.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your First International Bank of Israel research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First International Bank of Israel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First International Bank of Israel's overall financial health at a glance.
Looking For More Investment Ideas Beyond First International Bank of Israel?
If you want to put this kind of thinking to work outside First International Bank of Israel, the Simply Wall St Screener can help you quickly filter for companies that fit the balance sheet strength, valuation and income profile you care about.
- If capital preservation comes first for you, start by checking companies that pass our resilience filters through the 100 resilient stocks with low risk scores.
- If you are hunting for quality at a reasonable price, broaden your watchlist with the 618 high quality undiscovered gems that combine solid fundamentals with relatively low attention.
- If you care most about dependable cash returns, focus your shortlist using the 161 dividend fortresses that meet a 5%+ yield hurdle with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com