- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CICC: Short-term crude oil premiums are more flexible, and the 4Q26 Brent oil price center was raised to 85 US dollars/barrel
The Zhitong Finance App learned that CICC released a research report saying that the Brent oil price fluctuation center has continued to rise since the third quarter, and the $90 per barrel quarterly center forecast in the bank's June mid-year outlook is being fulfilled. Recently, the geographical situation in the Middle East has once again escalated. Damage to Gulf oil exports has returned to more than 10 million b/day, Brent oil prices have exceeded 100 US dollars/barrel, and spot oil prices in the North Sea and Middle East are close to 120 US dollars/barrel. Global onshore oil reserves returned to the elimination channel in August/September, similar to the situation in April of this year. Considering that current oil inventory levels are lower than in the previous period, the bank suggests that short-term crude oil premiums are more flexible.
Looking ahead to the year, the bank believes that oil prices may have a “bottom of supply” below and a “peak in demand” above. On the one hand, the progress of the resumption of Middle Eastern crude oil production since the third quarter has fallen short of expectations. The recent escalation of the geographical situation will cause the market to reassess the sustainability of Middle Eastern crude oil supply losses and support the rise in the “supply bottom” of oil prices. On the other hand, endogenous demand is still weak. The recovery in summer demand should not be extrapolated linearly; a “peak in demand” may appear after oil prices break 100. Combining the above, the bank raised the 4Q26 Brent oil price forecast to 85 US dollars/barrel (June forecast was 80 US dollars/barrel) to reflect a more continuous supply gap and lower inventory levels.
In the refined oil market, short-term increases in oil prices and freight rates are impacting the gross profit of oil refining in Europe and Asia. In contrast, the cracking price gap of refined oil products such as gasoline is under high downward pressure. In contrast, the bank warned to focus on structural shortages and cracking price resilience in overseas diesel markets.
CICC's main views are as follows:
Geographic situation escalates, low inventory amplifies short-term risk premium flexibility
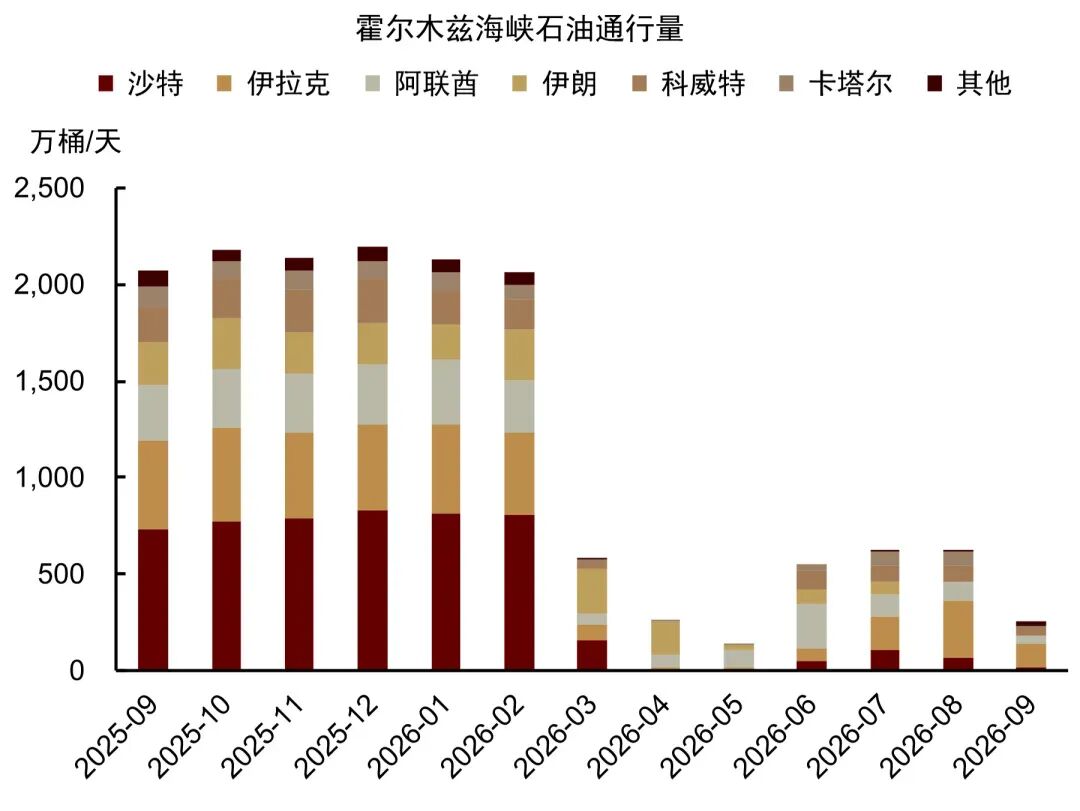
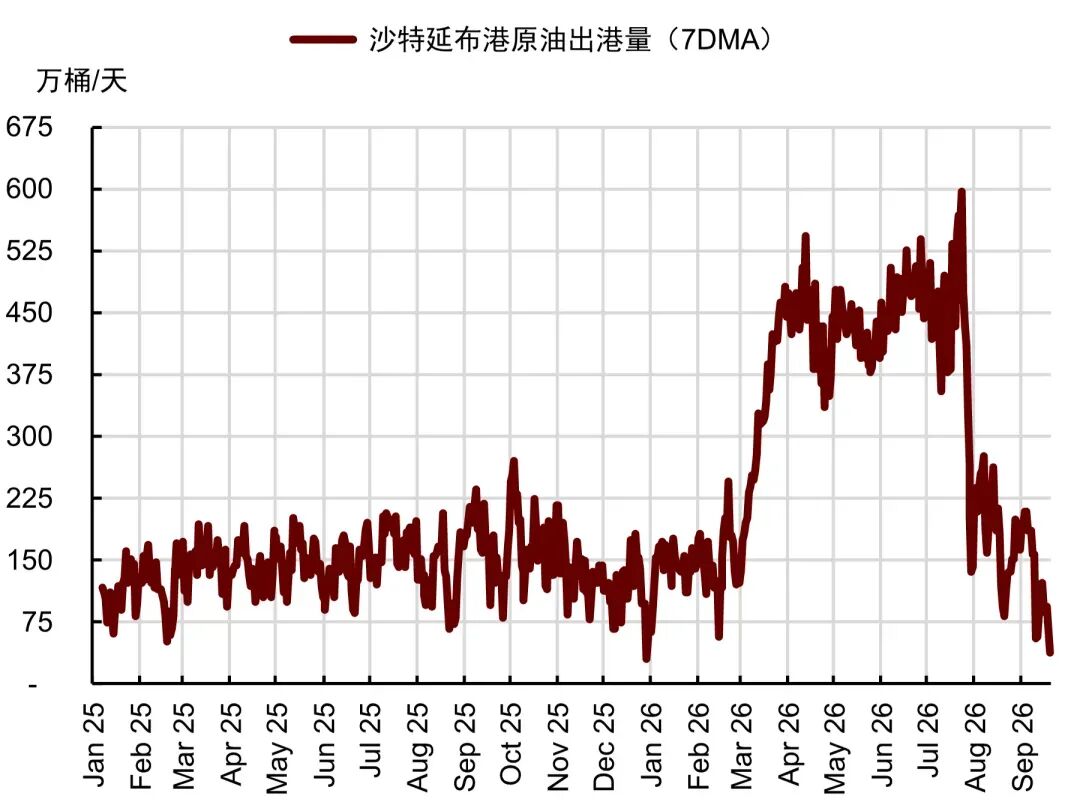
Since September, the situation in the Middle East has once again escalated, and damage to oil trade has worsened. On the one hand, the oil tanker attack between the US and Iran has increased the obstruction of passage through the Strait of Hormuz. According to Kpler, oil traffic in the strait has been reduced from 6-7 million b/d in July-August to 2 to 3 million b/d since September. Meanwhile, the conflict between the Houthis and Saudi Arabia is heating up. Following an impact on the passage of goods in the Mander Strait in August, many Saudi energy infrastructures have been attacked since this week. On September 11, the Saudi Ministry of Energy announced that due to multiple attacks on the East-West oil pipeline, the pipeline has been temporarily closed as a precautionary measure, but details of the damage and restoration plans were not disclosed. Since the Strait of Hormuz was blocked this year, Saudi Arabia has increased crude oil exports from 1.5 million b/d to 4.5 million b/d through the East-West oil pipeline and Yanbu port, making it one of the important crude oil transit routes in the Gulf region. The bank initially estimates that since September, the decline in Middle East oil exports from pre-conflict levels has once again expanded to more than 10 million b/day.
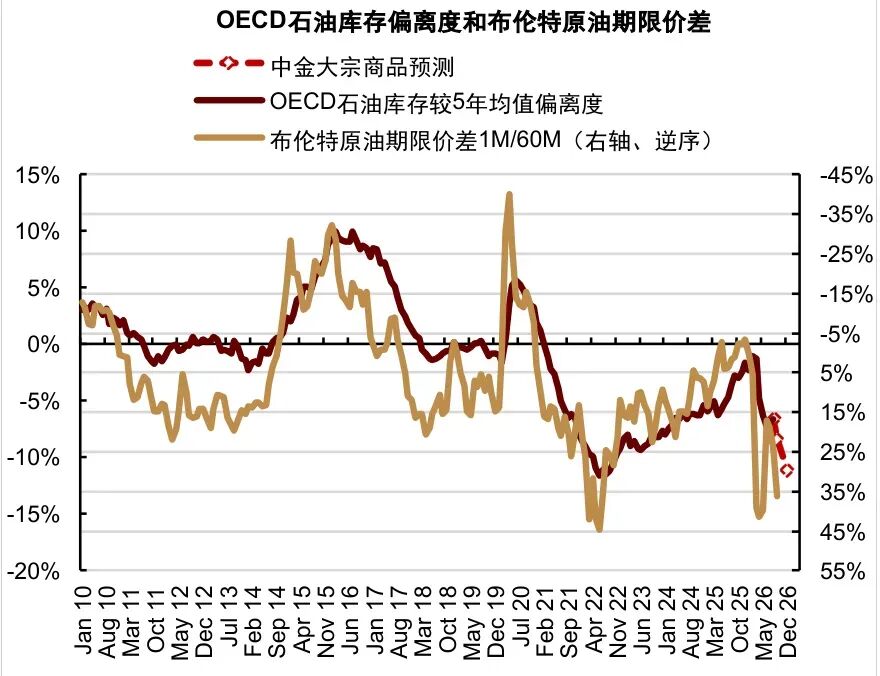
Driven by geopolitical sentiment, the price of Brent oil has surpassed 100 US dollars/barrel this week, and the premium in the spot market widened again, similar to the situation from late March to April. Currently, the spot price of North Sea crude oil and Oman crude oil is close to 120 US dollars/barrel. The premium of North Sea crude oil spot compared to Brent crude oil futures rose from almost zero at the beginning of the month to 13 US dollars/barrel, and there is still room for a high of 35 US dollars in early April. Global onshore oil stocks returned to the elimination channel in August. The bank expects the pressure to further increase onshore storage in September, similar to the situation in April this year. Looking at the short term, considering that the current oil inventory level is lower than in the previous period, the bank suggests that oil prices are more volatile and flexible.
The resumption of production in the Middle East is slow, and the “bottom supply” of oil prices may have risen
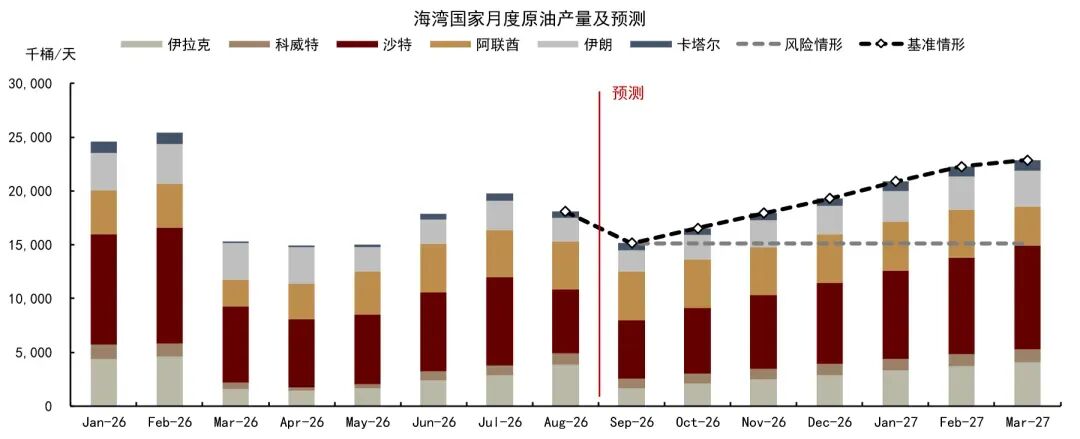
In addition to short-term trade disturbances and risk premium fluctuations, the bank believes that more importantly, the recent repeated geographical situation will cause the oil market to reassess the sustainability of Middle Eastern crude oil production losses, price the likely longer-term shortage pattern and lower inventory levels, and support the bottom rise in oil prices. Looking back at the end of the second quarter, with the conclusion of a cease-fire agreement between the US and Iran and the resumption of navigation in the straits, the market was optimistic about the resumption of crude oil production in the Middle East. However, in reality, due to repeated geographical situations, the resumption of production in July-August was slow. In August, crude oil production in the Gulf countries decreased by a cumulative total of about 7.34 million b/day compared to pre-conflict levels, and the loss ratio was still close to 30%. Also, on a month-on-month basis, Saudi crude oil production fell to 5.97 million b/day and Iran's crude oil production fell to 2.16 million b/day in August, all of which hit the lowest level since the US-Iran conflict this year. Considering another decline in oil exports in September, the bank lowered its forecast for the resumption of crude oil production in the Middle East. 4Q26 production may be 7-8 million b/d below pre-conflict levels, accounting for 7-8% of global supply. The process of resuming Middle Eastern crude oil production may have been extended to at least 1Q27. Under these circumstances, the bank believes that the “supply bottom” of Brent oil prices may have risen to 80 US dollars/barrel during the year.
Endogenous demand is weak, and the “peak of demand” will appear after oil prices break 100
There is a marginal recovery in oil demand in summer, but linear extrapolation is inappropriate. Global oil demand recovered month-on-month in July-August. In particular, in the Asian market, the operating rate of refineries in Japan and South Korea rebounded, India's consumption of refined oil products corrected year-on-year in July, and China's crude oil imports rebounded sequentially for 2 consecutive months, leading to an improvement in oil market demand expectations. However, as previously estimated by the bank, the supply shock dominates the rise in oil prices, which will inhibit demand, and after oil prices break 100, negative feedback on demand may gradually become the core driver of fundamental rebalancing. Recently, after oil prices broke 100, the bank has initially observed a decline in the price spread of refined oil products and high refining profits in the Singapore market. The recovery in demand over the past two months, which has benefited from easing supply pressure, may not be extrapolated linearly. Looking ahead, the bank believes that the “peak of demand” may appear after oil prices break 100, and that short-term geo-supply transactions may still be a pulse. In terms of price forecasts, the bank raised the 4Q26 Brent oil price forecast to 85 US dollars/barrel (June forecast was 80 US dollars/barrel) to reflect a more continuous supply gap and lower inventory levels. The OECD oil inventory at the end of the year is expected to be about 12% lower than the 5-year average.
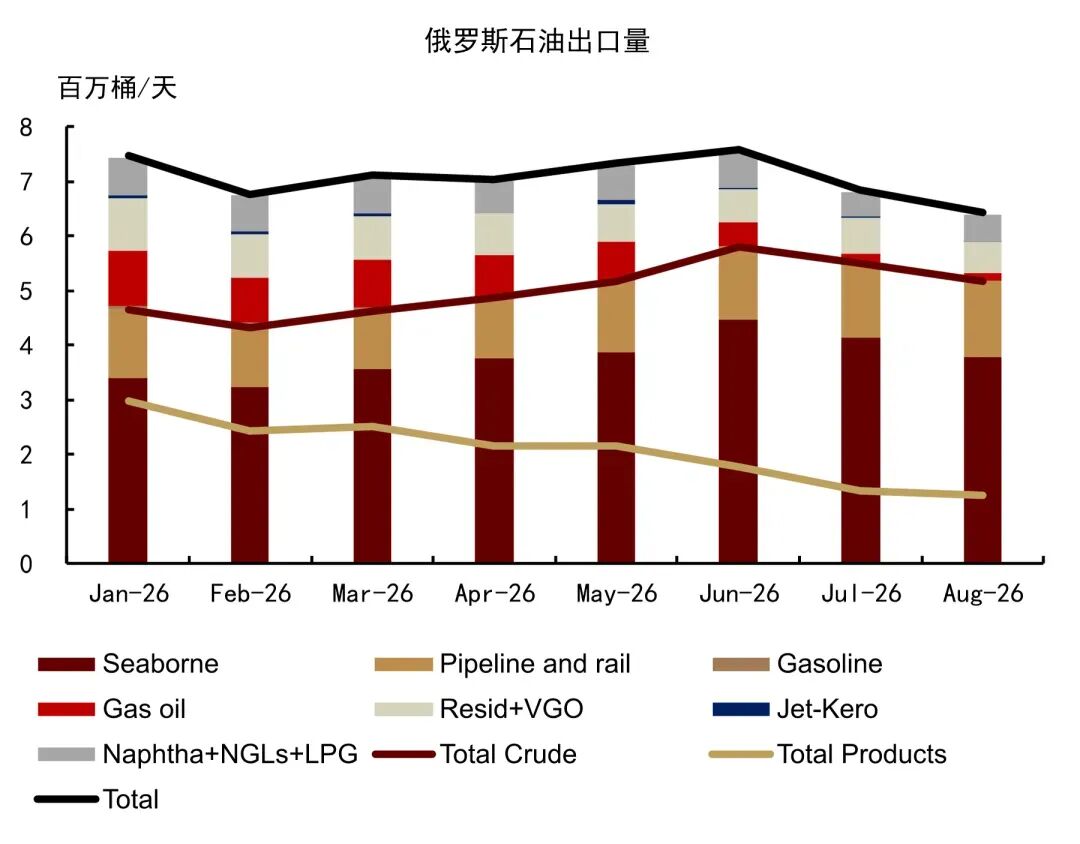
In the refined oil market, short-term increases in oil prices and freight rates are impacting gross refining margins in Eurasia. In contrast, the cracking price gap of refined oil products such as gasoline is under high downward pressure. In contrast, the bank warned to focus on structural shortages and cracking price resilience in the diesel market. The bank indicated the risk of rising overseas diesel prices in previous reports. Since August, diesel prices in Europe and the US have increased by about 40%. Currently, they have risen to around 200 US dollars/barrel, and the difference in diesel cracking prices has also risen to the highest level since the US-Iran conflict. In August, Russian diesel exports fell to 140,000 b/d, a decrease of 82% from the 2025 level, which means that global diesel exports fell by about 10%. At present, Russia has extended the ban on diesel exports until the end of September, and according to IEA statistics, the restoration of Russian refineries may take several months, and the amount of Russian crude oil processed during the year may continue to be about 30% lower than last year's level. The bank suggests that the diesel supply gap may continue during the year, and it may be difficult for overseas diesel cracking price differences to fall high.
Figure 1: Traffic volume in the Strait of Hormuz
Source: Kpler, CICC Research Division
Chart 2: Saudi Yanbu Port Crude Oil Handling Volume
 Source: Thomson Reuters, CICC Research Division
Chart 3: The process of resuming crude oil production in the Middle East may be further delayed
Source: Bloomberg News, IEA, CICC Research Division
Chart 4: Russian oil exports
 Source: IEA, CICC Research Division
Figure 5: OECD oil inventory path forecast