
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Impinj (PI) Could Be 2% Undervalued Following Its Convertible Note Exchange
Impinj (PI) has moved to restructure part of its balance sheet by entering privately negotiated deals to exchange about $56.3 million of 1.125% Convertible Senior Notes due 2027 for a combination of cash and new common shares.
Impinj shares have been firming up in recent months, with a 90 day share price return of 29.54% and a 3 year total shareholder return of 176.67%. This suggests the recent note exchange is being viewed as a meaningful balance sheet clean up rather than a source of new risk.
Scan how Impinj’s refinancing move compares with other chip and connectivity players by jumping into our hand picked 89 AI infrastructure stocks that are building the backbone for data heavy applications.
Impinj has just swapped most of its 2027 converts for cash and equity, which clears one question and raises another. Is today’s price already reflecting that change, or is it worth waiting patiently for a better entry as you weigh the valuation next?
Most Popular Narrative: 2.2% Undervalued
Impinj’s most followed narrative pegs fair value at about $180.89, only slightly above the recent $176.82 close. That keeps the focus squarely on what is driving that estimate.
M800 and Gen2X platform enhancements, including improved readability, faster inventory counting, and unique enterprise use cases (like loss analytics), are driving higher gross margin product mix and expanding the company's addressable market by enabling new categories such as food, high-value apparel, and hard-to-read items. Sustained adoption of these products bolsters future gross margins and earnings.
Want to understand why this Impinj story leans so heavily on richer margins, faster top line expansion, and a punchy future earnings profile? The full narrative lays out how those moving parts intersect with a higher implied profit base, a premium multiple on future earnings, and a path to stronger returns that is far from guaranteed.
Result: Fair Value of $180.89 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Impinj’s reliance on a handful of major customers, along with the risk that newer pilots in areas like food move slowly, could easily unsettle that margin driven story.
Find out about the key risks to this Impinj narrative.
Another View On Impinj’s Valuation
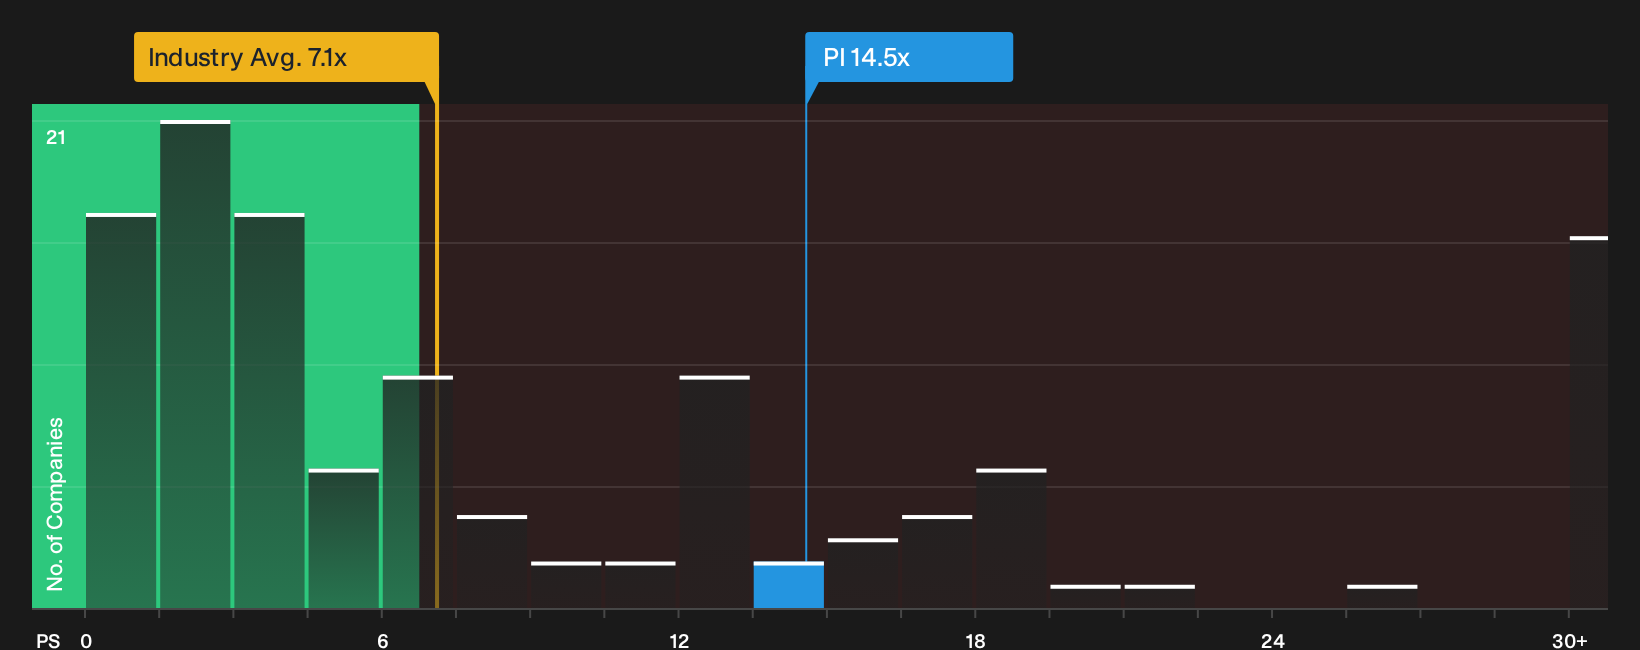
The first narrative leans on earnings forecasts and a fair value near $180.89. A simple revenue multiple points in a very different direction. Impinj trades on a P/S of 14.5x, while the US Semiconductor industry sits at 7.1x and peers around 3.8x, with a fair ratio of 6x.
That gap suggests investors are paying a heavy premium today, which could shrink if expectations cool or expand if the story plays out more strongly than the crowd assumes.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Impinj story looks optimistic, so move fast to test the numbers yourself and stress test the assumptions that matter most. Then weigh those bright spots against the fine print by reviewing the 1 key reward.
Looking for more Impinj investment ideas?
If Impinj has sharpened your interest, do not stop here. Use the Simply Wall Street screener to surface fresh opportunities before they move without you.
- Target value hunting by scanning a curated 32 high quality undervalued stocks that pairs robust fundamentals with pricing that some investors may have overlooked.
- Build a sturdier core by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you focus on financially resilient businesses.
- Spot tomorrow’s potential leaders early by checking a 15 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com