
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sony (TSE:6758) Stock Looks Cheap As 5 Year Return Hits 60%
Sony Group stock has pulled back over the past year, yet the current market price still sits well below what a Discounted Cash Flow (DCF) intrinsic value estimate suggests. This puts fresh attention on whether the recent slump has gone too far. The share price has delivered a 5 year return that is solid in absolute terms, while multiple valuation checks now lean toward the shares trading on the cheap side.
- Over 5 years, Sony Group has returned 59.7%, which points to meaningful long term wealth creation even after the recent setback.
- The expanded Sony partnership with the NFL can support future cash generation, while legal disputes around digital content and AI training may weigh on how investors price that cash flow.
- Sony Group screens as undervalued in the broader checks, with a value score of 5 and both the Discounted Cash Flow (DCF) intrinsic value estimate and earnings based multiples indicating the shares trade at a discount.
The issue now is whether Sony Group’s current discount to intrinsic value leaves enough room for investors to be compensated for the legal and business risks that come with the story.
Spot undervalued opportunities like Sony Group by scanning our hand-picked list of 16 high quality undervalued stocks, which pairs strong fundamentals with discounted prices.Is Sony Group Still Cheap on Cash Flow?
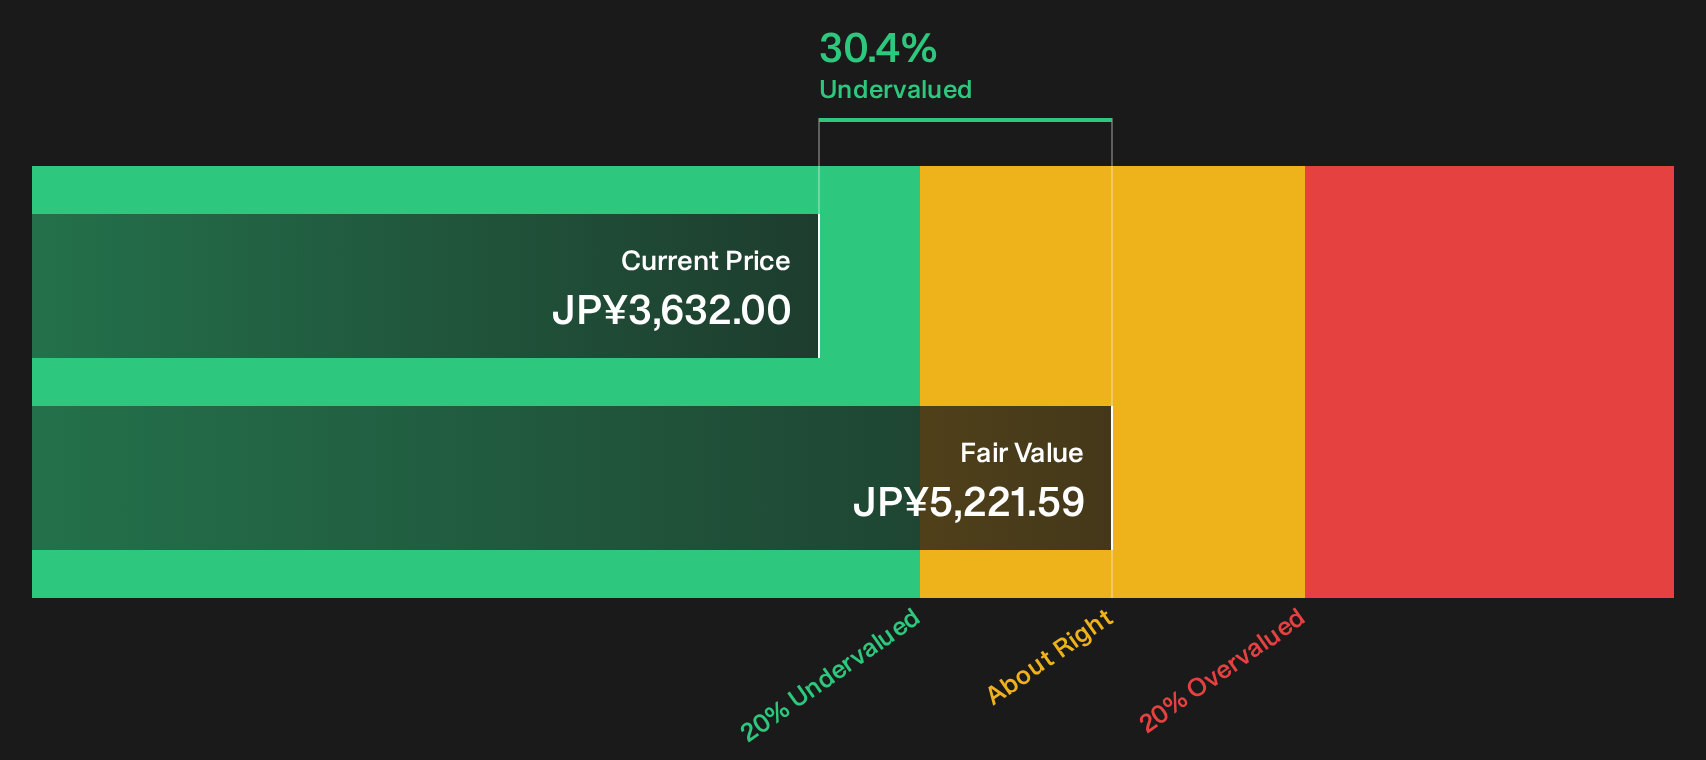
The Discounted Cash Flow (DCF) model looks at what Sony Group’s future cash generation could be worth in today’s money. On this view, the group is working from a latest twelve month free cash flow base of roughly ¥1.49b, with projections assuming that cash flow keeps growing rather than shrinking. Rolling those estimates forward and discounting them back, the DCF model points to an intrinsic value of about ¥5,222 per share.
That figure implies the stock trades at roughly a 30.4% discount to the cash flow based estimate, which presents Sony Group as undervalued on this measure. The lawsuit over digital game ownership helps explain why the price may lag the model, since it adds legal uncertainty around a profitable piece of the PlayStation ecosystem even as the cash generation assumptions remain intact.
On the DCF numbers presented, Sony Group stock currently appears undervalued relative to its estimated intrinsic value.
Our Discounted Cash Flow (DCF) analysis suggests Sony Group is undervalued by 30.4%. Track this in your watchlist or portfolio, or discover 16 more high quality undervalued stocks.
Does Sony Group Look Undervalued on Earnings?
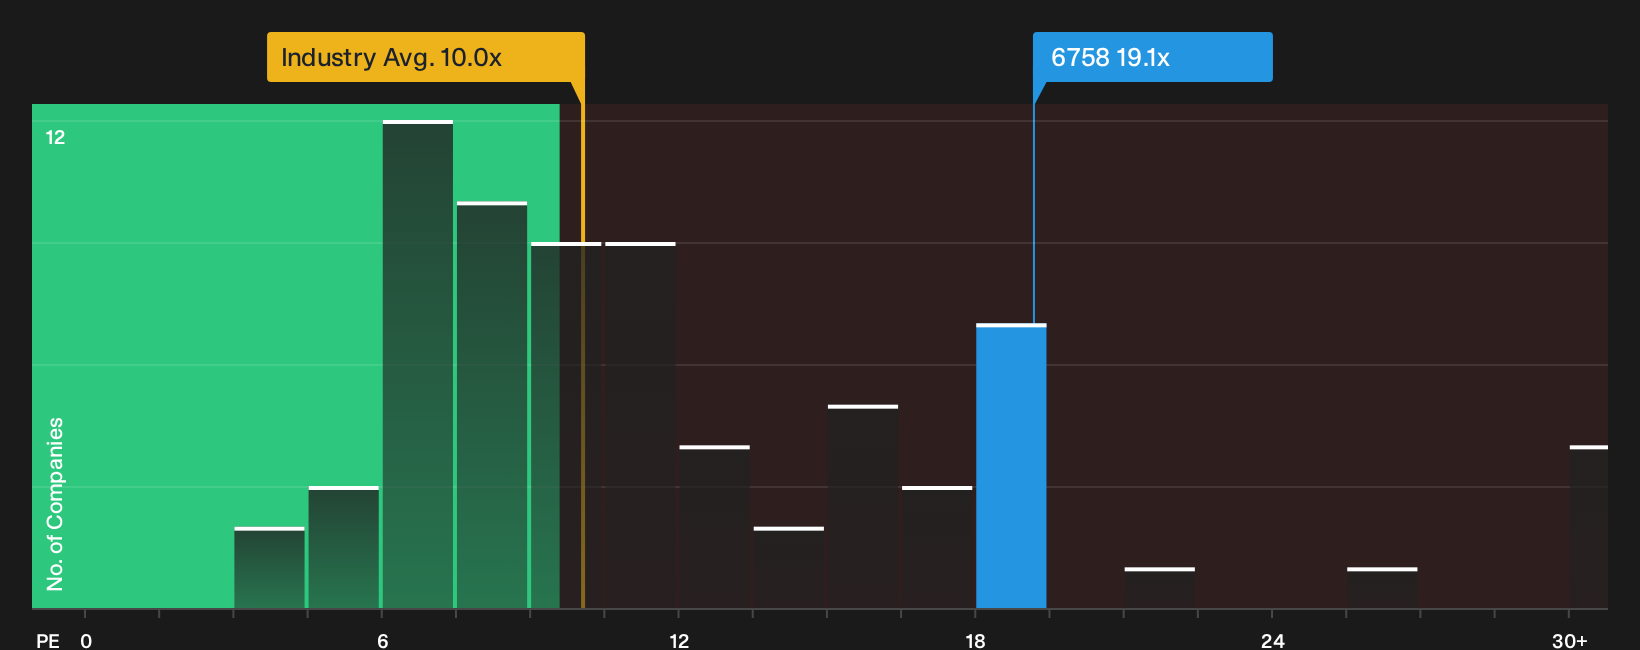
P/E is a useful lens for Sony Group because earnings remain a key reference point for how investors judge its mix of hardware, content, and services. On this metric, the stock trades on about 19.1x earnings, which is below both the broader Consumer Durables industry average of roughly 10.0x and the closer peer group average of 23.9x.
The tailored fair P/E ratio for Sony Group is estimated at 26.0x, which is higher than the current 19.1x level. That gap suggests the market is pricing in a margin of safety relative to what this model implies for the business given its scale and risk profile. The legal disputes around digital content and AI training help explain some caution, yet the multiple still appears lower than this fair value yardstick.
On the P/E numbers alone, Sony Group stock appears undervalued compared with the multiple that the fair ratio model implies.
See what the numbers say about this price — find out in our valuation breakdown.
The Sony Group Narrative: What Would Justify Today's Price?
Sony Group’s valuation gap raises a simple question for you as a shareholder. What mix of growth, margins, and earnings outcomes would need to play out for the stock to be worth materially more or materially less than where it trades today? Narratives on Simply Wall St’s Community page aim to spell out those future paths and treat each implied fair value as a thesis about Sony Group’s business that can be tracked over time rather than just a one off snapshot.
Community views on Sony Group pull in opposite directions, with one camp focused on the content and AI upside and the other on console cycle and sensor risks.
Bull case: 25% undervalued
"Ongoing expansion and robust engagement in Sony's PlayStation ecosystem, including increased monthly active users and growth in network service revenue, indicate a shift toward more stable, high-margin, recurring digital income streams..."
Read the full Bull Case to see why Sony Group could be undervalued
Bear case: roughly fairly valued
"Although the PlayStation 5 ecosystem now reaches a large installed base of more than 92 million units and software and network services are already a major contributor, the later stage of the console cycle means hardware sales are moderating..."
Read the full Bear Case to see why Sony Group could be overvalued
Do you think there's more to the story for Sony Group? Head over to our Community to see what others are saying!
The Bottom Line
Sony Group screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and its current earnings multiple, so the market is already building in a cushion. The key question is whether that discount compensates for the legal and business uncertainties around digital content and AI training. For you as a shareholder, the crux is simple. Either the cash generation and earnings profile prove resilient enough for that valuation gap to narrow, or the ongoing disputes and console cycle risks show that the current markdown is justified and the stock stays cheap for a reason.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com