
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rollins (ROL) Slides Into A Valuation Debate, Is It Undervalued Or Overvalued?
Rollins (ROL) has drawn fresh attention after recent share performance, with the pest control specialist now trading at US$34.73. Investors are reassessing the stock as multi-year returns remain relatively muted.
Recent trading tells a different story, with Rollins posting a 1-day share price return of 0.49% after a much steeper 90-day share price decline of 25.95% and a 1-year total shareholder return that is down 38.59%. This signals fading momentum despite a largely flat total shareholder return over five years.
Stress test your expectations for Rollins against a hand picked set of resilient compounding stories by scanning the 11 resilient stocks with low risk scores alongside this recent share price reset.
Rollins now trades well below both analyst targets and one estimate of intrinsic value after that sharp slide. Is this a discounted compounding story, or a market warning that the valuation still needs work?
Most Popular Narrative: 114.4% Overvalued
Against Rollins' last close at $34.73, the most followed narrative points to a fair value of $16.20, which implies a materially richer market price than that framework supports.
Rollins is the dominant pure-play compounder in global pest control, a structurally necessary, recession-resistant service business that has grown revenue for 24 consecutive years and delivered ROIC of 23 to 31% for 12 consecutive years, without a single year of ROIC below 21% even through COVID-19. The investment thesis rests on three mutually reinforcing pillars: (1) a Wide Moat rooted in switching costs, as commercial customers cannot switch providers without triggering compliance risk, and residential customers renew habitually at annual price increases of 3 to 4% above CPI without meaningful churn; (2) a proven M&A flywheel that converts a fragmented industry of 34,000+ U.S. operators into compounding route density and FCF, completing 30 to 45 bolt-on acquisitions annually at disciplined multiples with zero reported impairments; and (3) a capital-light business model with minimal reinvestment needs, generating FCF of $678M in FY2025 on $3.76B of revenue. Under the Neutral scenario, Rollins compounds revenue at 8.2% over 10 years and FCF from $678M to $1.56B, anchored by management's own organic growth guidance of 7 to 8% and a structural tailwind from climate-driven pest season extension in its core Sun Belt markets. At a 30% Margin of Safety and a 22× FCF exit multiple, the setup offers a durable, high-conviction entry into a business that is difficult to compete against, impossible to disrupt digitally in its core commercial segment, and biologically guaranteed in its demand.
Curious how that compounding story still lands on a fair value that sits well below today’s share price. The answer sits in the growth glidepath, the margin assumptions, and the exit multiple this narrative leans on.
Result: Fair Value of $16.20 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Rollins story could be knocked off course if acquisition returns disappoint or if pricing power weakens and erodes those high embedded expectations.
Find out about the key risks to this Rollins narrative.
Another View On Rollins' Value
A very different picture comes from our DCF model. On that framework, Rollins at $34.73 screens as undervalued compared with an estimated future cash flow value of $59.13. These are two different methods that produce two different outcomes. Which set of assumptions feels more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
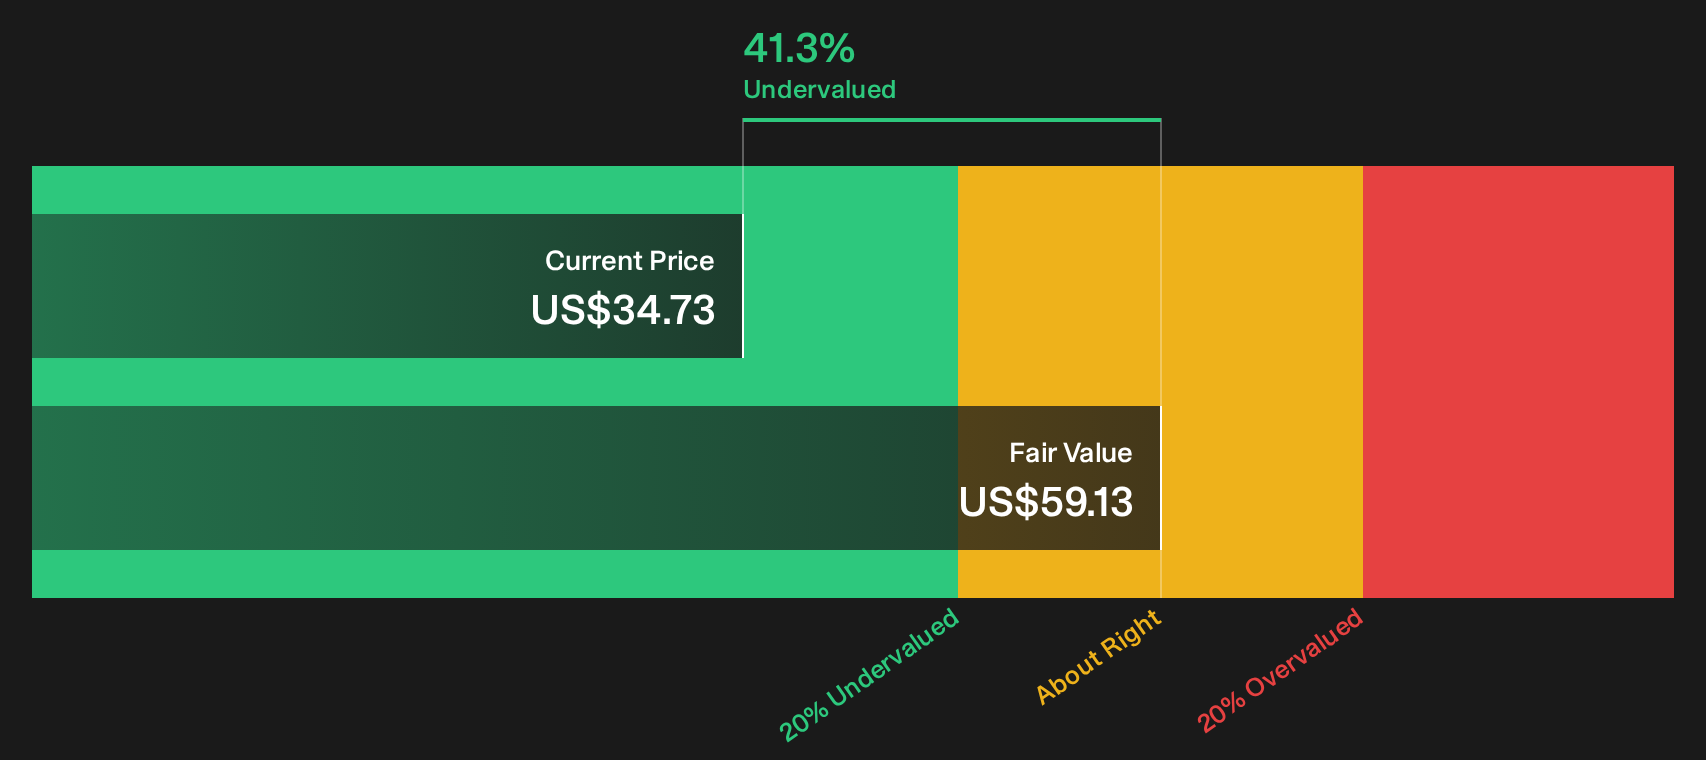
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rollins for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across Rollins can feel confusing, so move quickly from headline impressions to hard numbers and form your own judgment with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Rollins?
If Rollins has sharpened your focus on quality and price, do not stop here. Broaden your watchlist with curated ideas built from hard data, not hype.
- Target resilient cash generators that combine strong fundamentals with balance sheet strength using the list of solid balance sheet and fundamentals (23 results).
- Spot potential mispricings where quality meets attractive entry points by scanning the 32 high quality undervalued stocks.
- Research dependable income streams by reviewing the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com