
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
USA Compression Partners (USAC) On Its $600 Million Notes Deal And Valuation Question
USA Compression Partners (USAC) has moved into the spotlight after lining up a $600 million senior unsecured notes offering due 2035 and preparing to shift its listing from the NYSE to the Texas Stock Exchange.
The latest $600 million notes issuance and the upcoming move to the Texas Stock Exchange arrive after a steady run, with USA Compression Partners’ share price at $27.64 and a year to date share price return of 16.18%, while the 1 year total shareholder return of 24.52% and 5 year total shareholder return of 187.07% point to momentum that investors will be weighing against the new debt load and listing shift.
Spot fresh income and infrastructure plays with a similar capital structure story by scanning our hand picked 6 dividend fortresses alongside USA Compression Partners.Fresh debt on the books, a new exchange listing on the horizon, and USA Compression Partners trading near analysts’ price target at $27.64 raise a key question: Is this the moment to commit, or does waiting for a cheaper entry make more sense as the valuation picture unfolds next?
Most Popular Narrative: 6.8% Undervalued
USA Compression Partners is trading at $27.64 against a narrative fair value of about $29.67, so the current unit price sits modestly below that modeled estimate based on a discount rate of 8.41%.
High contract renewal rates and a shift toward longer-term agreements, particularly in high-growth Northeast and dry gas basins, are reducing revenue volatility and underpinning stable distributable cash flow and earnings visibility.
Read the complete narrative. Read the complete narrative.
Want to see what sits behind that fair value gap? The narrative leans heavily on tighter compression capacity, thicker margins, and a profit trajectory that assumes the current contract strength endures. Curious which revenue and earnings paths are baked into those assumptions, and how rich a multiple they imply by the late 2020s? The full narrative lays out that playbook in detail.
Result: Fair Value of $29.67 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, USA Compression Partners faces pressure points, including reliance on a small group of large customers and higher capital and operating costs that could strain future cash generation.
Find out about the key risks to this USA Compression Partners narrative.
Another View: USA Compression Partners Through a P/E Lens
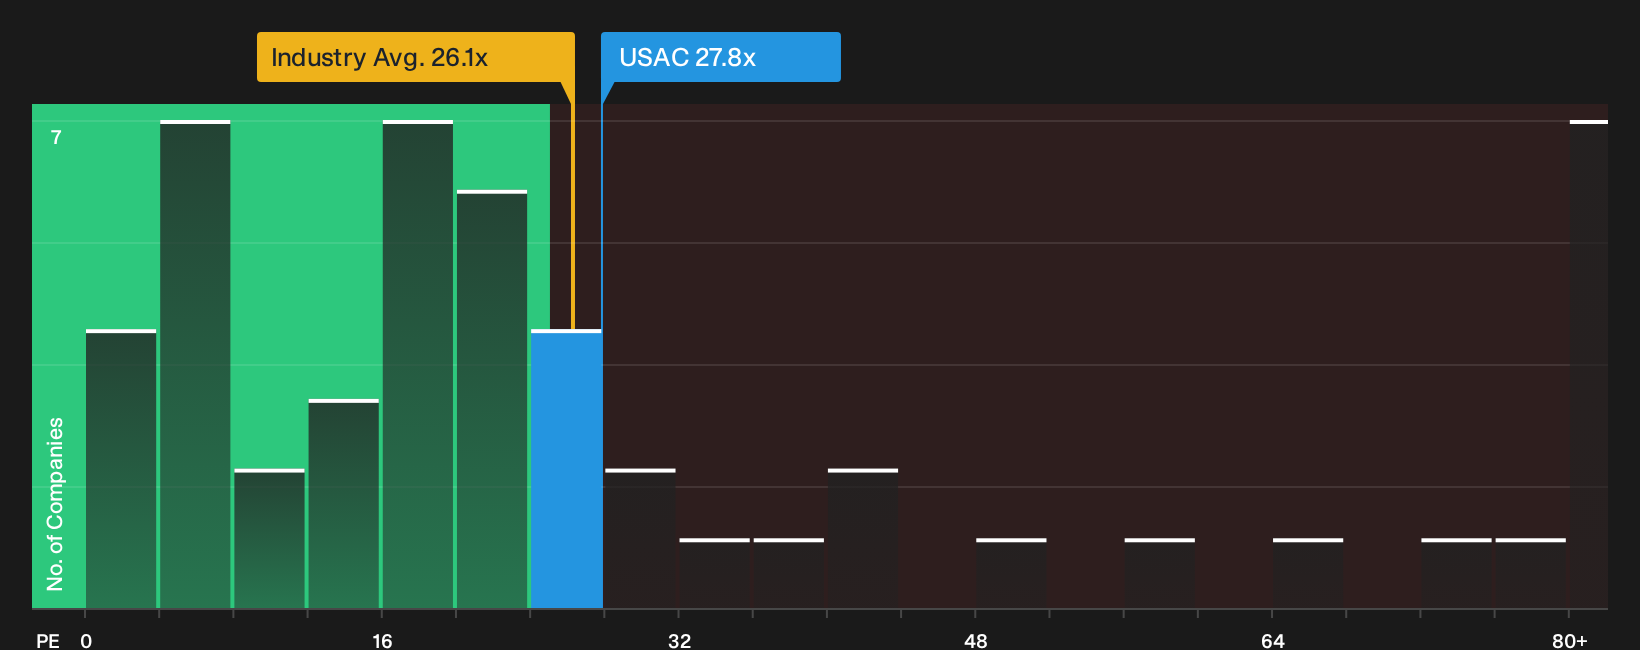
There is a different takeaway when USA Compression Partners is viewed through its P/E ratio instead of the narrative fair value. Units change hands at about 27.8x earnings, above both the US Energy Services industry at 26.1x and the estimated fair ratio of 21.1x, which points to valuation risk if expectations slip.
That premium looks even more pointed when compared with peers on 56.3x, since USAC trades cheaper than that group while still above the fair ratio level that the market could move toward if sentiment cools. The key question is whether that gap closes through stronger results or through a lower unit price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on USA Compression Partners so far. If you want to move before sentiment shifts again, weigh both sides of the story by reviewing the 2 key rewards and 3 important warning signs.
Looking for more USA Compression Partners sized ideas?
Do not stop at USA Compression Partners. Broaden your watchlist with fresh, data driven ideas so you are not relying on a single income story.
- Target long term compounding potential by using the 32 high quality undervalued stocks that highlight businesses trading below their estimated worth with quality fundamentals behind them.
- Strengthen your downside protection by scanning the 11 resilient stocks with low risk scores that focus on resilient operations and lower overall risk profiles.
- Spot under followed stories early by reviewing the 15 high quality undiscovered gems that surface quality companies the wider market may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com