
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Carlisle (CSL) Stock May Be 34% Undervalued With Cash Flow Support
Carlisle Companies enters this valuation review with a mixed setup for investors, with the stock giving up some ground in recent months while both an intrinsic value estimate and market multiples point to a cheaper profile than the current share price suggests.
- Carlisle Companies shares have returned 77.5% over five years, which puts the recent pullback into context as a step back after a strong multi year run.
- The key support for the current valuation may come from the business's ability to convert earnings into cash flow. However, any hit to construction related demand or project timing could weigh on that cash generation and challenge the thesis.
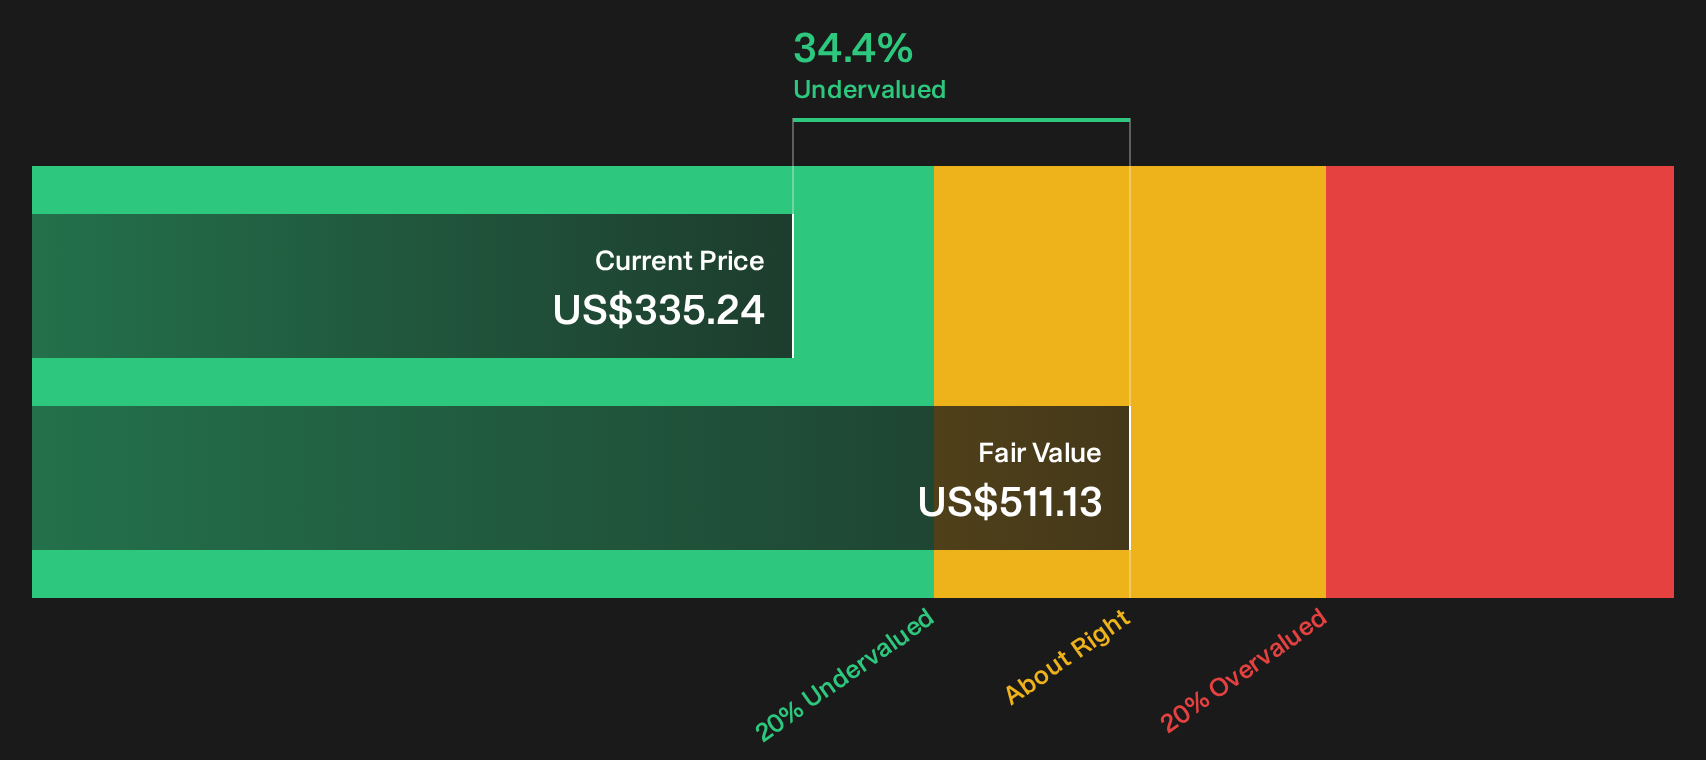
- The Discounted Cash Flow (DCF) intrinsic value estimate sits about 34.4% above the recent market price and the stock screens as undervalued on earnings multiples, so the broader checks lean cheap, with Carlisle Companies undervalued in 6 of 6 tests.
The issue now is whether Carlisle Companies' recent share price weakness has already reset expectations enough, or if the current discount to intrinsic value still offers a meaningful valuation cushion for new capital.
Capitalize on Carlisle Companies' current value signals by scanning a curated list of 32 high quality undervalued stocks that also combine solid cash generation with supportive balance sheets.Does Carlisle Companies Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach here evaluates Carlisle Companies based on the cash it is expected to generate for shareholders over time. The model starts with latest twelve month free cash flow of about $878.9 million in reporting currency. It then assumes those cash flows grow rather than shrink, using a 2 Stage Free Cash Flow to Equity setup that tapers growth as the business matures.
On those inputs, the DCF model points to an estimated intrinsic value of around $511 per share. That sits roughly 34.4% above the recent share price, so the current quotation implies a meaningful gap to the cash flow projection. For investors who put more weight on cash generation than on headline earnings multiples, Carlisle Companies appears undervalued on this intrinsic value basis.
On the DCF numbers alone, Carlisle Companies stock appears undervalued relative to the cash it is projected to produce.
Our Discounted Cash Flow (DCF) analysis suggests Carlisle Companies is undervalued by 34.4%. Track this in your watchlist or portfolio, or discover 32 more high quality undervalued stocks.
Is Carlisle Companies a Bargain on Earnings?
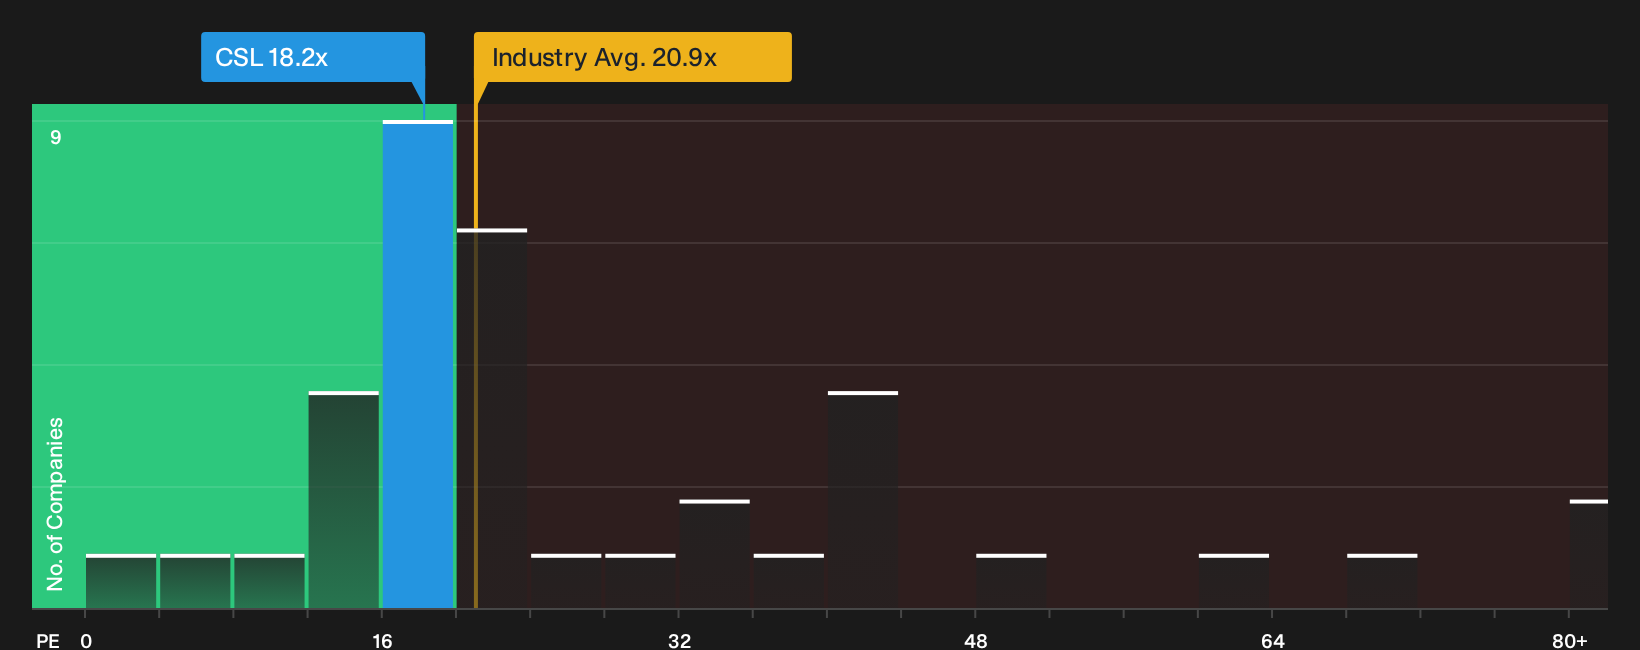
P/E works well for Carlisle Companies because earnings quality matters a lot for an industrial group with established operations and clear profitability. On this lens, the shares trade on about 18.2x earnings, which is lower than the building sector average near 20.9x and well below the broader peer group that clusters around 35.0x.
The model that blends Carlisle Companies' sector, scale and risk profile into a tailored benchmark points to a fair P/E of roughly 22.5x. That is a meaningful gap to the current 18.2x multiple and indicates investors are paying less per dollar of earnings than this framework suggests might be reasonable for the business.
On the P/E yardstick, Carlisle Companies stock appears undervalued relative to both its industry context and the modelled fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Carlisle Companies Narrative: What Would Justify Today's Price?
Narratives for Carlisle Companies build on the valuation puzzle by outlining which combinations of future growth, profitability and earnings power would need to hold for the shares to be worth much more or less than today’s quote. Each scenario links a fair value to a specific set of potential catalysts and risks for Carlisle Companies' business, allowing you to track over time which version of events appears to be taking shape on Simply Wall St's Community page.
Add your own narrative on Carlisle Companies' valuation, and provide a clear view on how its growth, margins and execution may develop from here, to be one of the first voices in the Simply Wall St community tracking how that thesis holds up as fresh data arrives.
Do you think there's more to the story for Carlisle Companies? Head over to our Community to see what others are saying!
The Bottom Line
Carlisle Companies screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and on earnings multiples, so the valuation case rests on those two lenses pointing in the same direction. The crux is whether cash generation and construction linked demand hold up well enough for that intrinsic value gap to remain credible. If free cash flow proves resilient and the market grows more comfortable with the earnings profile, the key debate becomes whether the current discount reflects genuine mispricing or a fair cushion for project and cycle risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com