
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kesko (HLSE:KESKOB) Stock May Be Fully Priced On Earnings Resilience
Kesko Oyj has delivered a strong 42.1% gain over the past three years, yet current valuation checks still flag the stock as relatively expensive rather than a clear bargain.
- A 42.1% return over three years rewards holders, which raises the bar for any new buyers who need the current price to be justified by future fundamentals.
- Expectations around Kesko Oyj's ability to sustain cash generation from its retail operations can support the share price, while any pressure on consumer demand or retail margins may weigh on what investors are willing to pay.
- With the company scoring 2 out of 6 on a broad set of valuation checks, the stock appears more expensive than an obvious value opportunity.
The issue now is whether Kesko Oyj's recent share price gains leave enough valuation room for long term investors who are thinking about starting or adding to a position.
Compare Kesko Oyj's rich valuation with a curated list of other businesses that combine quality with price discipline in the 182 high quality undervalued stocks.
Is Kesko Oyj Getting Expensive on Earnings?
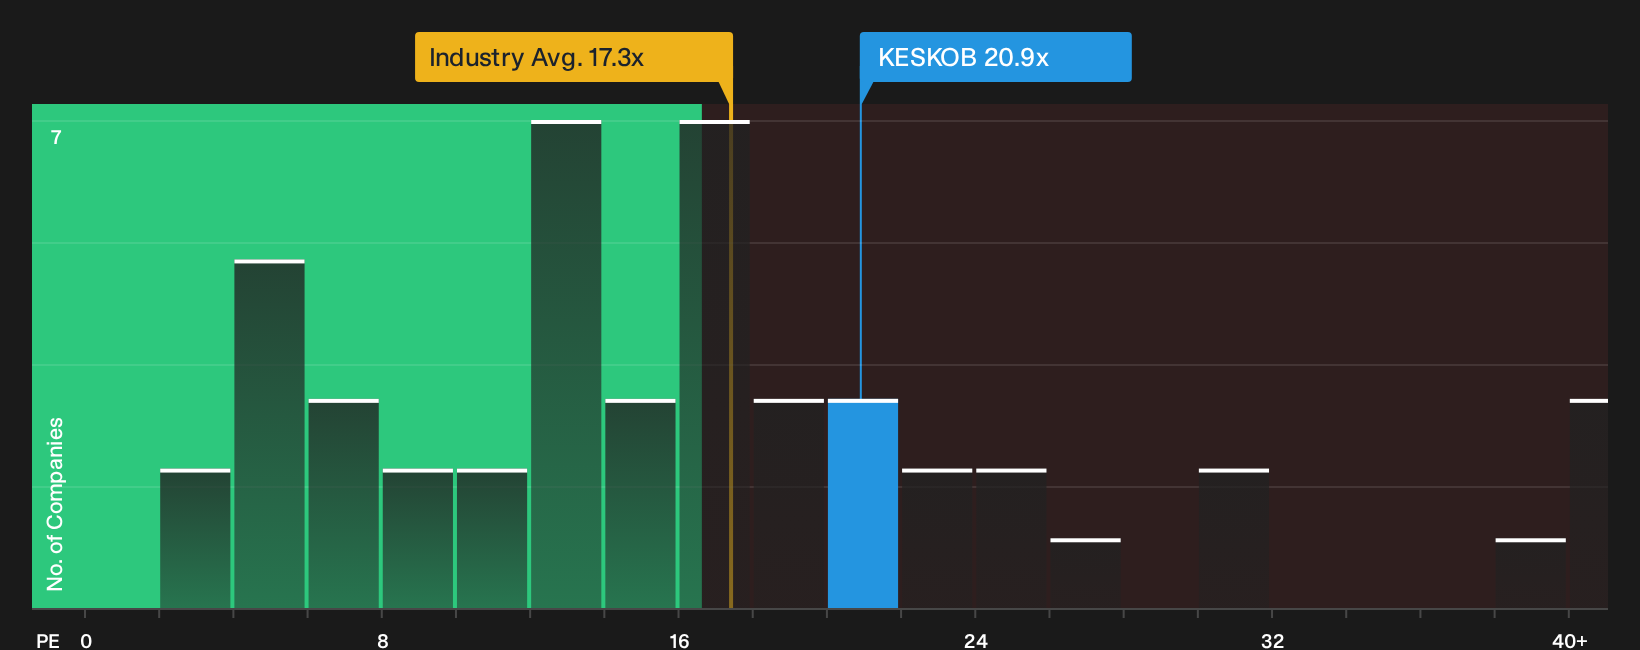
The P/E ratio fits Kesko Oyj well because earnings power is central to how investors tend to judge established retailers. On this measure, the stock trades on roughly 20.9x earnings, which sits slightly above the Consumer Retailing industry average of about 15.9x and just ahead of the peer group at roughly 20.4x. That is a modest premium to both the wider sector and closer listed comparables.
For you as a potential shareholder, this means the market is already placing a higher price on each euro of Kesko Oyj earnings than it does for the typical retailer. The current P/E does not look extreme against peers, yet it does suggest the shares are pricing in quality or resilience that cheaper alternatives in the sector are not being given. Anyone considering new capital going into HLSE:KESKOB needs to be comfortable paying that kind of earnings multiple for a retail focused group.
On the P/E yardstick, Kesko Oyj stock comes across as overvalued relative to the wider Consumer Retailing industry.
See what the numbers say about this price — find out in our valuation breakdown.
The Kesko Oyj Narrative: What Would Justify Today's Price?
Narratives for Kesko Oyj on Simply Wall St act as the missing link between the current P/E premium and the underlying expectations that would need to hold on earnings, margins and growth for the valuation to move meaningfully higher or lower from here. Each scenario ties a fair value estimate to a clear set of potential catalysts and risks so you can track over time which version of Kesko Oyj's story is actually unfolding.
Use the Narratives tool to add your own number driven case on Kesko Oyj and present your view on where its growth, margins and execution go from here.
You can be one of the first voices in the Simply Wall St community to set out a thesis on Kesko Oyj and then track how that story holds up as new data arrives.
Do you think there's more to the story for Kesko Oyj? Head over to our Community to see what others are saying!
The Bottom Line
Kesko Oyj looks overvalued on market multiples, with investors already paying up for its perceived quality and resilience relative to peers. That does not rule the stock out, but it leaves less room for disappointment if earnings, margins or consumer demand come under pressure. For new capital, the key question is whether Kesko Oyj can keep justifying a premium P/E over time, or whether the rating eventually settles closer to the rest of the Consumer Retailing group.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com