
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top Asian Growth Stocks With High Insider Ownership
As Asian markets navigate a complex landscape marked by geopolitical tensions and fluctuating oil prices, investors are increasingly focusing on growth opportunities that offer resilience amid uncertainty. In this environment, stocks with high insider ownership can be particularly appealing, as they often signal strong confidence from those closest to the company and may align interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.5% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| SEERS (KOSDAQ:A458870) | 33.8% | 35.7% |
| Ningbo Sanxing Medical ElectricLtd (SHSE:601567) | 24.9% | 56.8% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 23.9% | 28.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Underneath we present a selection of stocks filtered out by our screen.
JUSUNG ENGINEERINGLtd (KOSDAQ:A036930)
Simply Wall St Growth Rating: ★★★★★☆
Overview: JUSUNG ENGINEERING Co., Ltd. manufactures and sells semiconductor, display, and solar cell equipment both in South Korea and internationally, with a market cap of approximately ₩9.55 trillion.
Operations: The company generates revenue from semiconductor equipment and services, amounting to approximately ₩225.81 billion.
Insider Ownership: 34.9%
Earnings Growth Forecast: 91.5% p.a.
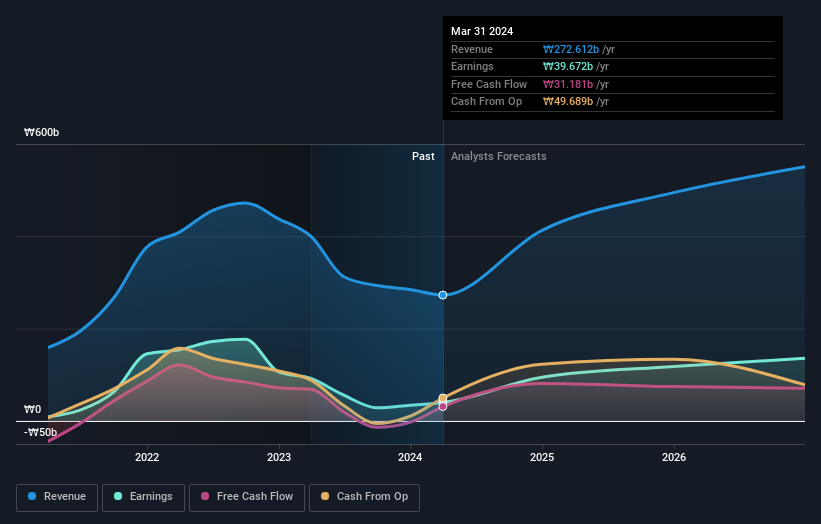
JUSUNG ENGINEERING Ltd. is positioned for substantial growth in Asia with insider ownership contributing to alignment with shareholder interests. The company's earnings and revenue are forecast to grow significantly, outpacing the KR market averages, at 91.53% and 54.2% per year respectively. Despite recent volatility in share price and a decline in profit margins from last year, its growth trajectory remains strong without significant insider trading activity over the past three months.
- Unlock comprehensive insights into our analysis of JUSUNG ENGINEERINGLtd stock in this growth report.
- Insights from our recent valuation report point to the potential overvaluation of JUSUNG ENGINEERINGLtd shares in the market.
Sunwoda ElectronicLtd (SZSE:300207)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Sunwoda Electronic Co., Ltd, with a market cap of CN¥33.98 billion, is involved in the research, development, and manufacturing of lithium-ion batteries both in China and internationally.
Operations: The company's revenue segments include the production and development of lithium-ion batteries for various applications across domestic and international markets.
Insider Ownership: 28.7%
Earnings Growth Forecast: 49.5% p.a.
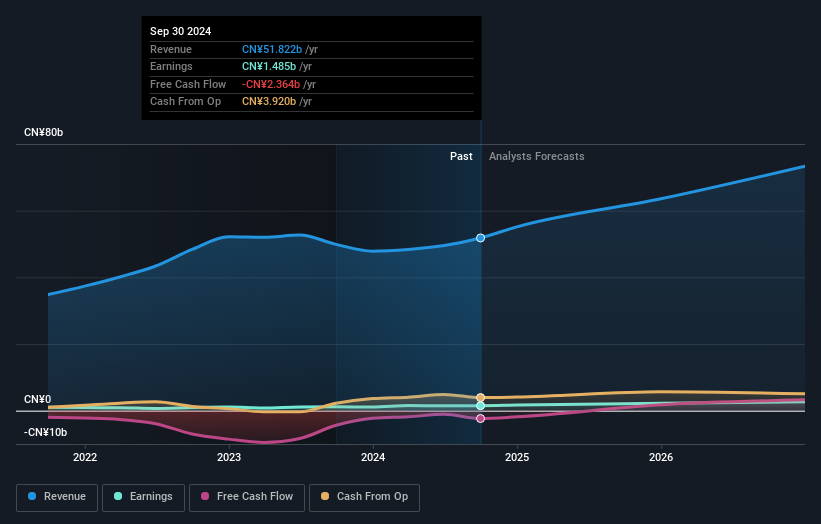
Sunwoda Electronic Co., Ltd. is poised for robust growth, with earnings projected to rise significantly at 49.5% annually, surpassing the Chinese market average. Despite a drop in net profit margin from 2.5% to 1.1%, revenue growth is expected to exceed market rates at 22.3%. Recent product innovations and European regulatory certifications bolster its position in energy storage markets, although insider trading activity remains minimal over the past three months.
- Click here to discover the nuances of Sunwoda ElectronicLtd with our detailed analytical future growth report.
- The analysis detailed in our Sunwoda ElectronicLtd valuation report hints at an deflated share price compared to its estimated value.
Lasertec (TSE:6920)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Lasertec Corporation designs, manufactures, and sells inspection and measurement equipment across Japan, South Korea, Taiwan, other parts of Asia, and the United States with a market cap of ¥3.10 trillion.
Operations: The company's revenue is primarily derived from its ¥230.49 billion segment focused on the design, manufacture, and sale of inspection and measurement equipment.
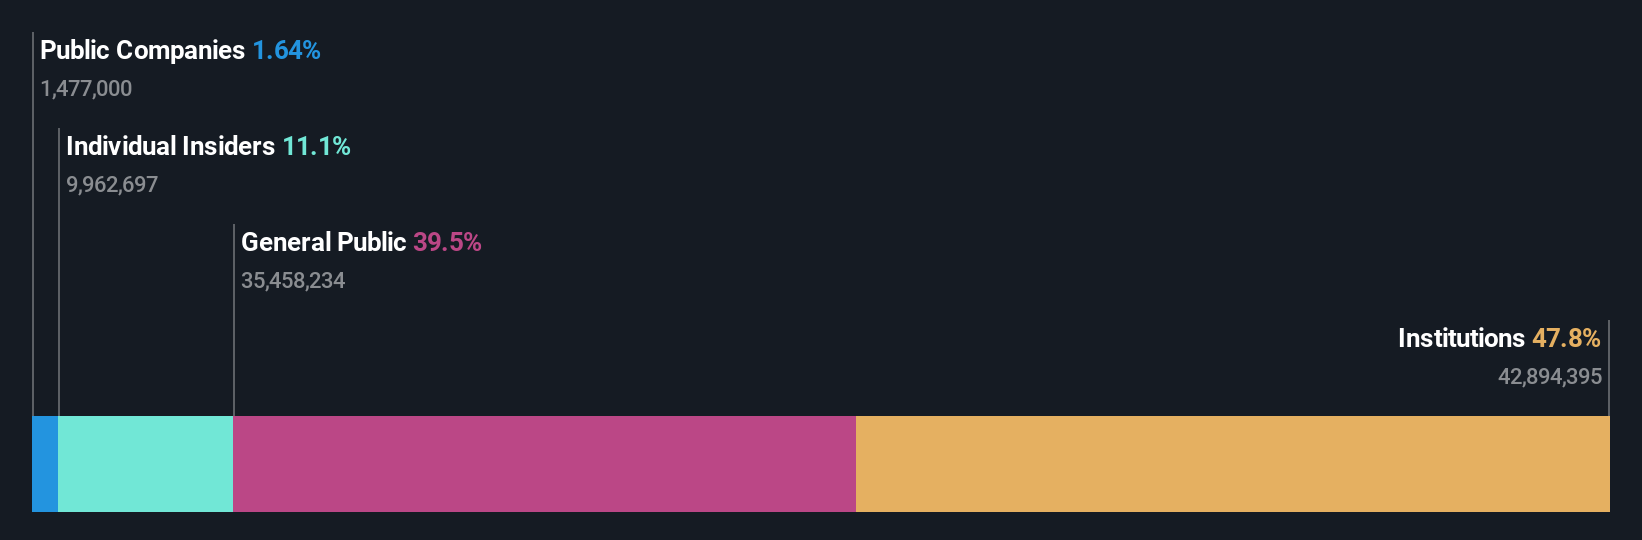
Insider Ownership: 11.1%
Earnings Growth Forecast: 19.3% p.a.
Lasertec demonstrates potential as a growth company with high insider ownership in Asia, with earnings projected to grow at 19.26% annually, outpacing the Japanese market. However, recent financial results show a decline in sales to ¥230.49 billion and net income to ¥77.49 billion for the year ending June 2026 compared to the previous year. Despite this, Lasertec has provided optimistic guidance for fiscal 2027 and announced dividend increases, reflecting confidence in future performance amidst executive changes.
- Navigate through the intricacies of Lasertec with our comprehensive analyst estimates report here.
- The valuation report we've compiled suggests that Lasertec's current price could be inflated.
Seize The Opportunity
- Dive into all 497 of the Fast Growing Asian Companies With High Insider Ownership we have identified here.
- Searching for a Fresh Perspective? We've found 7 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com