
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Could CES Energy Solutions (TSX:CEU) Be 7% Undervalued After Its Record Quarter?
Record quarter puts CES Energy Solutions in focus
CES Energy Solutions (TSX:CEU) drew investor attention after reporting record quarterly performance, with strong revenue growth, improved profitability, and resilient demand for its specialised chemical solutions across the North American oil and gas sector.
The record quarter has arrived on top of powerful momentum, with CES Energy Solutions’ share price up 4.09% in the last session, 22.72% over 90 days and 62.67% year to date, while its 1-year total shareholder return of 136.99% points to sustained strength rather than a short-lived spike.
Compare CES Energy Solutions’ surge with other energy plays by scanning our hand picked 39 power grid technology and infrastructure stocks, which may also be benefiting from rising service intensity and infrastructure demand.
After a 1 year total return of 136.99% and a current price of CA$20.09, CES Energy Solutions now forces a tougher question: Does the balance of risk and reward still lean toward buyers once valuation is stripped back and compared with fundamentals?
Most Popular Narrative: 7.1% Undervalued
On the most followed valuation view, CES Energy Solutions screens as undervalued, with a fair value of CA$21.63 versus the CA$20.09 last close, and that gap rests on some punchy long term assumptions.
The company's ongoing bids for large production chemical contracts, primarily representing new customers, could significantly expand market share and provide higher-margin, recurring revenues, which would enhance both top-line growth and EBITDA margins if awarded. Anchoring its growth in complex well completions and producers' focus on maximizing hydrocarbon recovery, CES is benefitting from long-term demand for advanced chemical solutions, driving resilient revenue growth even amidst rig count softness.
Want to see what underpins that confidence in CES Energy Solutions? The narrative leans on ambitious revenue compounding, fatter margins, and a future earnings multiple that assumes the cash machine keeps running hard.
Result: Fair Value of CA$21.63 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, CES Energy Solutions faces real pressure if energy transition policies curb drilling activity, or if customer tenders further squeeze pricing and compress margins.
Find out about the key risks to this CES Energy Solutions narrative.
Another view on CES Energy Solutions’ valuation
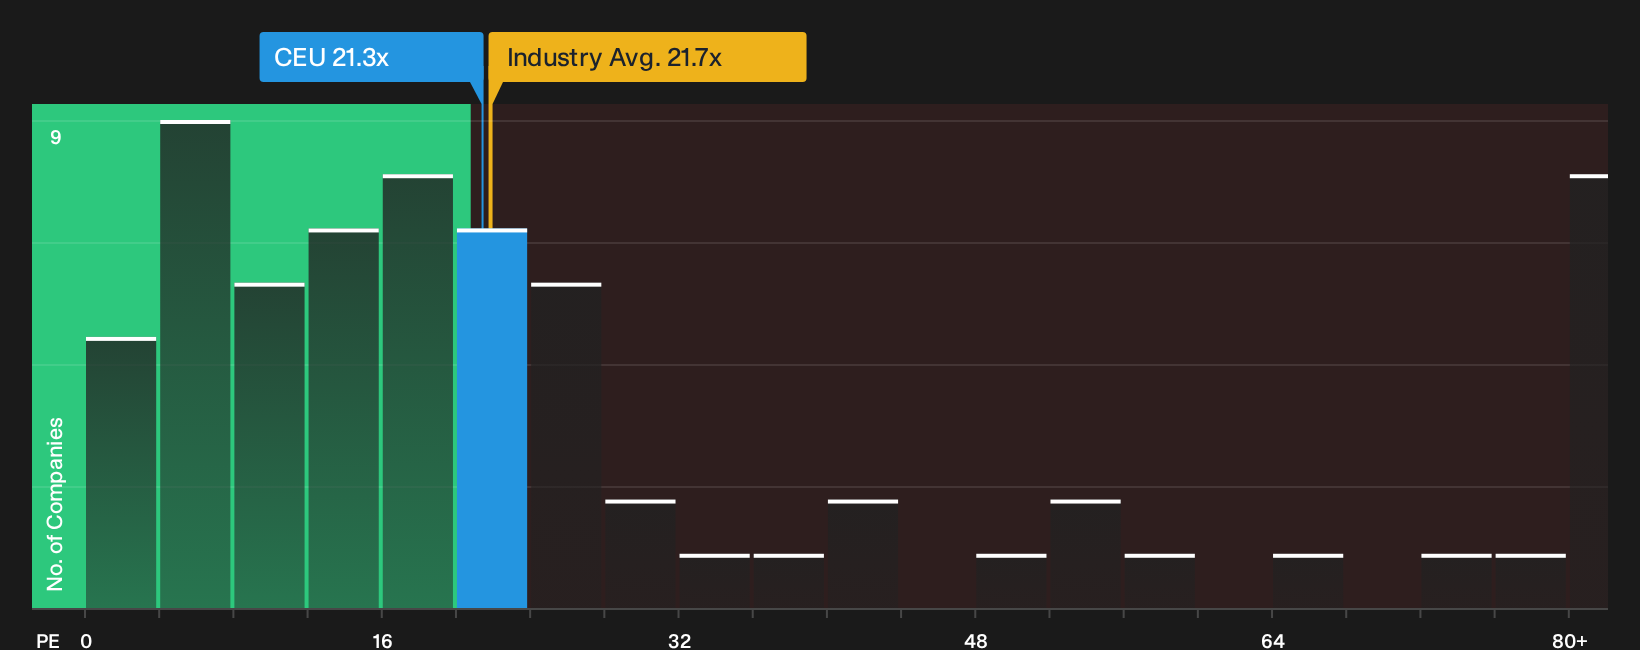
The first lens suggests CES Energy Solutions is about 7.1% undervalued, with fair value around CA$21.63 compared with a CA$20.09 share price. A second lens tells a different story. At a P/E of 21.3x versus a fair ratio of 17.7x, the stock appears expensive, even though that headline multiple is slightly below both peer and North American industry averages. This raises a key question: is the opportunity in the discount to fair value, or is the risk in the relatively high earnings multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this CES Energy Solutions story points to promise, while flagged issues pull in the opposite direction. Move fast and stress test the data for yourself using the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond CES Energy Solutions?
If CES Energy Solutions has sharpened your focus, do not stop here. Broaden your watchlist with fresh angles and let the data surface what you might otherwise miss.
- Target stronger value opportunities by scanning the 5 high quality undervalued stocks that combine pricing gaps with solid underlying fundamentals.
- Build a more resilient portfolio by reviewing the 1 resilient stocks with low risk scores that score well on stability and financial strength.
- Spot future standouts early by checking the 9 high quality undiscovered gems that pair quality metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com