
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why JPMorgan Is Betting That Lithium Americas Stock Will Double.
Lithium Americas Corp. (LAC) is back on Wall Street’s radar after JPMorgan turned bullish on the lithium developer, upgrading the stock to an “Overweight” rating from “Neutral” and setting a $6 price target. The target implies close to 100% upside from the stock’s previous close, giving investors a potentially significant re-rating opportunity if the bank’s bullish assumptions play out.
The call reflects a more constructive outlook for lithium prices. JPMorgan recently raised its lithium price assumptions, arguing that lithium carbonate prices have remained above $20 per kilogram and that the market could face a supply deficit through the end of the decade. Those higher price assumptions materially improve JPMorgan’s estimates for Lithium Americas’ long-term earnings and net asset value.
Meanwhile, at the center of the investment thesis is Thacker Pass, Lithium Americas’ flagship Nevada project and one of the most important emerging domestic lithium developments in the U.S. Construction is progressing, with the company targeting mechanical completion in late 2027 and commercial production in 2028. Phase 1 is designed for annual production of 40,000 tonnes of battery-grade lithium carbonate.
With construction progressing and lithium demand expected to remain closely linked to electric vehicles, energy storage, and the U.S. push to secure critical-mineral supply chains, JPMorgan’s conviction looks justified.
About Lithium Americas Stock
Lithium Americas is a Canada-based lithium development company focused on advancing lithium resources critical to the North American battery supply chain. Headquartered in Vancouver, British Columbia, the company’s flagship asset is the Thacker Pass project in Humboldt County, Nevada, which it is developing through a joint venture with General Motors Company (GM). Lithium Americas has a market cap of around $1.1 billion.
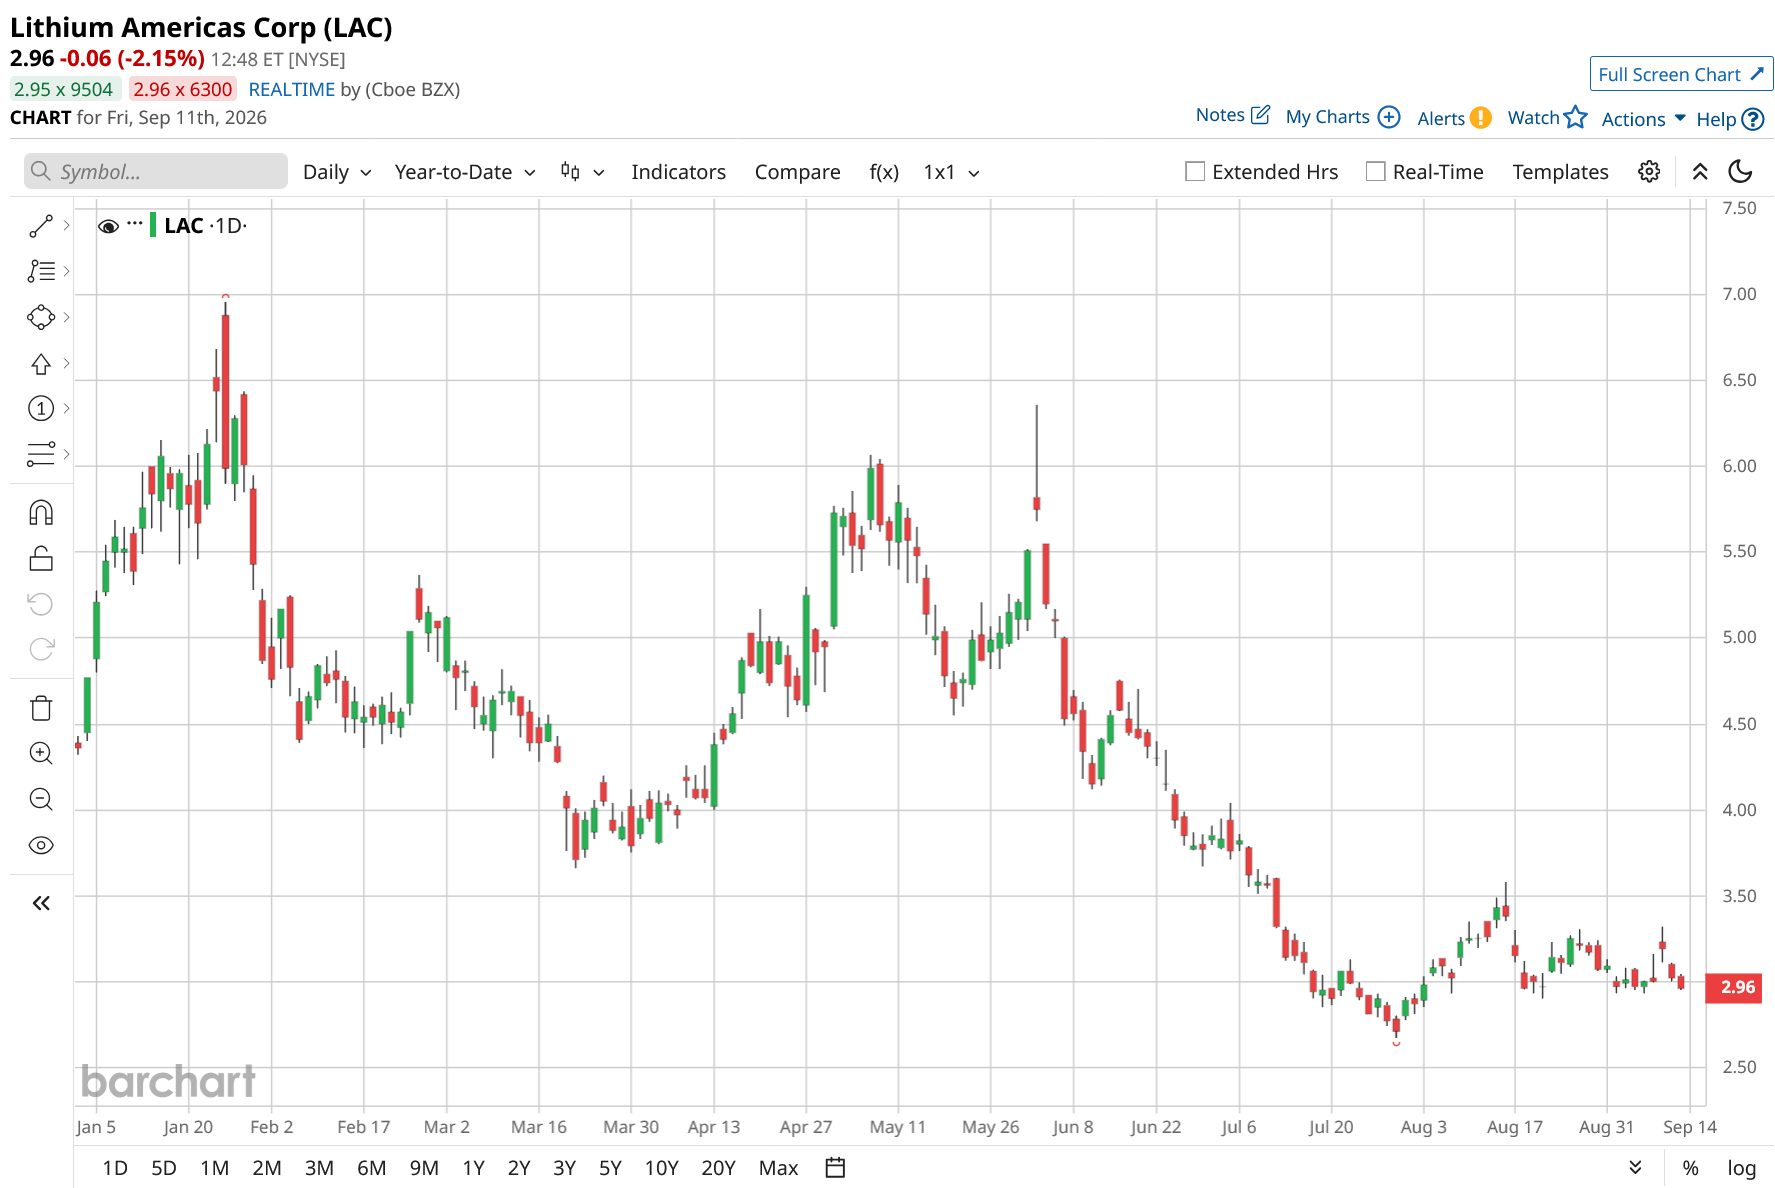
LAC has endured a difficult 2026, with shares down 32% year-to-date (YTD), despite a sharp rebound in the latest session. The stock closed at $3.19 on Sept. 9, up 6.3%, after trading as high as $3.32 during the session, as JPMorgan’s return to an “Overweight” rating and $6 price target renewed investor interest. However, the stock witnessed a 5.3% pullback in the following session.
Meanwhile, the decline earlier in the year has largely reflected concerns surrounding the cost, financing, and execution risks associated with Thacker Pass. The company remains in the development stage and has targeted $1.3 billion to $1.6 billion of Phase 1 capital spending in 2026, while $1.8 billion of construction capital and other project-related costs had already been capitalized as of June 30. Investors have also been concerned about potential dilution and debt financing as it funds the multibillion-dollar project.
Lithium Americas's weakness has left the stock 72% below its 52-week high of $10.52, reached last year. Nevertheless, the stock has managed to remain up by 4% over the past year.
LAC stock currently trades at a discount to industry peers at 0.77x price-to-book.
Lithium Americas Remains Pre-Revenue
Lithium Americas released its second-quarter 2026 results on Aug. 13, covering the quarter ended Jun. 30.
While LAC remains pre-revenue, net income attributable to LAC stockholders was $2.2 million, versus a $12.4 million loss a year earlier, while EPS improved to a loss of $0.02 from a loss of $0.06. However, the improvement did not come from operating growth. LAC benefited from a $4.5 million gain on its JV warrant obligation, a $5.7 million gain related to convertible debt and conversion features, and $6.7 million of other income, compared with $1.4 million of other income in Q2 2025.
On the other hand, general and administrative expenses increased 93.6% year-over-year (YoY) to $15.1 million. Transaction costs, however, fell to zero from $13.3 million in the prior-year quarter. For the first six months of 2026, LAC reported net income of $6.3 million versus a $24.8 million net loss in the first half of 2025, while net income attributable to shareholders improved to $1.7 million from a $23.1 million loss.
The balance sheet remained a major focus. LAC ended June with $1.3 billion in cash and restricted cash, up from $905.6 million at the end of 2025. The company received a $342 million third advance under its U.S. Department of Energy loan in June, bringing cumulative DOE advances to $1.2 billion.
Operationally, Thacker Pass continued to advance, with detailed engineering more than 95% complete and procurement exceeding 80% as of June 30. The company remained on track for mechanical completion in late 2027, while major electrical construction was progressing.
With Phase 1 designed to produce approximately 40,000 tonnes of battery-grade lithium carbonate annually, investors will be watching whether LAC can stay within its 2026 capex guidance and maintain its late-2027 completion target as the project moves toward peak construction.
Analysts anticipate loss per share to improve 76.1% YoY to $0.11 in fiscal 2026 but again deteriorate 63.6% to $0.18 in fiscal 2027.
What Do Analysts Expect for LAC Stock?
In addition to JPMorgan turning bullish, ATB Cormark Capital Markets also maintained a “Buy” rating and $10 price target on Aug. 18, signaling significant upside potential for Lithium Americas as Thacker Pass continues to advance.
Meanwhile, BMO Capital Markets on Aug. 14 maintained a “Market Perform” rating and lowered its price target to $4 from $4.5, while TD Cowen maintained a “Hold” rating and lowered its price target to $4.5 from $5 on Aug. 17, reflecting a more cautious view on Lithium Americas.
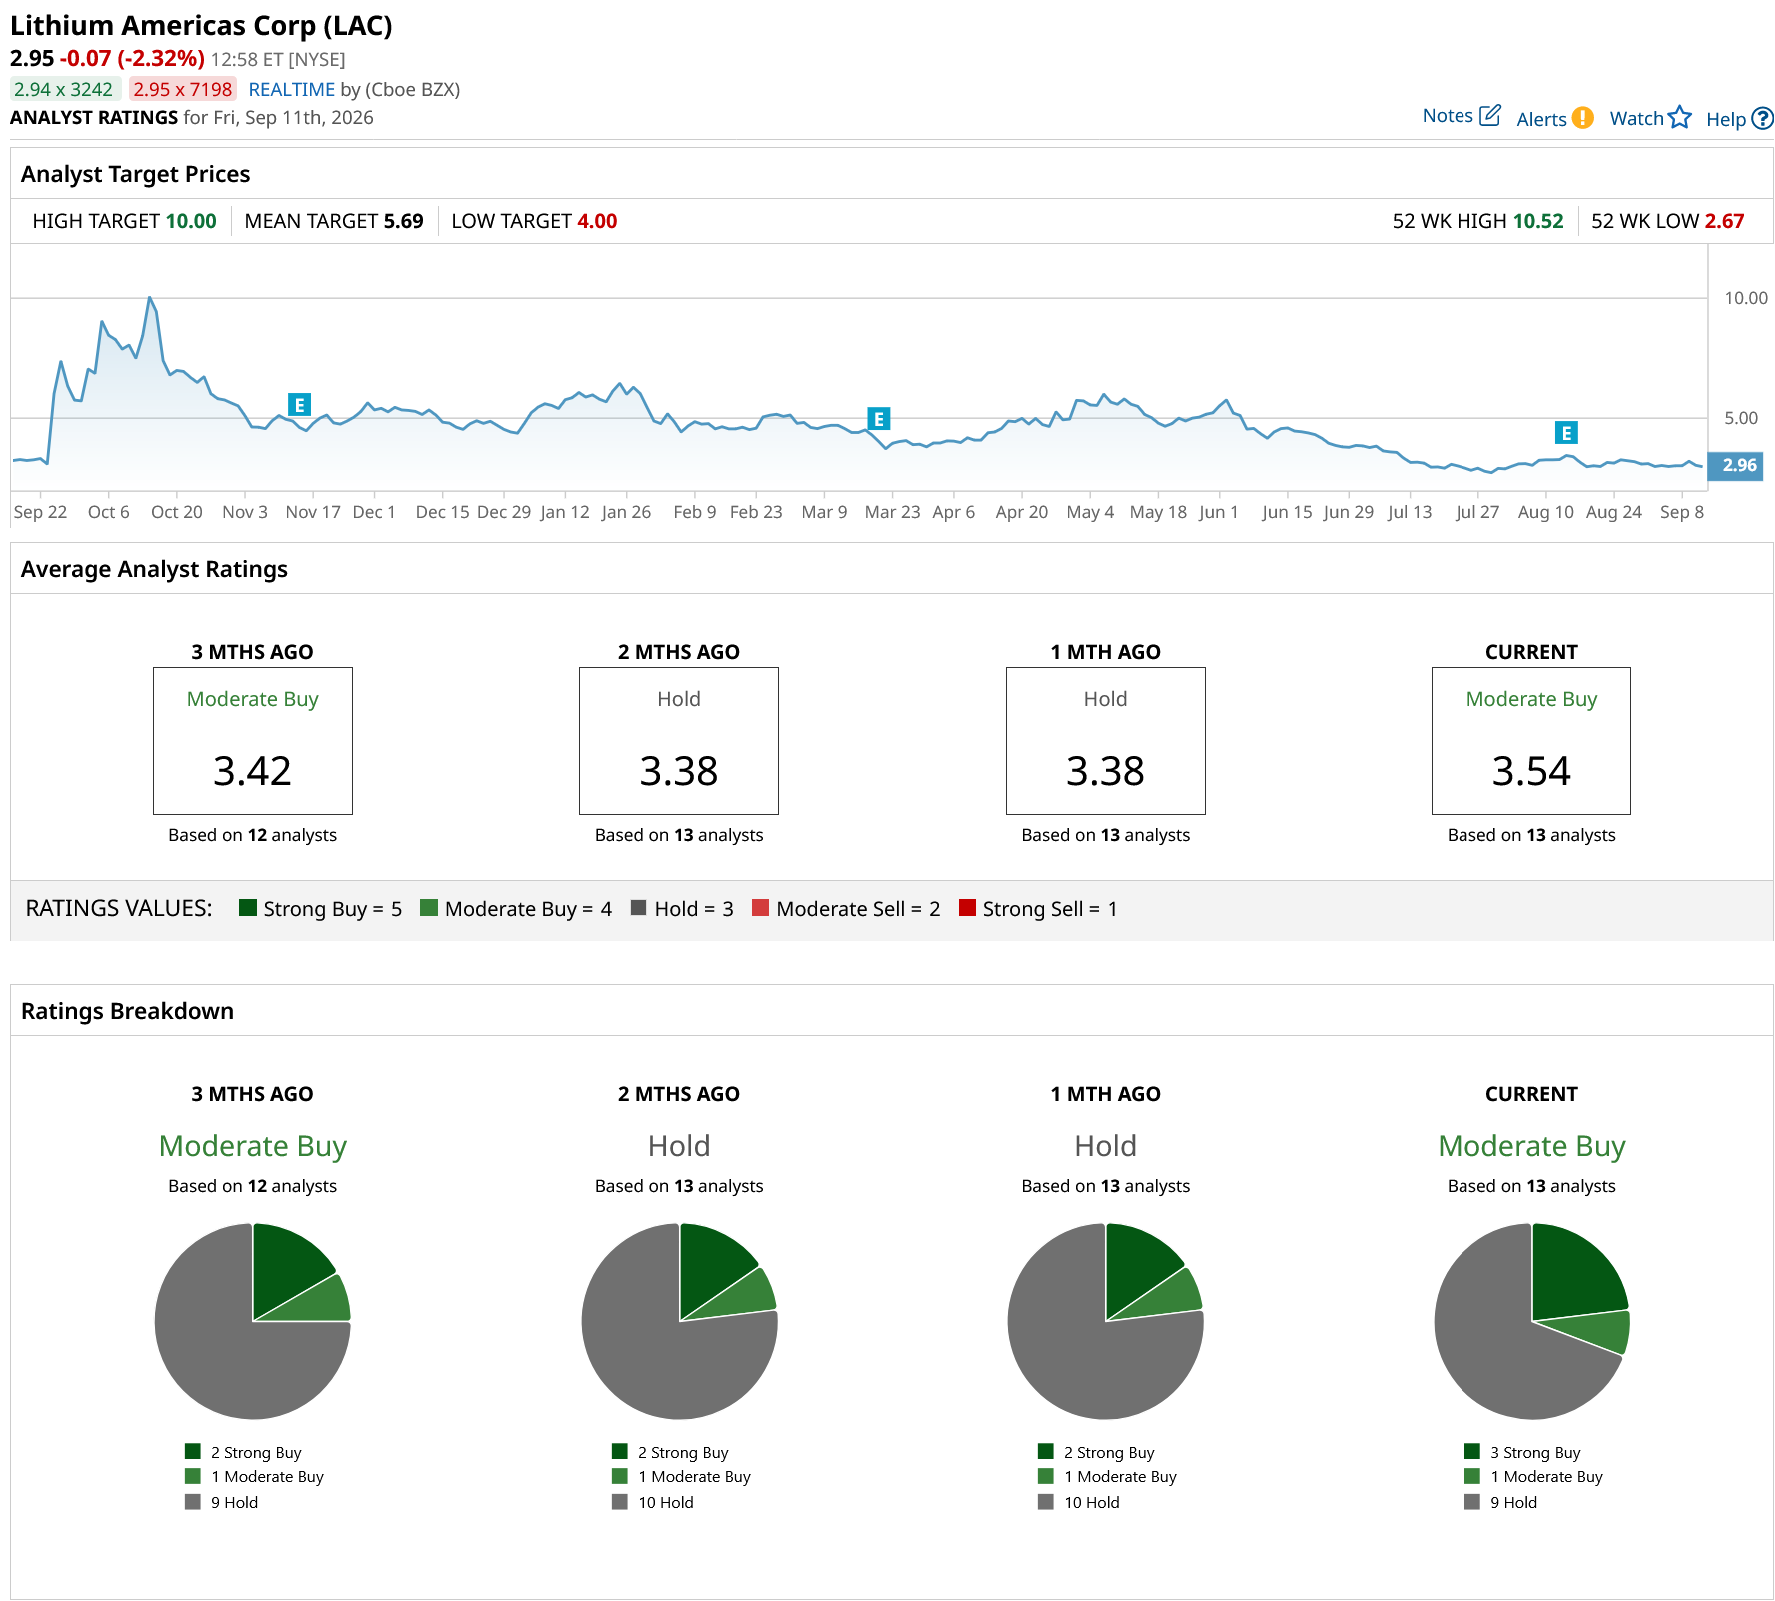
LAC stock has a consensus “Moderate Buy” rating overall. Out of 13 analysts covering the stock, three recommend a “Strong Buy,” one suggests a “Moderate Buy,” and nine analysts stay cautious with a “Hold” rating.
LAC’s average analyst price target of $5.69 indicates an upside of 93%, while the Street-high target price of $10 suggests 239% upside ahead.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.