
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
American Electric Power (AEP) Stock Could Be 7% Rich As Dividend Support Holds
American Electric Power Company has delivered a strong 75.5% share price gain over the past five years, yet the latest valuation checks send a cooler message, with the Dividend Discount Model (DDM) pointing to a fair intrinsic value and the broader metrics leaning on the expensive side overall.
- A roughly 75.5% return over five years sets a solid backdrop and raises the bar for what counts as a compelling entry point now.
- Expectations that a regulated utility like American Electric Power Company can keep cash flows relatively steady may support the current price, while any pressure on allowed returns or higher capital spending needs could weigh on what investors are willing to pay.
- The recent valuation work suggests American Electric Power Company looks undervalued on earnings style multiples, yet with a low overall value score of 1 out of 6 it does not screen as a clear bargain once all the checks are combined.
The issue now is whether American Electric Power Company's current valuation leaves enough upside to justify the risks after that multi year run.
Stack the recent 75.5% five year return for American Electric Power Company against other potential opportunities by scanning 39 power grid technology and infrastructure stocks in one quick pass.
Is American Electric Power Company Fairly Priced on Dividends?
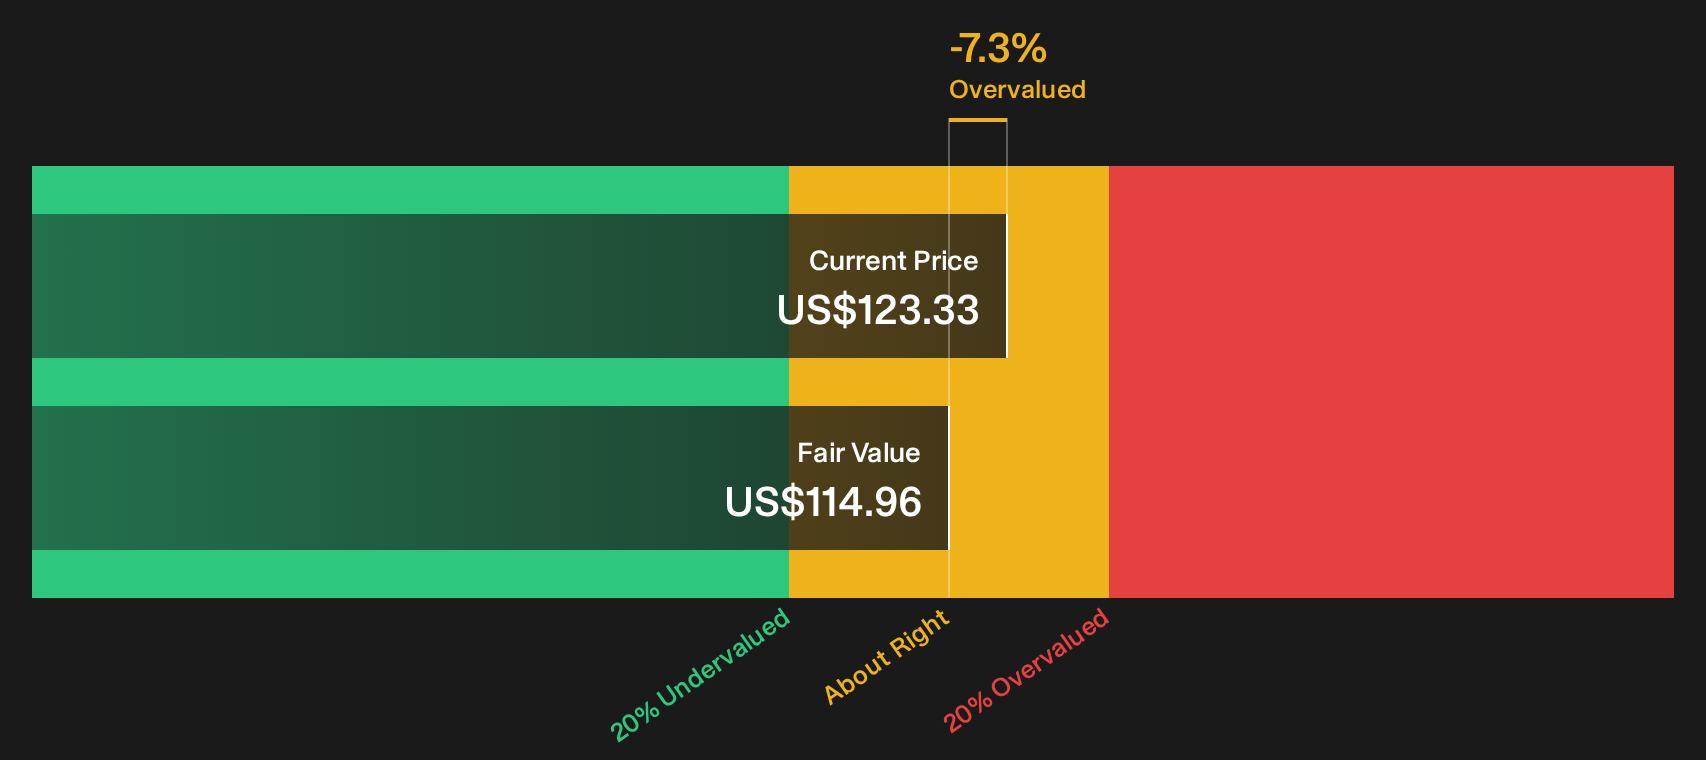
The Dividend Discount Model (DDM) looks at what you pay today against the stream of dividends you expect over time. For American Electric Power Company, the inputs lean on a current dividend per share of about $4.11, a return on equity of 10.51% and a payout ratio a little above 65%, which together imply dividend growth of roughly 3.7% a year based on the retained earnings calculation.
Run through that framework, the DDM points to an intrinsic value of about $114.96 per share, which comes out roughly 7.3% above where American Electric Power Company currently trades. The gap is not huge and it rests on the idea that the utility can keep funding its dividend while only recycling about one third of earnings back into the business at similar return levels.
On this dividend based view the stock comes out about fairly valued, with only a modest premium to the current share price implied by the DDM output.
American Electric Power Company is fairly valued according to our Dividend Discount Model (DDM), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Does American Electric Power Company Look Undervalued on Earnings?
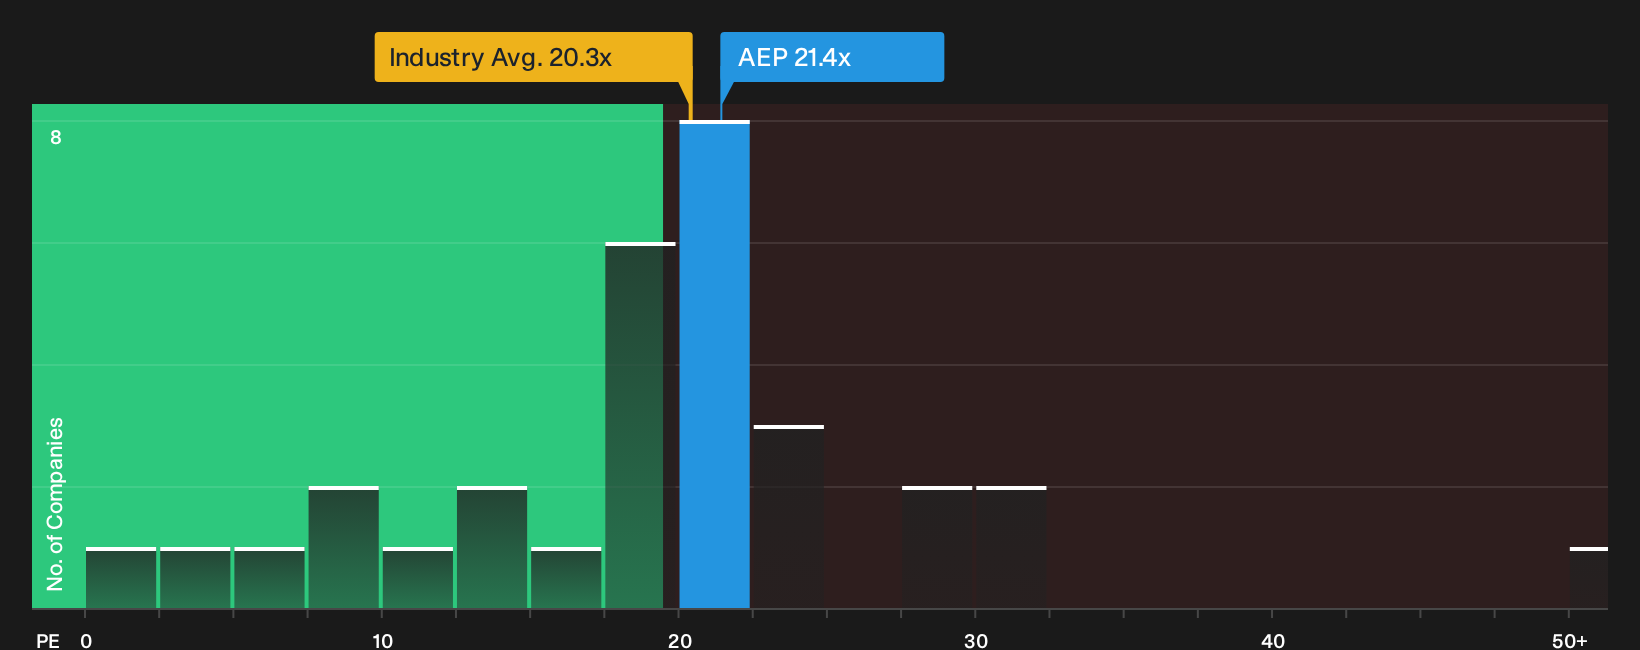
The P/E ratio tends to fit American Electric Power Company reasonably well because earnings for a regulated utility are usually the main anchor for what investors are willing to pay. On this measure, the stock trades at about 21.4x earnings, which is only slightly above both the broader electric utilities sector on roughly 20.3x and the peer group average near 20.9x.
The valuation model that blends factors like size, profitability and risk suggests a fair P/E closer to 24.0x for American Electric Power Company. That is somewhat higher than the current multiple, which indicates the market is pricing the shares at a discount to what this framework would indicate, even after the multiyear share price gain already on the board.
On the P/E yardstick, American Electric Power Company currently screens as undervalued relative to the fair multiple implied by its fundamentals and sector profile.
See what the numbers say about this price — find out in our valuation breakdown.
The American Electric Power Company Narrative: What Would Justify Today's Price?
Narratives for American Electric Power Company pick up where this valuation puzzle leaves off, and explain which paths for earnings, margins, and growth would need to hold for the stock to be worth materially more or less than today’s price. All of this is housed on Simply Wall St’s Community page. Each narrative ties a specific fair value estimate to a clear story about American Electric Power Company's possible catalysts and risks, so you can track which version seems to be unfolding over time.
Community views on American Electric Power Company now stretch from “data center-fuelled opportunity” to “AI premium that already prices in the good news.”
Bull case: 15% undervalued
"AEP is capitalizing on increased load growth, expecting retail load growth of 8% to 9% annually through 2027, driven by commercial and industrial demand, which should significantly boost revenue…"
Read the full Bull Case to see why American Electric Power Company could be undervalued
Bear case: 9% overvalued
"The market is no longer valuing AEP on current cash flow alone, it is pricing in its role as the exclusive toll keeper for the AI era…"
Read the full Bear Case to see why American Electric Power Company could be overvalued
Do you think there's more to the story for American Electric Power Company? Head over to our Community to see what others are saying!
The Bottom Line
American Electric Power Company screens as roughly in line with the intrinsic value suggested by the Dividend Discount Model (DDM), with only a small implied upside. The tailored P/E view tilts undervalued, yet the broader checklist remains weak, which keeps the signal mixed rather than clearly indicating a cheap valuation. What really determines the outcome from here is whether American Electric Power Company can sustain the cash generation and capital spending balance that supports its dividend path without eroding investor confidence in that earnings profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com