
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Share Offering Require Action From Ingram Micro (INGM) Investors?
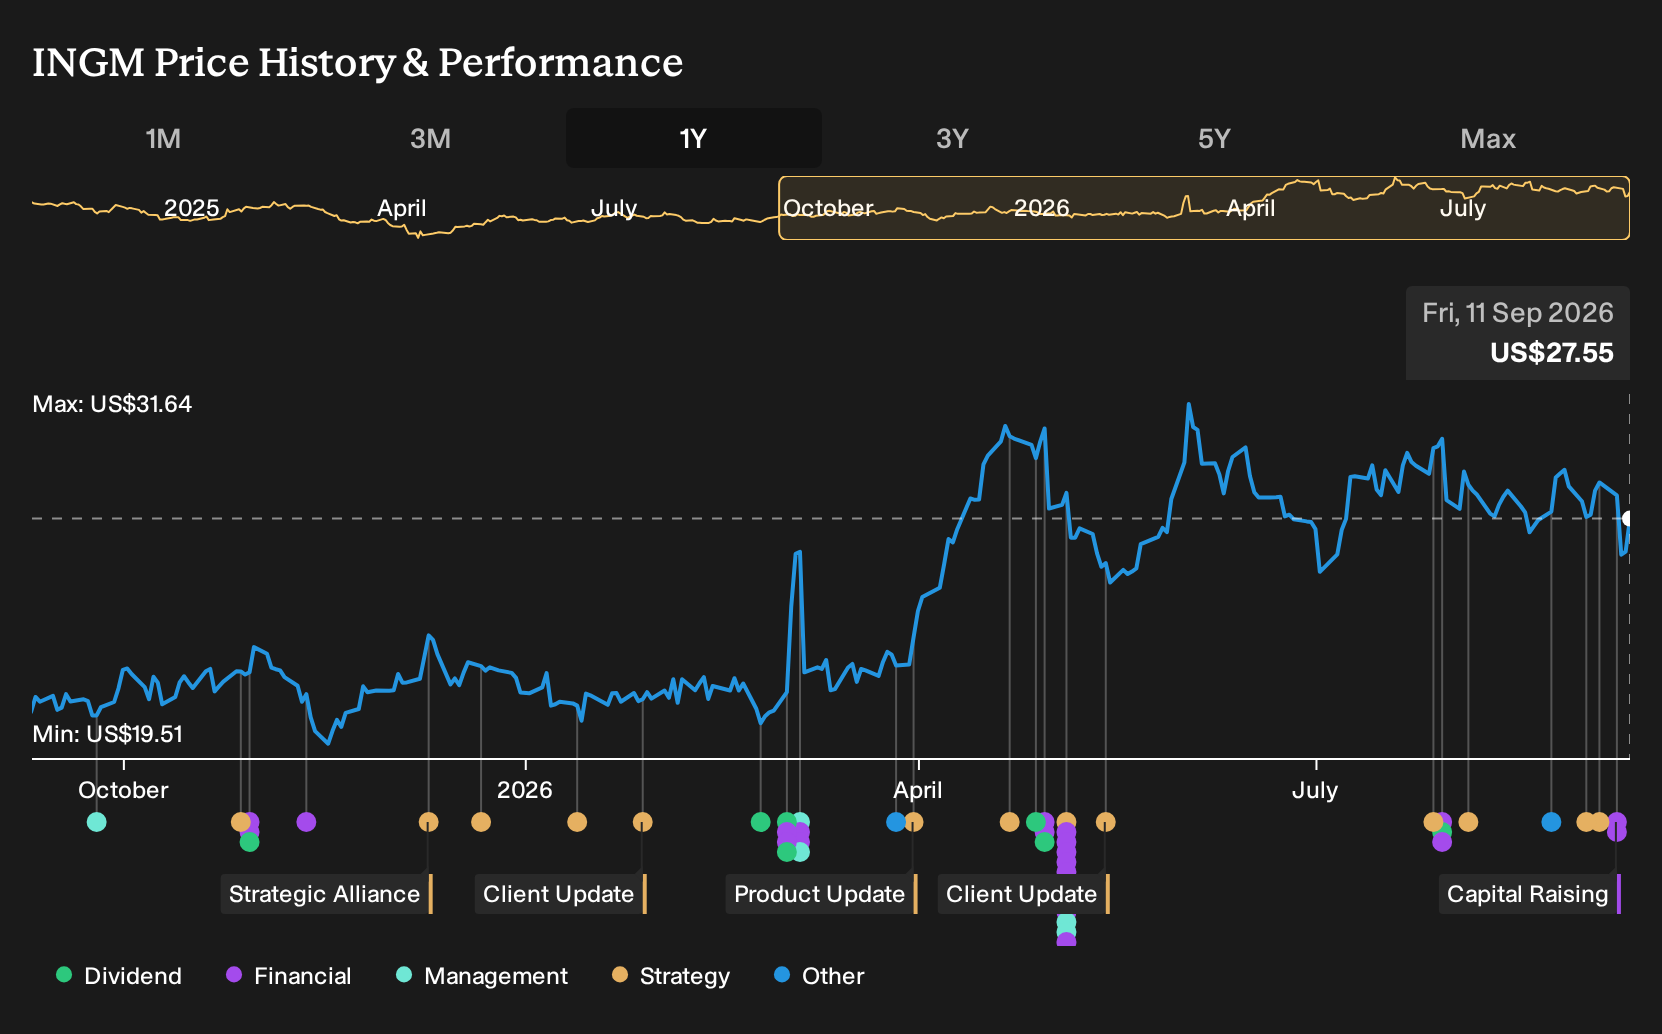
- Ingram Micro Holding has recently completed a follow on equity offering of 13,125,000 common shares at US$27.25 each, raising about US$357.7 million with a small per share discount.
- At the same time, Crossware and CyberFOX announced expanded and new distribution agreements with Ingram Micro, which deepen the Xvantage platform’s role in email governance and cybersecurity for channel partners across North America.
- Now the focus shifts to how Ingram Micro Holding's fresh equity capital and broader Xvantage partner ecosystem might influence the longer term investment narrative.
Compare Ingram Micro Holding’s fresh capital raise and Xvantage momentum with other potential breakouts by scanning our curated list of 89 AI infrastructure stocks.
Ingram Micro Holding Investment Narrative Recap
To own Ingram Micro Holding, you need to believe its role as a key distributor in AI infrastructure and cloud can offset late cycle PC demand and low margin GPU and server volumes. The fresh US$357.7m equity raise appears most relevant to strengthening the balance sheet and funding working capital for that hardware heavy mix.
The near term catalyst remains execution on Xvantage and other AI centric platforms that can convert proofs of concept into scaled partner usage. The biggest risk is that higher working capital needs and low margin infrastructure deals, combined with debt not well covered by operating cash flow, keep pressure on cash generation.
The Crossware expansion inside Ingram Micro Holding’s Xvantage platform ties directly to that catalyst. It increases the range of email governance and marketing tools that partners can source through a single pane of glass, which matters if SMB demand and higher value services are going to support margins alongside large infrastructure projects.
There is also meaningful risk concentration. If offerings such as Crossware Email Signature or CyberFOX do not drive broader adoption of Xvantage and its AI tools, then mix could continue tilting toward large, low margin GPU and server deals. That would make it more difficult for the business to improve earnings quality while managing working capital and leverage.
Ingram Micro Holding's current analyst narrative points to revenues of US$61.4b and earnings of US$678.6m by 2029, based on a 3.1% yearly revenue growth rate and an increase in forecast earnings of about US$248m from US$430.6m today.
Uncover why Ingram Micro Holding's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Ingram Micro Holding focuses squarely on hardware mix. Pessimistic analysts worry that client and endpoint volumes stay heavy while higher margin services lag, which could keep earnings closer to about US$649.5m on roughly US$60.0b of revenue by 2029. Those estimates came before this capital raise and Xvantage news, so you may see forecasts shift as opinions adjust.
Explore another Ingram Micro Holding fair value estimate, including one that suggests as much as 37% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ingram Micro Holding research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ingram Micro Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingram Micro Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ingram Micro Holding?
Once you have a view on Ingram Micro Holding, it can help to widen the lens and compare it with other stocks that fit different risk and return profiles. The Simply Wall St Screener gives you a way to sort through the market quickly using the metrics that matter most to you.
- If you want income and resilience to be front and center, check out a curated set of 6 dividend fortresses that might suit a more yield focused approach.
- If capital preservation and steadier fundamentals are higher on your list, start with our 11 resilient stocks with low risk scores and see which businesses align with your comfort zone.
- If you are hunting for overlooked opportunities with stronger balance sheets and earnings quality, scan through the 15 high quality undiscovered gems and build a watchlist of potential candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com