
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Carel Industries (BIT:CRL) Stock May Be Rich Despite Its 18% Three Year Return
Carel Industries has delivered a solid 18.0% return over the past three years, yet the stock now screens as expensive on broader valuation checks, which raises questions about how much upside is already priced in. With the shares recently closing at €26.95, the gap between past returns and current pricing is front and center for anyone assessing the valuation today.
- The 18.0% gain over three years shows Carel Industries has rewarded long term holders, which can make new entry points feel less forgiving if expectations cool.
- Future revenue growth and margin resilience can support today’s multiples. Any slowdown in cash flow generation or higher capital needs may weigh on how investors value the business.
- The stock scores 1 out of 6 on broad valuation checks, which leans more toward expensive than a clear bargain.
For investors, the debate is whether Carel Industries’ recent share price and track record leave enough valuation headroom to justify buying or adding at current levels.
Compare Carel Industries’ rich valuation with other potentially better priced businesses by scanning the hand picked 183 high quality undervalued stocks that also pair solid cash flows with stronger value scores.
Is Carel Industries Getting Expensive on Earnings?
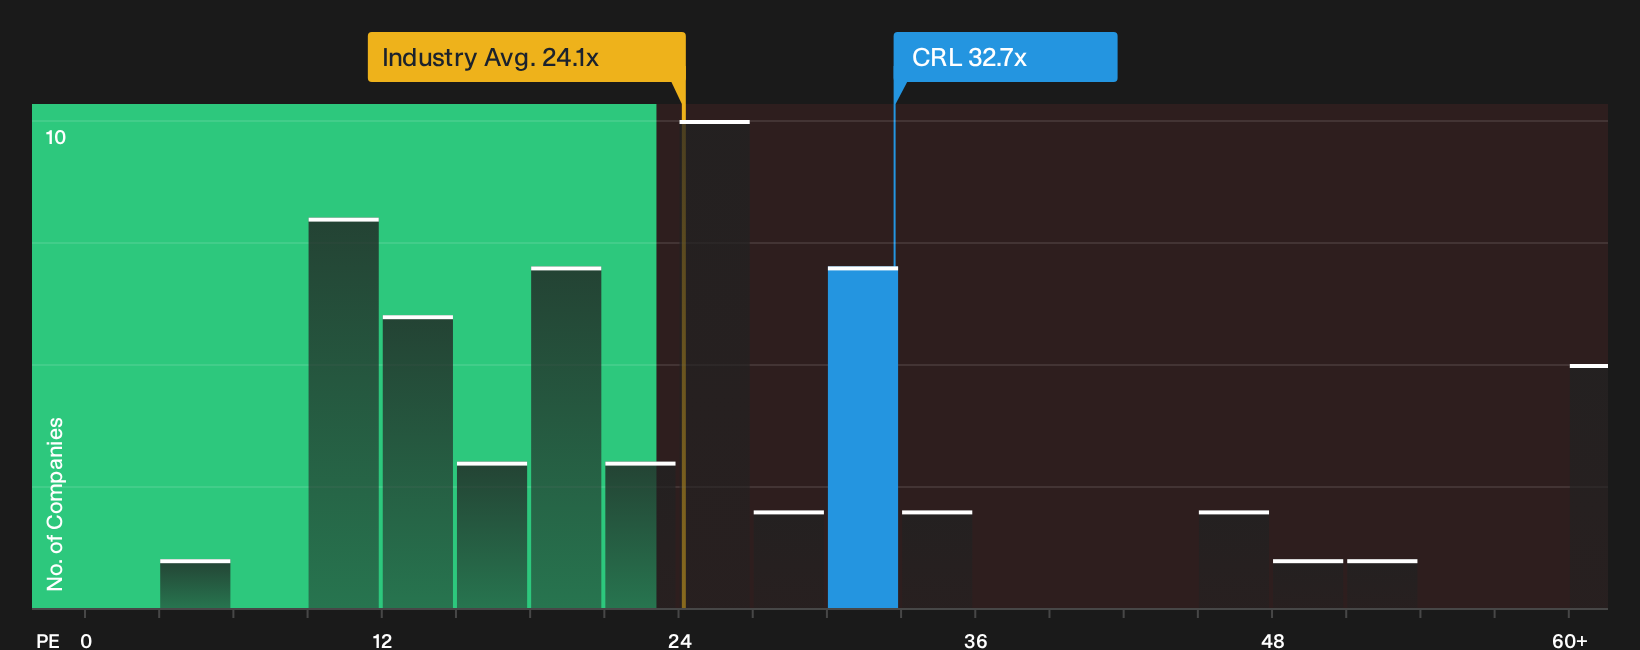
The P/E ratio is a clear way to see what you are paying for each euro of earnings at Carel Industries. On this basis, the stock trades at about 32.7x earnings, which is a premium to the wider building industry on roughly 18.2x and also ahead of the peer group average near 23.1x.
The tailored fair P/E multiple for Carel Industries is closer to 18.6x, based on its sector, profitability profile and risk inputs. This is below the current 32.7x, so the shares show a valuation gap that already reflects a strong outlook compared with what this framework would usually assign.
On this earnings multiple, Carel Industries appears richly valued, with investors paying a premium to both peers and the fair-value P/E suggested by the model.
See what the numbers say about this price — find out in our valuation breakdown.
The Carel Industries Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Carel Industries pick up where the valuation puzzle leaves off. They spell out which future paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than today's price on the Community page. Each scenario ties its number to a clear view on how Carel Industries' revenue mix, margin profile and risk picture might evolve, which you can revisit as fresh information comes through.
One of the top community narratives on Carel Industries: 27% undervalued
"The company's decisive pivot into data center cooling, supported by proprietary sensor technology, leadership in fast-growing liquid cooling, and direct engagement with hyperscalers…"
Read one of the top narratives on Carel Industries
Do you think there's more to the story for Carel Industries? Head over to our Community to see what others are saying!
The Bottom Line
Carel Industries currently trades on earnings multiples that lean toward overvalued when set against sector peers and a tailored fair P/E range. That premium only makes sense if the business can sustain strong profitability and keep capital needs in check. For you as an investor, the key question is whether revenue growth and margins stay robust enough to support that richer P/E, or whether expectations cool and the valuation gradually comes back toward the sector pack.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com