
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ASX Growth Stocks With High Insider Stakes
As the Australian market grapples with rising oil prices and inflationary pressures, investors are navigating a complex landscape marked by heightened interest-rate expectations and volatile equity valuations. In this environment, growth companies with high insider ownership can offer a compelling proposition, as insider stakes often signal confidence in the company's long-term potential amidst broader market uncertainties.
Top 10 Growth Companies With High Insider Ownership In Australia
| Name | Insider Ownership | Earnings Growth |
| Wisr (ASX:WZR) | 10.3% | 94.2% |
| Starpharma Holdings (ASX:SPL) | 19.3% | 92% |
| SKS Technologies Group (ASX:SKS) | 19.3% | 27.7% |
| PDI Gold (ASX:PDI) | 10.4% | 63.6% |
| Forrestania Resources (ASX:FRS) | 24.7% | 126.7% |
| Elsight (ASX:ELS) | 12.5% | 58.5% |
| DXN (ASX:DXN) | 13.5% | 129.3% |
| Austral Resources Australia (ASX:AR1) | 23.5% | 28.2% |
| Adveritas (ASX:AV1) | 17.6% | 99.9% |
| Advanced Engineered Materials (ASX:AEM) | 35.1% | 58.7% |
We'll examine a selection from our screener results.
Chrysos (ASX:C79)
Simply Wall St Growth Rating: ★★★★☆☆
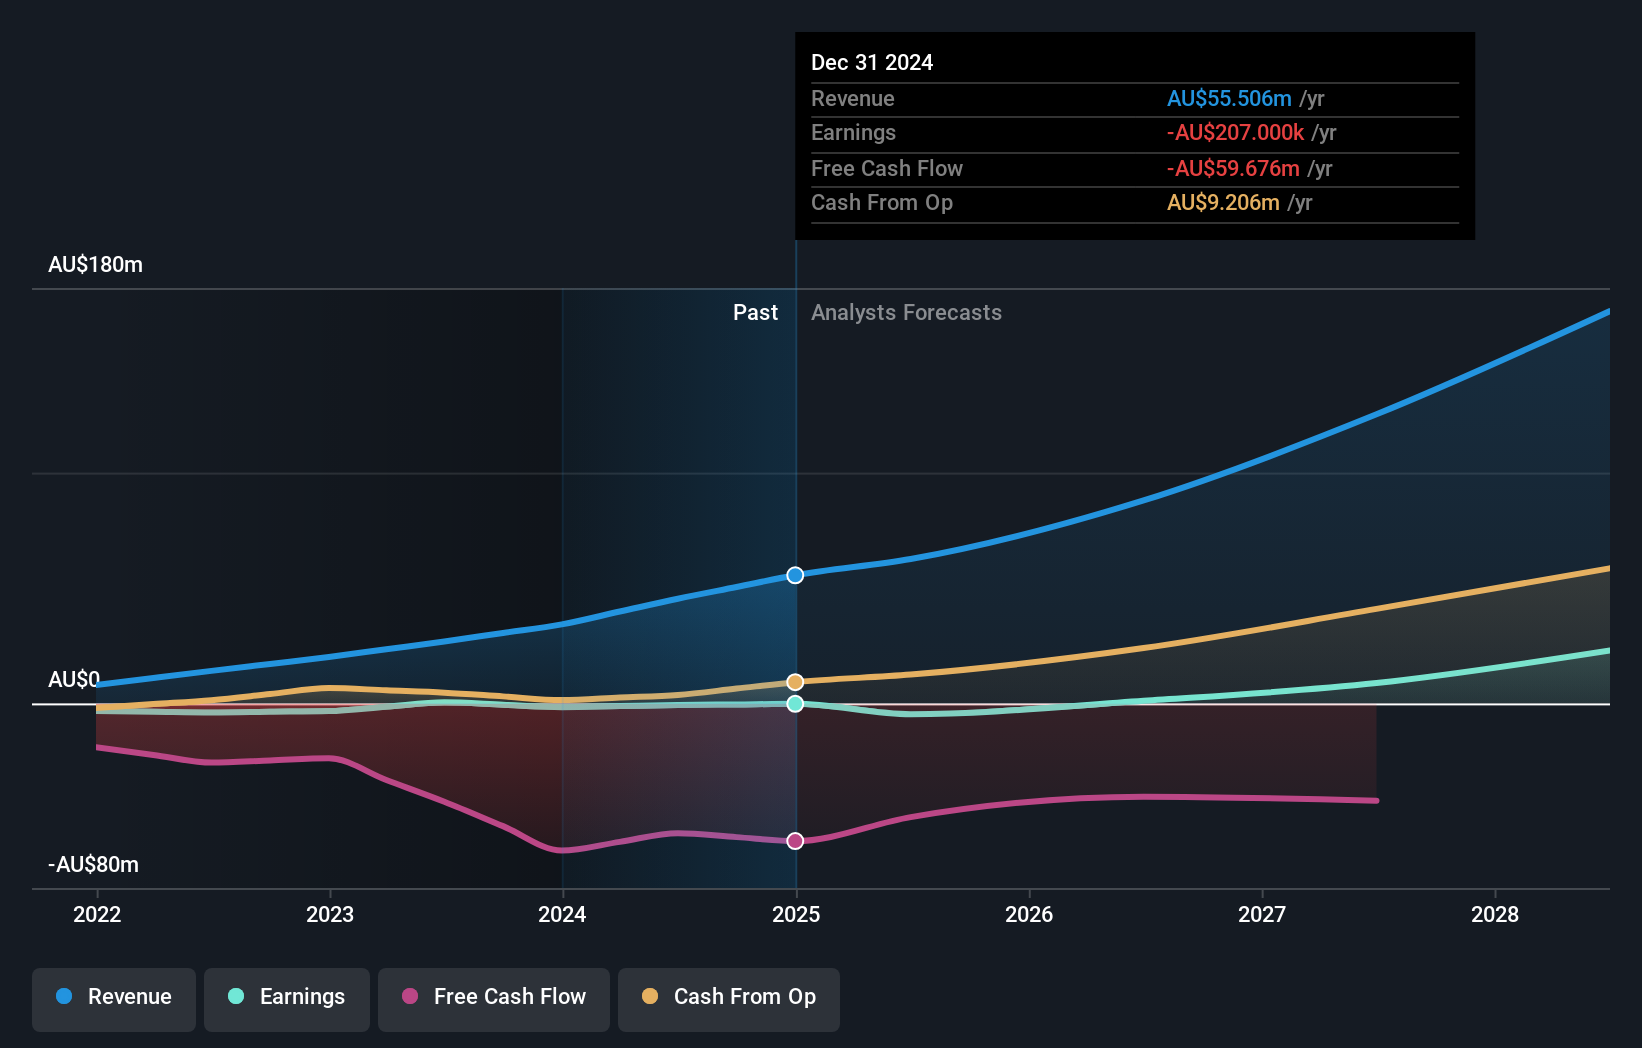
Overview: Chrysos Corporation Limited develops and supplies mining technologies across Europe, Africa, the Asia Pacific, North America, and South America with a market cap of A$819.07 million.
Operations: Chrysos Corporation Limited generates revenue of A$88.11 million from its mining services segment across multiple continents.
Insider Ownership: 10.8%
Revenue Growth Forecast: 19.1% p.a.
Chrysos Corporation Limited has shown strong growth, with revenue increasing to A$89.17 million and a return to profitability, reporting a net income of A$1.79 million for the year ending June 2026. Insider ownership remains high, with more shares bought than sold recently. The company's earnings are forecast to grow significantly at 36.1% annually, outpacing the Australian market's average growth rate of 11.1%, despite its return on equity being lower than benchmarks in three years' time.
- Delve into the full analysis future growth report here for a deeper understanding of Chrysos.
- Insights from our recent valuation report point to the potential overvaluation of Chrysos shares in the market.
Lycopodium (ASX:LYL)
Simply Wall St Growth Rating: ★★★★☆☆
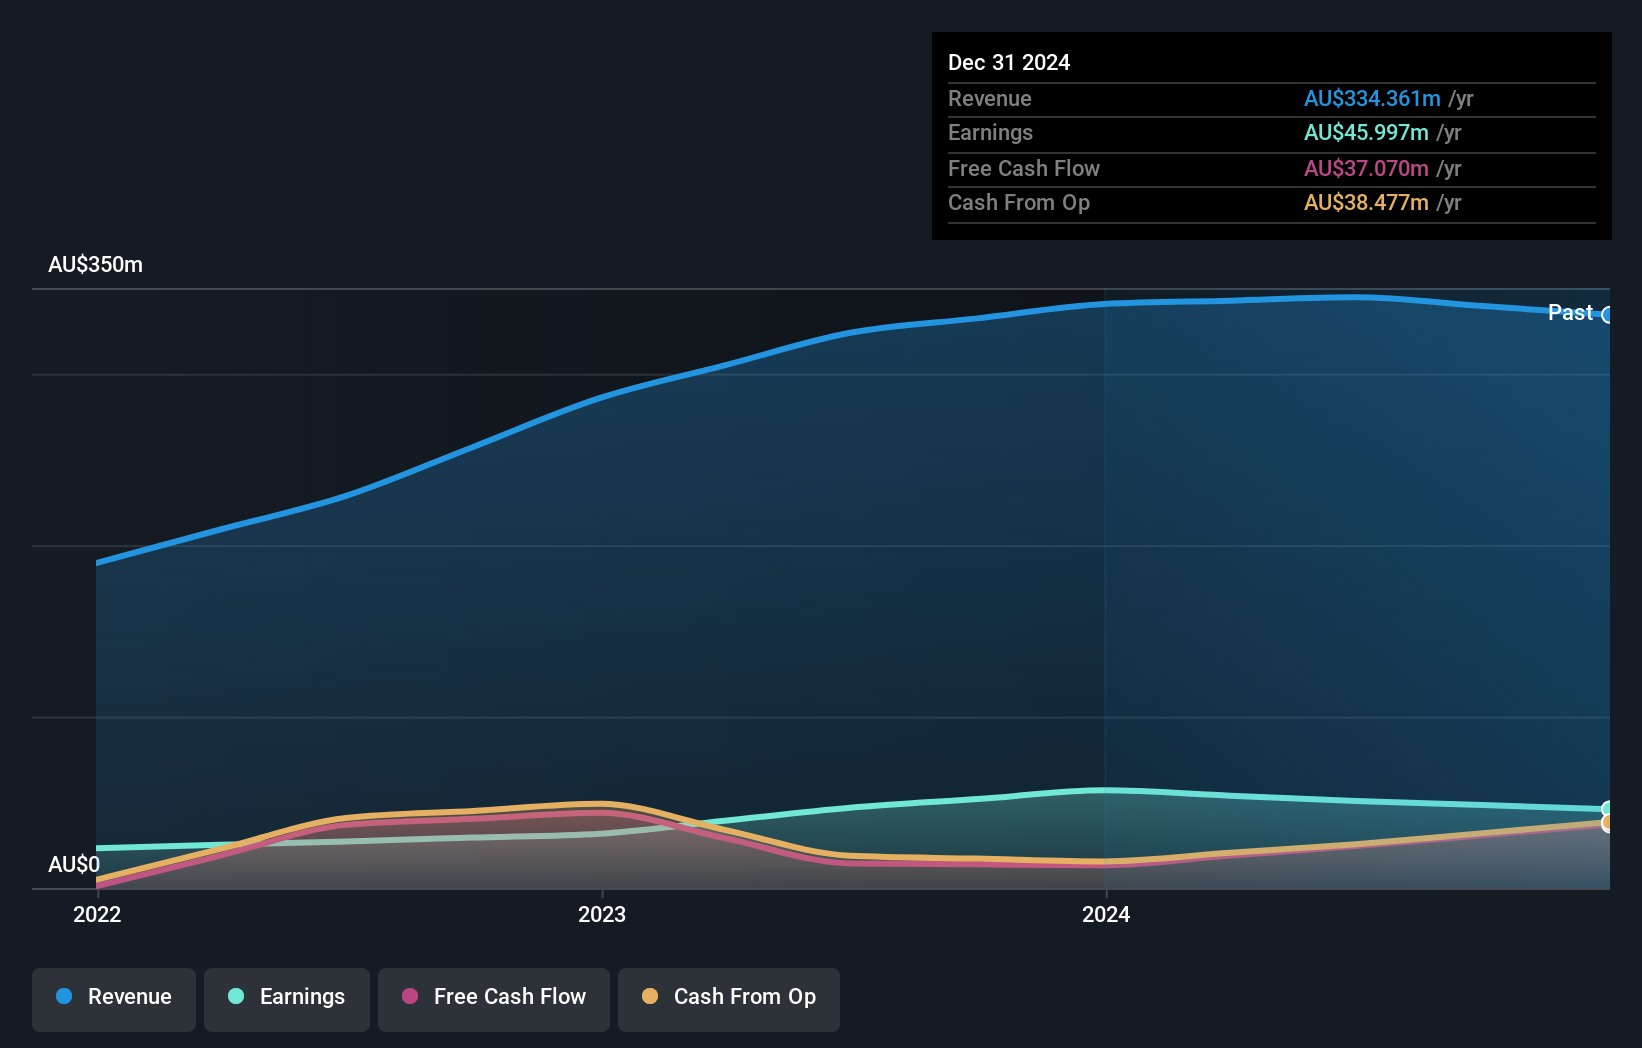
Overview: Lycopodium Limited offers engineering and project delivery services across the resources, rail infrastructure, and industrial processes sectors in Australia, with a market cap of A$861.82 million.
Operations: The company's revenue segments are distributed as follows: Africa contributes A$40.75 million, the Americas account for A$166.06 million, and the Asia Pacific region generates A$218.06 million.
Insider Ownership: 32.6%
Revenue Growth Forecast: 13.5% p.a.
Lycopodium's insider ownership is complemented by a forecasted revenue growth of 13.5% annually, outpacing the Australian market. Despite earnings growing at 11.9% per year, which is above market average but not significant, the company trades at 22.5% below estimated fair value. Recent results show sales and revenue increases to A$374.02 million and A$377.55 million respectively for FY2026, with net income slightly declining to A$40.17 million from A$42.22 million previously reported.
- Navigate through the intricacies of Lycopodium with our comprehensive analyst estimates report here.
- The analysis detailed in our Lycopodium valuation report hints at an inflated share price compared to its estimated value.
Turaco Gold (ASX:TCG)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Turaco Gold Limited is a gold exploration and development company operating in Cote d'Ivoire, with a market cap of A$917.70 million.
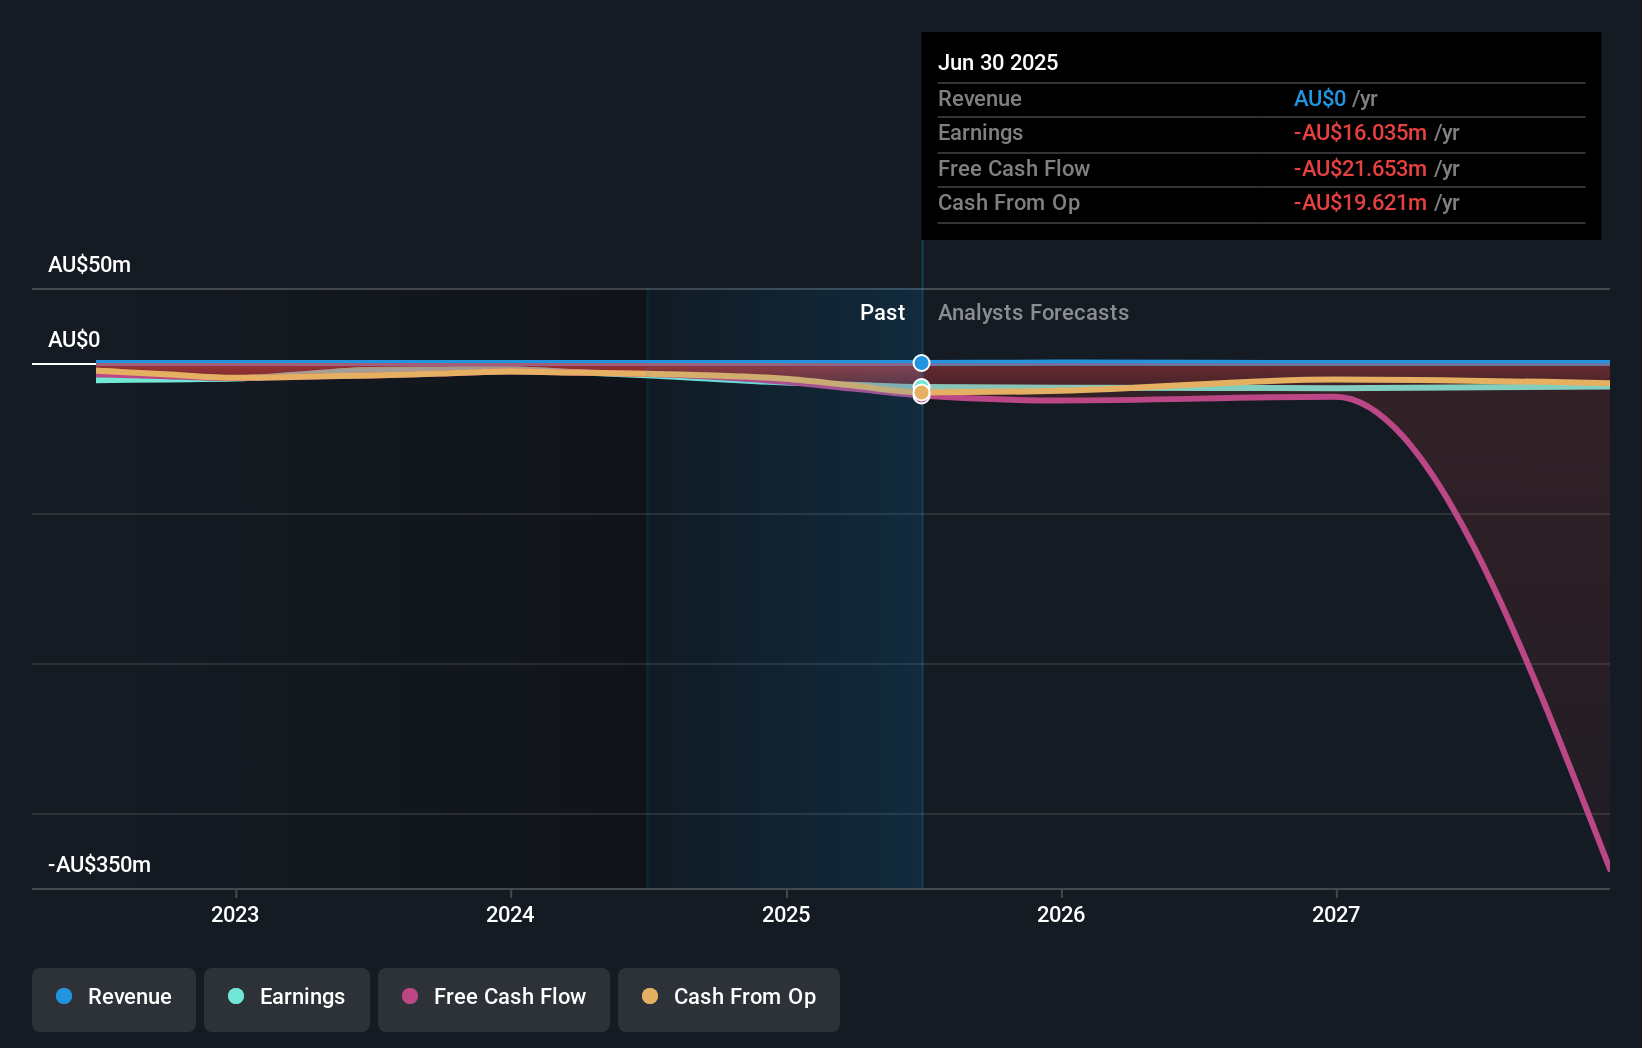
Operations: Turaco Gold Limited does not currently have distinct revenue segments, as it focuses on gold exploration and development in Cote d'Ivoire.
Insider Ownership: 18.5%
Revenue Growth Forecast: 60.8% p.a.
Turaco Gold's high insider ownership aligns with its anticipated revenue growth of 60.8% per year, significantly outpacing the Australian market. Despite a current net loss of A$18.67 million for H1 2026, the company is expected to become profitable within three years, surpassing average market growth rates. Trading at 90.3% below estimated fair value, Turaco faces financial challenges with less than a year of cash runway and low forecasted return on equity at 6.9%.
- Get an in-depth perspective on Turaco Gold's performance by reading our analyst estimates report here.
- Our valuation report here indicates Turaco Gold may be overvalued.
Seize The Opportunity
- Get an in-depth perspective on all 113 Fast Growing ASX Companies With High Insider Ownership by using our screener here.
- Interested In Other Possibilities? The end of cancer? These 34 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com