
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Whirlpool (WHR) And The Margin Recovery Story Behind Its Valuation Reset
Whirlpool (WHR) has been drawing attention after recent share price weakness, with the stock closing at US$35.21 as returns have fallen over the past month and past 3 months. Investors are reassessing what this level implies.
Over a longer stretch, Whirlpool has been struggling for momentum, with the share price return down 52.74% year to date and total shareholder return declining 60.76% over the past year. This points to fading confidence and a higher perceived risk profile despite recent business results.
Spot opportunities that match Whirlpool's reset expectations by scanning a curated group of 32 high quality undervalued stocks with resilient cash flows and balance sheets.
At roughly US$35 a share after recent steep declines, Whirlpool now trades on expectations that already appear significantly reset. Do those terms still offer more potential upside than downside for new buyers?
Most Popular Narrative: 31.7% Undervalued
Whirlpool's most followed narrative pegs fair value at $51.55, well above the recent $35.21 share price. This frames the current selloff in a very different light.
Recent and ongoing restructuring, cost takeout programs, and supply chain efficiencies are expected to deliver structural operating margin improvement, even as current headwinds fade.
Strengthened domestic U.S. manufacturing footprint positions Whirlpool to be a primary beneficiary of forthcoming tariff implementation, which will improve competitive positioning, support pricing power, and drive margin recovery as imported inventory clears and trade policies take full effect.
Want to see how this margin story translates into a higher fair value for Whirlpool? The key pieces are revenue growth, slimmer costs, and a richer earnings multiple that ties it all together.
Result: Fair Value of $51.55 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Whirlpool’s reliance on slow growing core markets and higher interest costs after recent refinancing could challenge that recovery story and keep pressure on returns.
Find out about the key risks to this Whirlpool narrative.
Another View: Whirlpool On Earnings Multiples
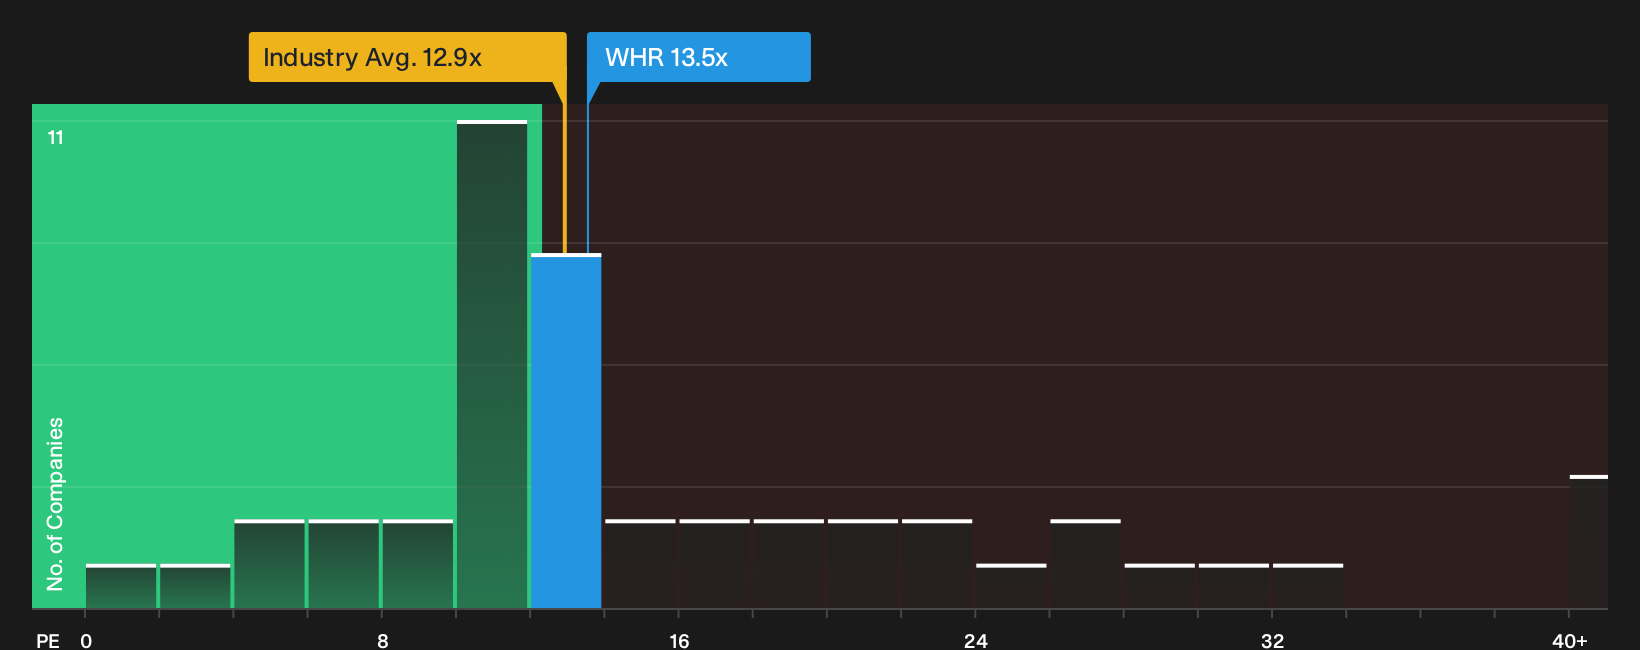
The first take presents Whirlpool as about 31.7% undervalued versus a fair value of $51.55. On plain P/E math, however, the story tilts in the opposite direction, with the stock at 13.5x earnings compared with 12.9x for the US Consumer Durables group and 9.5x for close peers.
That gap, when set against a fair ratio of 26.8x, leaves investors weighing whether this is a mispriced opportunity or a value trap that still carries plenty of performance risk in the near term.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Whirlpool is clearly split. Treat this as a prompt to move fast, review the full data set, and come to your own view by weighing the 3 key rewards and 3 important warning signs.
Looking for more Whirlpool investment ideas?
If Whirlpool’s reset valuation has your attention, do not stop here. Broader opportunities often appear where pricing, quality, and risk all line up more cleanly.
- Target strong value setups by reviewing the 32 high quality undervalued stocks that combine compressed valuations with solid business profiles and potential for sentiment to shift.
- Build a steadier income stream by focusing on 6 dividend fortresses that aim to balance yield with financial resilience and consistent shareholder payouts.
- Prioritize resilience under stress by scanning 11 resilient stocks with low risk scores that screen for healthier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com