
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Flotek Industries (FTK) Could Be 29% Below Fair Value As Lawsuits Test The Story
Why Flotek Industries Is Back In The Spotlight
Flotek Industries (FTK) is under scrutiny after multiple law firms launched class action lawsuits tied to a canceled 10 year contract with the Puerto Rico Electric Power Authority.
Recent trading has been choppy. The share price is now at $27.33 after a 7 day share price return of 16.10% and a 30 day share price decline of 23.72%. Flotek Industries has delivered a 1 year total shareholder return of 139.32% and a very large 3 year total shareholder return approaching 5x, indicating notable long term momentum. At the same time, lawsuits and updated 2026 guidance are keeping short term sentiment on edge.
Scan how other materials and energy transition plays are reacting to similar contract and legal headlines with a hand picked set of 11 resilient stocks with low risk scores that aim to keep downside in focus.
Flotek Industries is being priced off a sharp rally on the back of lawsuits, fresh guidance and a wide gap to analyst targets. Is this the moment to step in, or does patience for a better entry make more sense?
Most Popular Narrative: 28.5% Undervalued
Flotek Industries closed at $27.33 while the most followed narrative pins fair value at $38.25, so the gap between story and screen is wide.
Multi-year contracts and a growing customer base for high-margin Data Analytics offerings (including both power generation and custody transfer segments) provide significant revenue visibility and margin expansion potential, particularly as these segments shift to become the majority profit contributors by 2026.
Curious what needs to happen for that premium valuation to hold. The narrative leans on steady top line expansion, slimmer margins and a much richer future earnings multiple. The real swing factor is how those assumptions interact over time.
Result: Fair Value of $38.25 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the PREPA termination and heavy reliance on large customers mean any further contract disputes or renegotiations could quickly challenge the bullish Flotek Industries narrative.
Find out about the key risks to this Flotek Industries narrative.
Another View On Flotek Industries Valuation
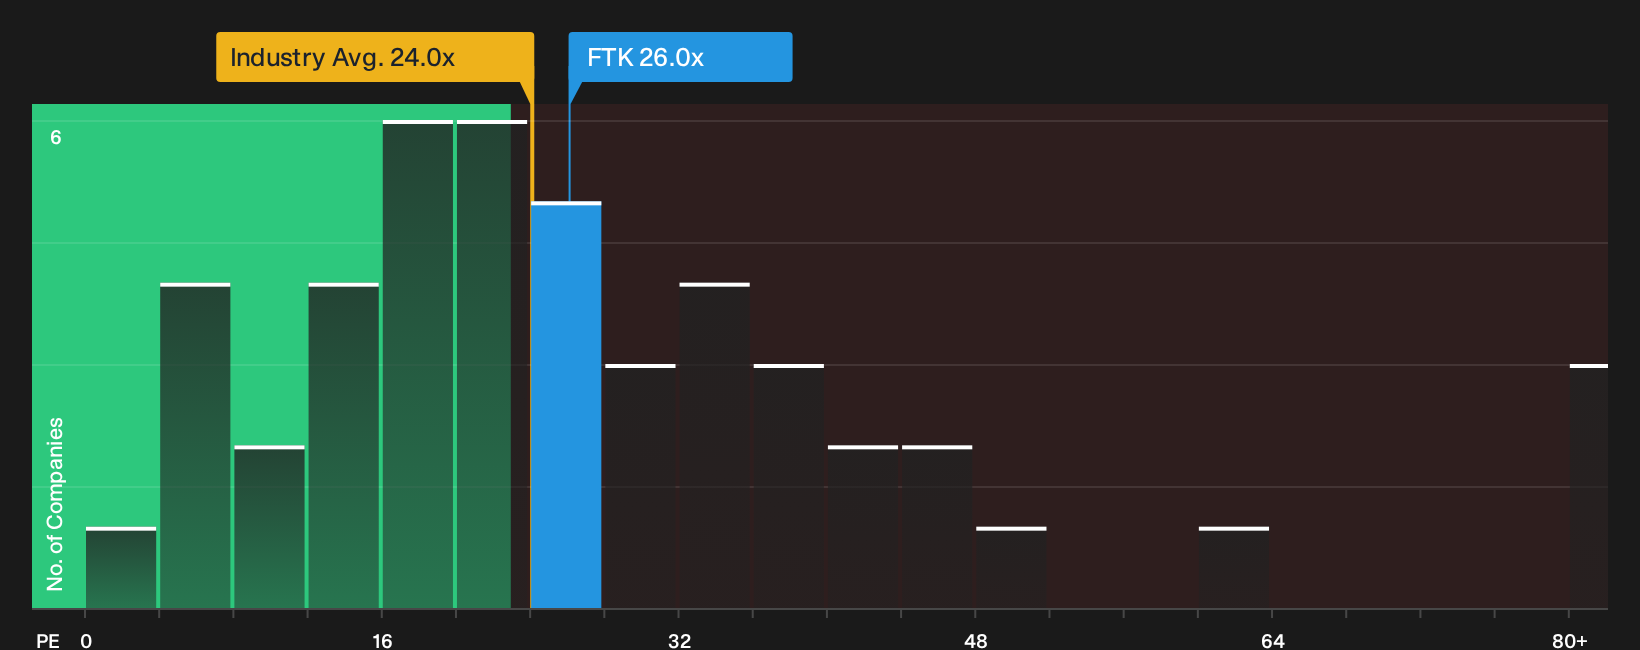
Analysts frame Flotek Industries as 28.5% undervalued, yet the current P/E of 26x sits above both the US Chemicals sector on 24x and the fair ratio of 16x. That kind of premium can reward patience or punish optimism, depending on how expectations reset.
Investors who want the numbers behind that premium can stress test the earnings assumptions and compare them with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed feelings on Flotek Industries after all this. If that sounds familiar, consider acting while attention is high and pressure test both sides of the story with the 2 key rewards and 3 important warning signs.
Looking for more Flotek Industries style ideas?
You do not need to stop with Flotek Industries. Broaden your watchlist with focused stock ideas that match your risk, income, and value priorities.
- Target potential bargains by scanning a curated pool of companies that screen well on quality and value with the 32 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with sturdier finances using the list of solid balance sheet and fundamentals (23 results).
- Boost your income focus by zeroing in on higher yielding opportunities through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com