
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Vail Resorts (MTN) Moved Today?
Why the Oasis slate matters for Vail Resorts investors
Vail Resorts (MTN) is back in the spotlight after Oasis Management put forward high profile director candidates, including Bob Chapek and Olympian Picabo Street, intensifying scrutiny of the company’s governance and long term direction.
The governance battle has arrived against a backdrop of mixed performance for Vail Resorts. The share price closed at $140.09 after a 5.07% 1 day share price return and a 4.58% year to date share price return. However, the 3 year total shareholder return is down 34.95% and the 5 year total shareholder return is down 43.81%, pointing to short term momentum picking up while longer term holders have faced sustained pressure.
Compare how Vail Resorts stacks up on governance and fundamentals next to a hand picked list of solid balance sheet and fundamentals (23 results).
After a 5.07% jump and a share price around $140, Vail Resorts trades at a reported 47% discount to intrinsic value and about 5% below analyst targets. Is that caution earned, or is it a mispricing of boardroom and weather risk?
Most Popular Narrative: 5.7% Undervalued
On the widely followed narrative view, Vail Resorts carries a fair value of $148.50 against a last close of $140.09. This puts the valuation debate squarely on future earnings power and capital returns rather than the recent share price bounce.
Vail Resorts is on track to deliver $100 million in annualized cost efficiencies by the end of fiscal year 2026 through its Resource Efficiency Transformation Plan, which could positively impact earnings by improving net margins. Continued investment in guest experience through lift, terrain, and food and beverage expansions, along with technology upgrades like My Epic App and AI capabilities, are expected to drive higher ancillary revenue and overall customer satisfaction, contributing positively to revenue growth.
Want to see the math behind that fair value gap? The narrative leans on a specific mix of revenue progression, margin rebuild, and future earnings multiples that are not obvious from the current share price chart.
Result: Fair Value of $148.50 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Vail Resorts faces real pressure if weaker skier visits and weather hit pass sales harder, or if currency swings weigh more heavily on already narrow margins.
Find out about the key risks to this Vail Resorts narrative.
Another view on Vail Resorts valuation
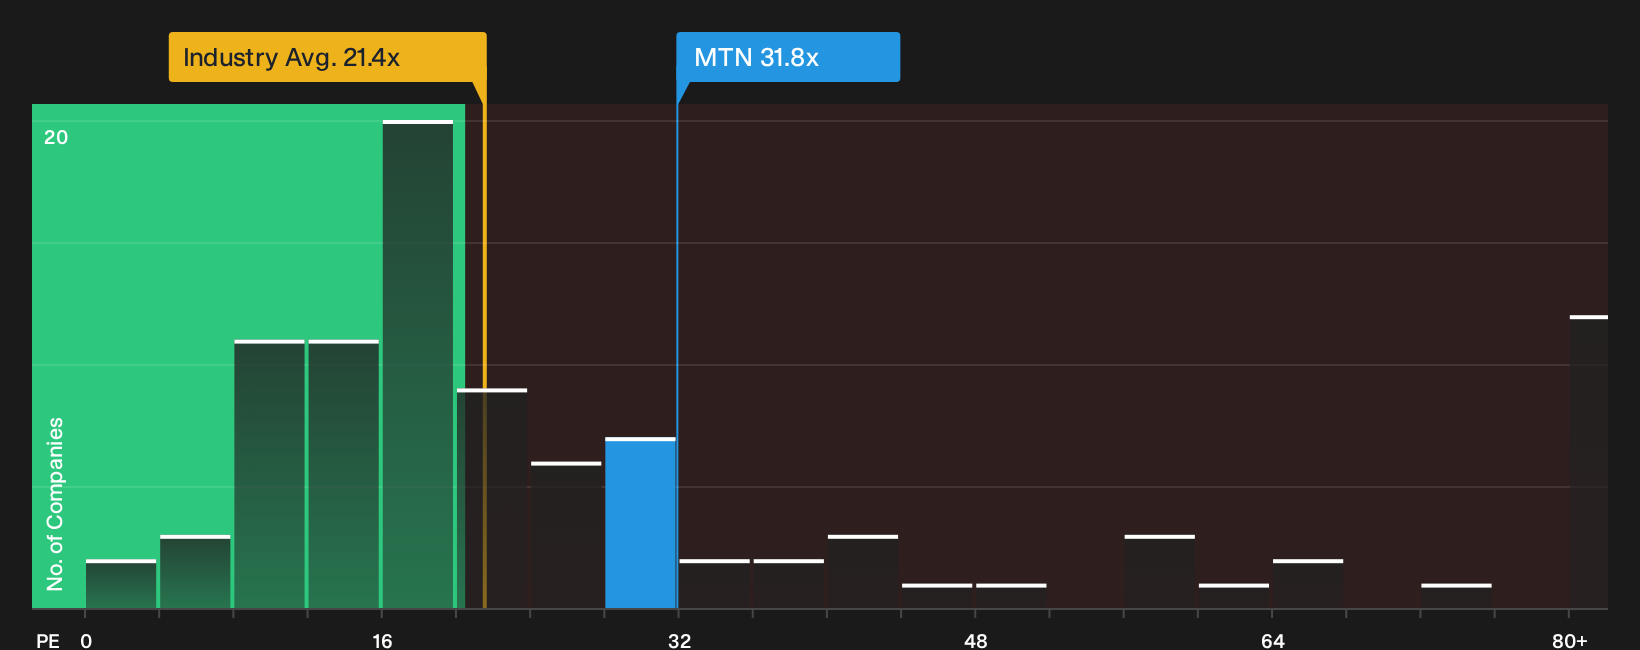
There is a twist when you look at Vail Resorts through earnings multiples. The stock trades on a P/E of 31.8x, while the US Hospitality industry sits near 21.4x and peers average 20.6x. The fair ratio is 26.5x, which points to a richer price tag than the first fair value estimate suggests. Is this a quality premium, or just less room for error if weather and visitation stay choppy?
For a closer look at how those earnings-based figures stack up against what the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this Vail Resorts story, you can see both optimism and unease pulling in opposite directions, so move quickly, review the numbers for yourself, then weigh the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Vail Resorts?
If Vail Resorts has you thinking harder about risk, reward, and price, use that energy now and scan for other opportunities before the next move passes you by.
- Target quality at a discount by checking stocks screened as 32 high quality undervalued stocks that combine supportive fundamentals with more appealing entry prices.
- Prioritize resilience and focus on companies filtered through our 11 resilient stocks with low risk scores that aim to limit downside shocks.
- Hunt for tomorrow's potential leaders today by scanning the 15 high quality undiscovered gems before they attract broader market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com