
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Did Kenon Holdings (TASE:KEN) Stock Drop After Its Latest Update?
Why Kenon Holdings Stock Is Back In Focus After Its Latest Earnings Release
Kenon Holdings (TASE:KEN) has moved back onto investors watchlists after its second quarter 2026 earnings report, which showed higher sales, net income and earnings per share compared with a year earlier.
Short term sentiment around Kenon Holdings has cooled, with the share price declining 5.4% over the past day and 7.5% year to date. However, the 1 year total shareholder return of 36.9% and the very large 3 year total shareholder return above 200% point to momentum built over a longer horizon as investors reassess the company after its strong earnings release.
Scan beyond Kenon Holdings and explore other power and infrastructure stocks showing strong earnings shifts with our hand picked list of solid balance sheet and fundamentals (194 results)
Kenon Holdings just paired strong recent earnings with a share price that has cooled in the short term. Are you looking at a business catching up to its results, or a mood swing that the valuation has yet to fully reflect?
Preferred P/E of 28.8x for Kenon Holdings: Is it justified?
On a simple earnings yardstick, Kenon Holdings trades on a P/E of 28.8x, which screens as good value against its direct peer group but looks expensive relative to the broader Asian renewable energy space.
The P/E multiple captures what investors are currently paying for each unit of reported earnings. It effectively bundles expectations about future profitability, capital allocation and risk into a single figure.
For a power and infrastructure operator like Kenon Holdings, that lens matters because cash generation can be tied to long term assets and contracts. The market is constantly weighing how durable those earnings streams are over time.
Compared with its immediate peers on this preferred multiple, Kenon Holdings looks cheap based on the data available, with its 28.8x P/E described as good value against a peer average of 84.6x. This suggests investors are not assigning the same earnings premium to this business as they are to similar companies.
The contrast is sharp once you widen the lens. The same 28.8x P/E is described as expensive versus the Asian renewable energy industry average of 14.8x, which implies the broader sector is priced on far lower earnings expectations than the valuation currently attached to Kenon Holdings.
See what the numbers say about this price — find out in our valuation breakdown..
Result: Price-to-earnings of 28.8x (ABOUT RIGHT)
Still, the Kenon Holdings story can change quickly if power prices soften or if large scale project delays weigh on reported earnings and investor confidence.
Find out about the key risks to this Kenon Holdings narrative.
Another View On Kenon Holdings Valuation
The earnings multiple paints one picture, but the SWS DCF model tells a different story for Kenon Holdings. At ₪200 per share, the stock is described as trading about 14.8% below an estimated future cash flow value of roughly ₪234.88. Does that signal mispricing, or is it simply a margin for error?
For a closer look at how this cash flow based estimate is built, including the key inputs that drive it, Look into how the SWS DCF model arrives at its fair value.
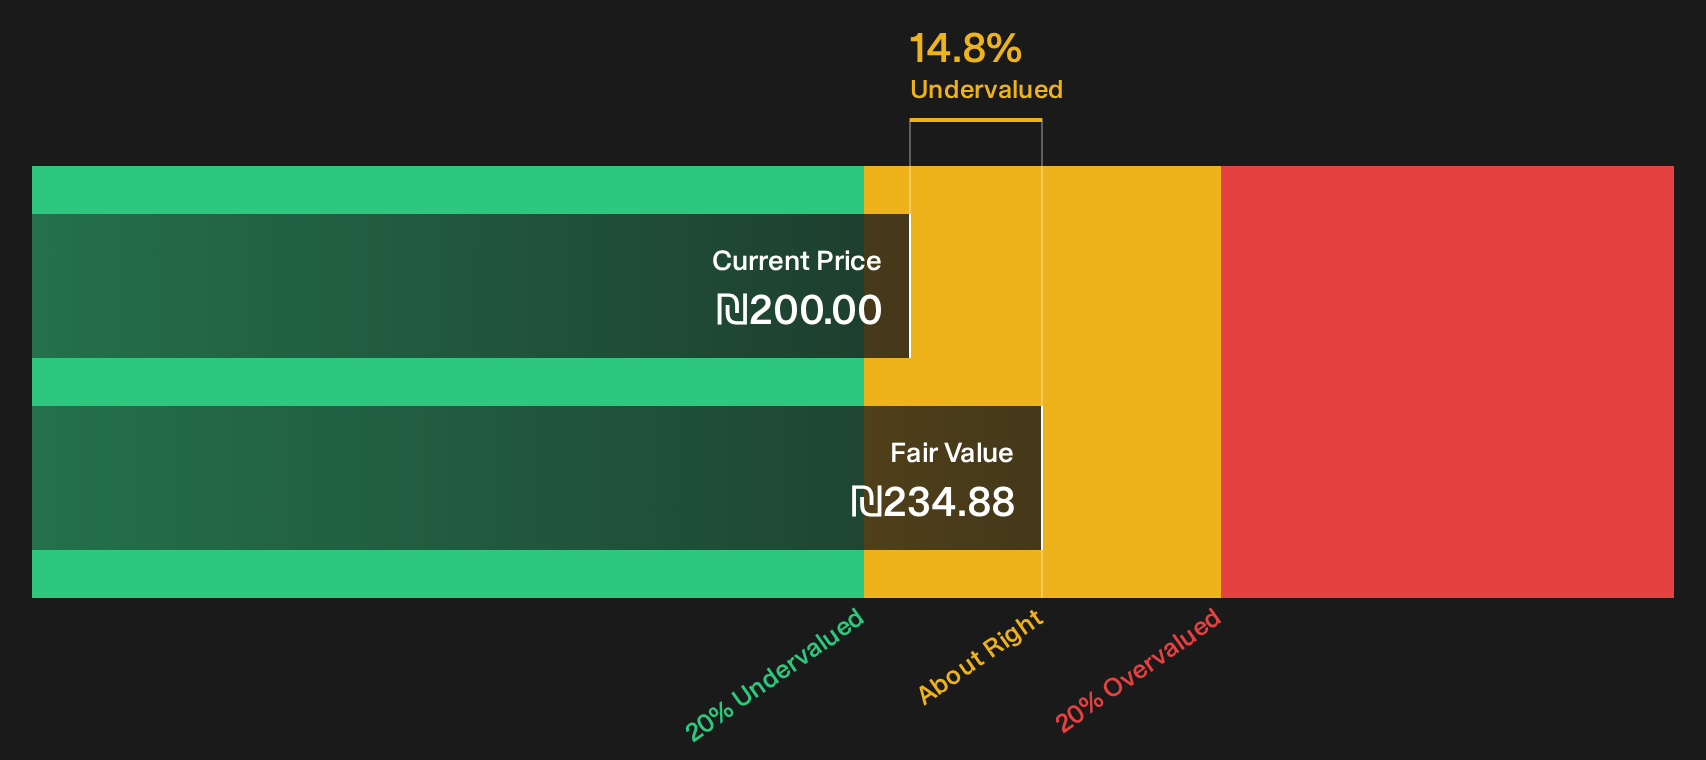
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kenon Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the mixed signals around Kenon Holdings lean more towards optimism or caution? Review the underlying data yourself and weigh both sides of the story using our breakdown of 1 key reward and 3 important warning signs
Ready For More Ideas Beyond Kenon Holdings?
If you stop with Kenon Holdings, you risk missing other opportunities that fit your style even better. Take a few minutes to scan focused shortlists built to surface clear, data backed ideas across different types of businesses.
- Target income first and hunt for resilient payouts with the 161 dividend fortresses.
- Spot potential mispricings early by working through the 183 high quality undervalued stocks.
- Prioritise capital protection and filter for sturdier balance sheets using the 99 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com