
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IDEXX Laboratories (IDXX) Keeps Growing, Is The Stock Still A Bargain?
IDEXX Laboratories (IDXX) has drawn investor attention after a period of weaker share performance, with the stock down over the past month and the past 3 months despite ongoing revenue and net income growth.
Over the past year, momentum in IDEXX Laboratories has cooled, with the share price down year to date and the 1-year total shareholder return declining 21.28%. However, the 3-year total shareholder return of 11.98% still reflects a more constructive longer-term picture.
Reset your watchlist by comparing IDEXX Laboratories with a hand-picked group of 15 high quality undiscovered gems that are also growing revenues and earnings while staying off most investors' radar.
IDEXX Laboratories keeps growing its top and bottom line while the share price has reset over the past year. Is this the moment to lean into that disconnect, or is it better to wait for an even cheaper entry before the valuation work begins?
Most Popular Narrative: 28.8% Undervalued
On the current numbers, the most followed narrative pegs IDEXX Laboratories at a fair value of $709.14 versus a last close of $504.70, which puts a spotlight on the assumptions doing the heavy lifting in that gap.
Rapid adoption of innovative diagnostic platforms such as inVue Dx, Catalyst Cortisol, and Cancer Dx are expanding IDEXX's addressable market and boosting recurring consumables demand, which is likely to drive sustained revenue and margin growth as new product usage ramps and menu breadth increases.
Read the complete narrative. Read the complete narrative.
Want to see what turns that product story into a higher fair value for IDEXX Laboratories? The narrative leans heavily on compounding revenue, fatter profit margins, and a premium future earnings multiple that assumes the model holds. Curious which specific growth and profitability paths underpin that price and how far they stretch expectations?
Result: Fair Value of $709.14 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, IDEXX Laboratories faces two pressure points that could challenge this fair value story: softer U.S. clinical visit trends and tougher pricing discussions with larger veterinary groups.
Find out about the key risks to this IDEXX Laboratories narrative.
Another View on IDEXX Laboratories Valuation
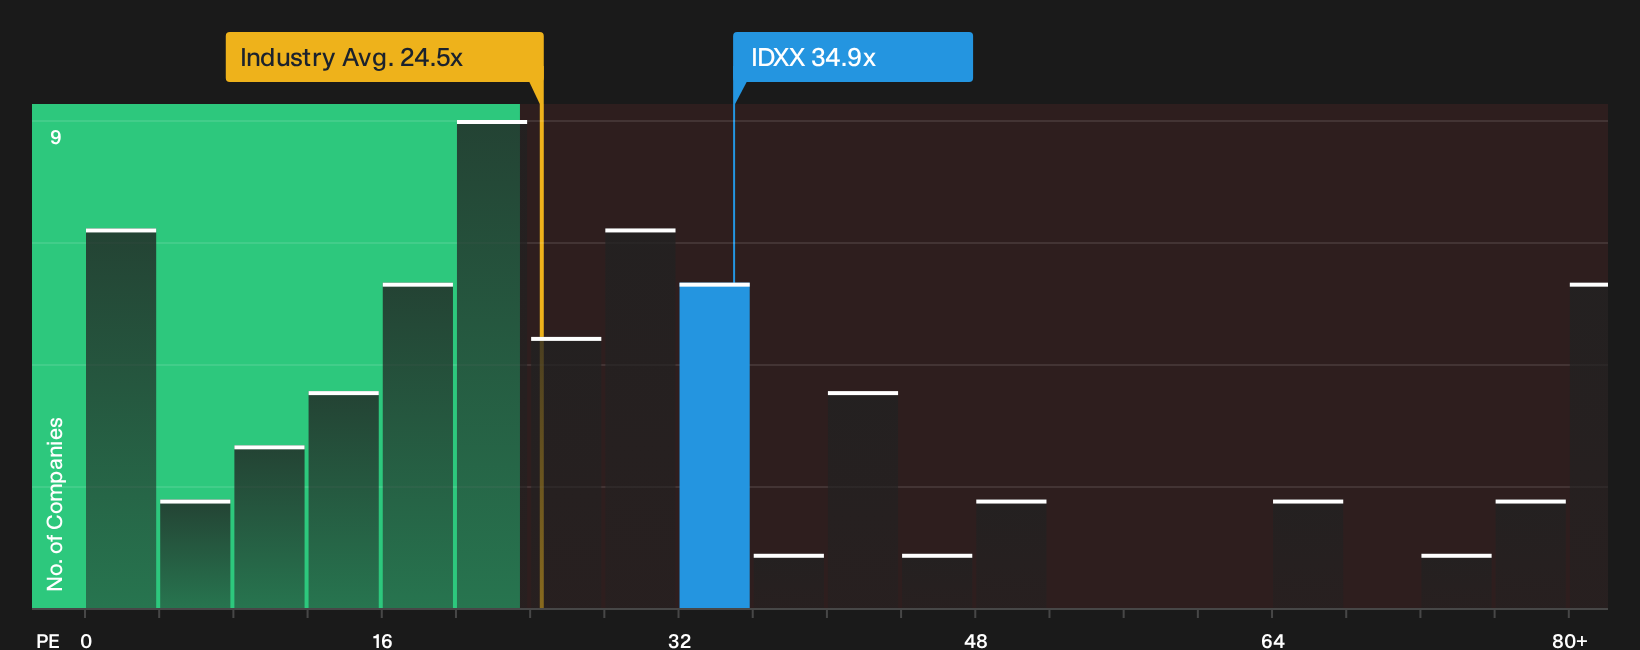
The analyst narrative frames IDEXX Laboratories as 28.8% undervalued, yet the current P/E of 34.9x tells a tougher story. That multiple is richer than the US Medical Equipment industry at 24.5x, above peers at 32.7x, and ahead of a fair ratio of 29.7x, which suggests less room for error if growth or margins soften.
For investors weighing that gap, the question becomes simple. Is paying above the fair ratio and sector benchmarks a price worth accepting for this earnings profile, or is it better to wait until the valuation sits closer to where the market could reasonably drift over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the bullish fair value case and the rich P/E for IDEXX Laboratories is normal. The best antidote is to interrogate the numbers yourself right now and pressure test both sides of the story using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond IDEXX Laboratories?
If IDEXX Laboratories has you rethinking your watchlist, use this moment to widen your opportunity set before the next wave of prices moves without you.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive entry points through the 32 high quality undervalued stocks.
- Strengthen your defensive side by focusing on businesses with sturdy finances and clean balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Seek resilient compounding by filtering for companies with dependable cash returns to shareholders with the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com