
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ensign Group (ENSG) Faces Legal Scrutiny, Is A 21% Undervalued View Still Intact?
Ensign Group (ENSG) is back under the microscope after law firm Kaplan Fox & Kilsheimer opened an investigation into potential securities violations, following a Hunterbrook Media report alleging inadequate care and misleading quality data.
Ensign Group shares trade at US$173.98 after recent volatility around the Hunterbrook and Kaplan Fox headlines. The 1-day share price return of 0.69% and the 7-day share price return of 1.87% hint at stabilising sentiment, following a 30-day share price return that declined 4.22%.
Compare how Ensign Group stacks up on quality and resilience by scanning a curated 11 resilient stocks with low risk scores designed to hold up when headlines turn hostile.
The recent pullback alongside the legal headlines sits against a 90 day return of 15.44%. Is Ensign Group’s current price echoing its operations, or is it simply a reset in sentiment before valuation catches up?
Most Popular Narrative: 20.9% Undervalued
On the most followed narrative, Ensign Group’s fair value of $220 sits above the last close at $173.98. This puts the current selloff against a much richer long term earnings story.
A sizeable pipeline of low occupancy, clinically challenged acquisitions, particularly in Texas, creates room for operational turnaround using the existing cluster and ONE CLINICAL model, which can affect occupancy driven revenue and EBIT over multi year periods.
Want to see what powers that $220 figure? The narrative leans on steady top line expansion, thicker margins and a future profit multiple that assumes investors keep paying up for that growth profile.
Result: Fair Value of $220 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Ensign Group narrative can fray quickly if Medicare and Medicaid funding tightens or if its rapid roll up of underperforming facilities drags on longer than expected.
Find out about the key risks to this Ensign Group narrative.
Another View On Ensign Group’s Valuation
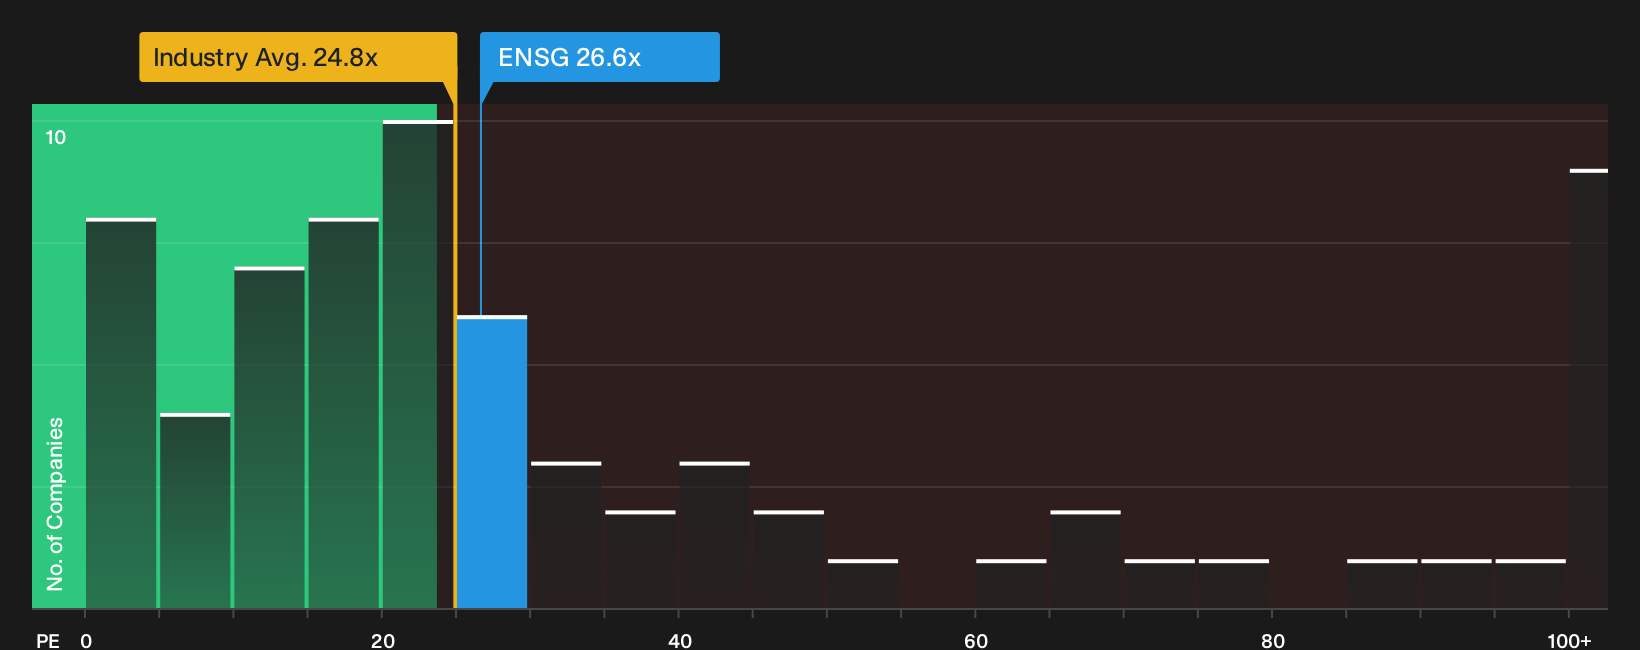
The story looks different once you shift from that narrative fair value to the straightforward P/E math. Ensign Group trades on a 26.6x P/E, which is higher than both the US Healthcare industry at 24.8x and its own 26.3x fair ratio. That gap suggests there may be less margin for error if growth or quality assumptions are challenged. This raises the question: how comfortable are you paying a premium for this type of earnings profile?
For a closer look at how this premium lines up against fundamentals and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of cautious headlines and valuation tension around Ensign Group feels unresolved, move quickly and review the underlying positives that investors are focusing on through the 4 key rewards
Looking for more investment ideas beyond Ensign Group?
If Ensign Group has sharpened your focus on quality and risk, do not stop here. Broader opportunity sits with other businesses that fit your criteria.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that filters for companies built to absorb shocks when headlines heat up.
- Hunt for potential mispricings by using the 15 high quality undiscovered gems that highlights strong fundamentals where attention has not fully arrived yet.
- Explore income-focused ideas through the 6 dividend fortresses that surfaces higher yielding stocks with an emphasis on stability and consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com