
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will New Denmark Factory Change Kitron Stock Narrative
- Kitron has announced plans for a new 8,850 square meter factory in Horsens, Denmark that will replace the current site. The facility is intended to support higher production capacity, more efficient workflows, and an expansion of its Danish workforce from about 150 to around 250 employees when fully utilised.
- The Horsens facility is being designed for regulated, high reliability sectors. Future Danish output could therefore shift further toward complex industrial and defense grade electronics where process control and certification requirements are critical.
- We will now look at how Kitron's investment narrative may be reshaped by its decision to build and own the Horsens facility.
Scan how Kitron's new factory plan compares with other manufacturers ramping up localized production and process control in our curated 39 power grid technology and infrastructure stocks
Kitron Investment Narrative Recap
For an investor in Kitron, the core belief is that an electronics manufacturing services provider with strong industrialization skills can keep winning work as customers demand localized, tightly controlled production. The Horsens project fits that story, but it is a long dated build that starts in 2027 and is not a major near term earnings catalyst.
The nearer focus still sits on filling the existing capacity in Europe and the U.S., managing tariffs, and protecting gross margins while material costs and defense mix remain tricky. The main risk is that utilization or regional demand dips before new projects, including Horsens, fully support the cost base.
Earlier expansion and ramp up of facilities in Norway and Sweden is the clearest reference point for this Danish move. Management has already committed to scaling within the EU and U.S., with a plan that can potentially triple output in those regions once fully used.
For you as a shareholder, the link between these announcements is execution. Kitron is layering on more bricks and mortar in several countries while still dealing with tariff exposure, Asia softness, and a weaker medical devices segment. The investment case leans heavily on converting a strong backlog into stable utilization across that wider footprint.
Kitron's narrative projects €1.6b revenue and €128.4 million earnings by 2029. This is based on an assumption of 19.1% yearly revenue growth and an earnings increase of about €60.8 million from €67.6 million today.
Uncover why Kitron's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
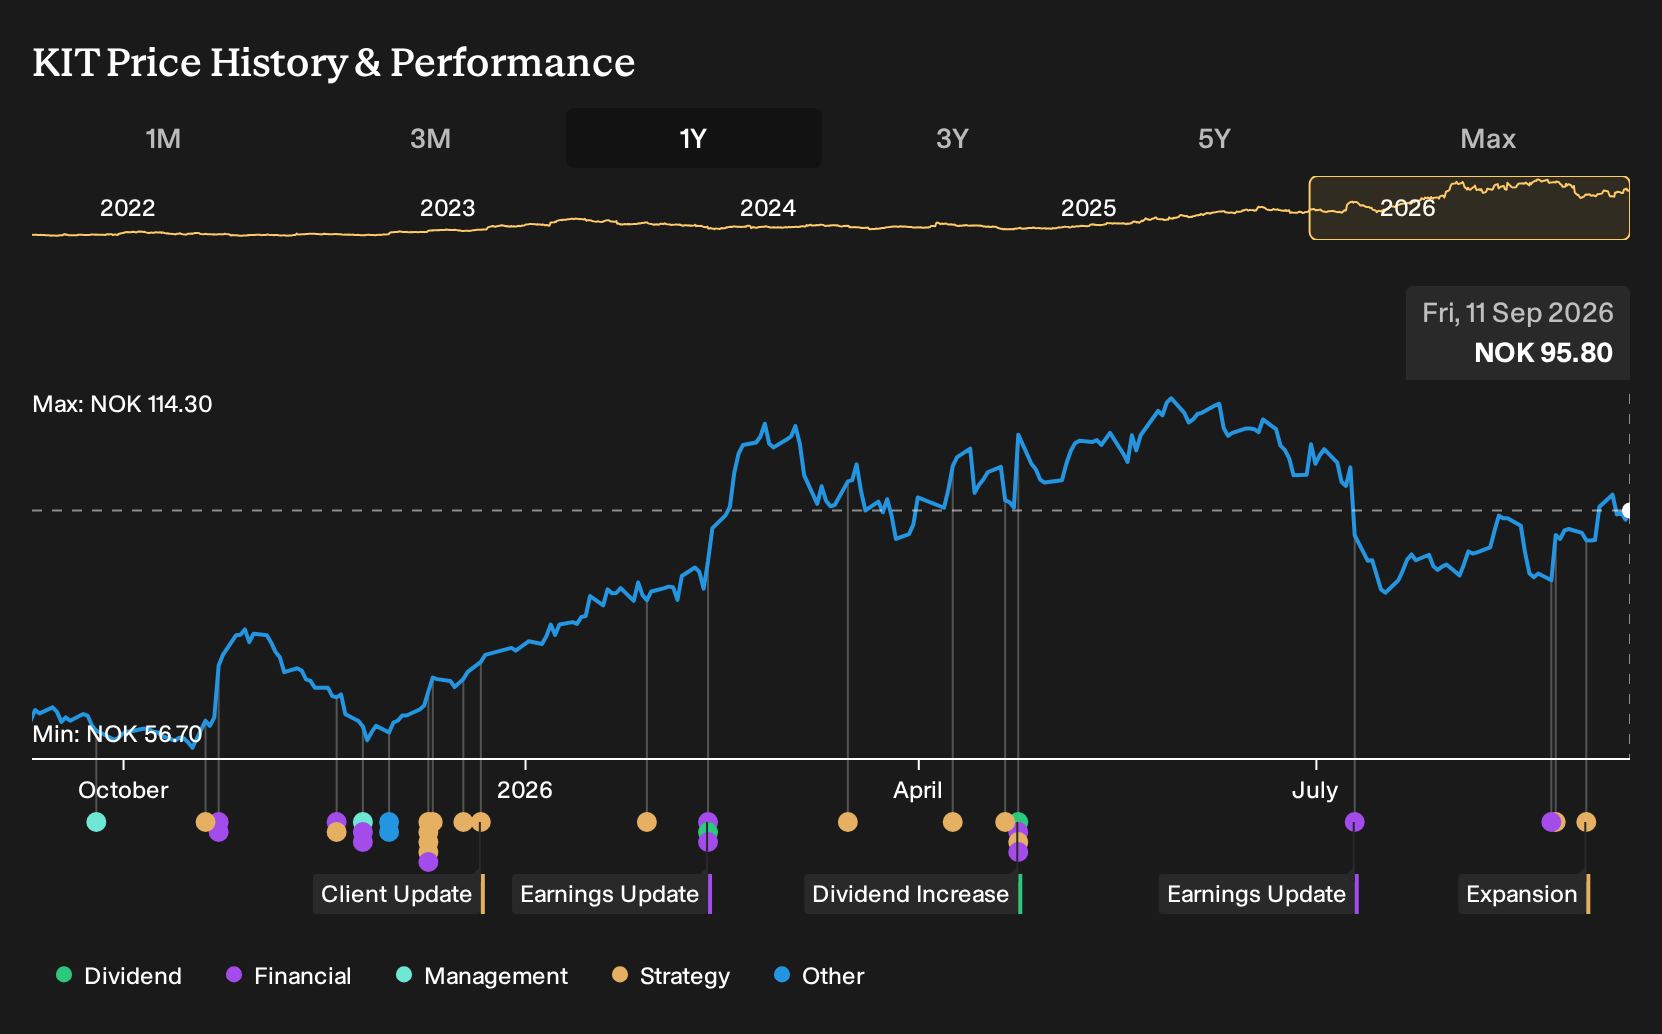
Exploring Other Perspectives
For Kitron, the more cautious analysts focus on margin pressure as the key swing factor. You can see that in their pre news forecasts, which still pencilled in about €1.6b of revenue and roughly €128.6 million of earnings by 2029, yet only supported a NOK95.97 target. These views could shift as the Horsens project is digested. It can therefore be useful to compare several narratives before deciding what you believe.
Explore 3 other Kitron fair value estimates, including one that suggests it could be worth just NOK95.97.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kitron research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Kitron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kitron's overall financial health at a glance.
Looking for more Kitron sized investment ideas?
Once you have a view on Kitron, it can help to line it up against other opportunities with clear financial traits so you can decide where it truly belongs in your portfolio.
- If you want potential value on your side, compare Kitron with a wider field of quality companies screened for both valuation and balance sheet strength using the 183 high quality undervalued stocks.
- For a focus on resilience and capital preservation, weigh Kitron against businesses that score well on stability, earnings consistency, and financial risk in the 99 resilient stocks with low risk scores.
- If your priority is resilience through strong finances, cross check Kitron with companies that pair solid cash flows and robust balance sheets in the list of solid balance sheet and fundamentals (194 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com